
From November 19 to December 9, Bản Việt Commercial Joint Stock Bank (BVBank, ticker BVB) is taking subscriptions and payments for 13 million public bonds with a face value of VND 100,000 each, VND 1,300 billion in total, over a 7-year term.Tin nhanh chứng khoán The first-year rate is 9.5% a year.FireAnt That is the figure savers see first, but it does not tell the whole story.
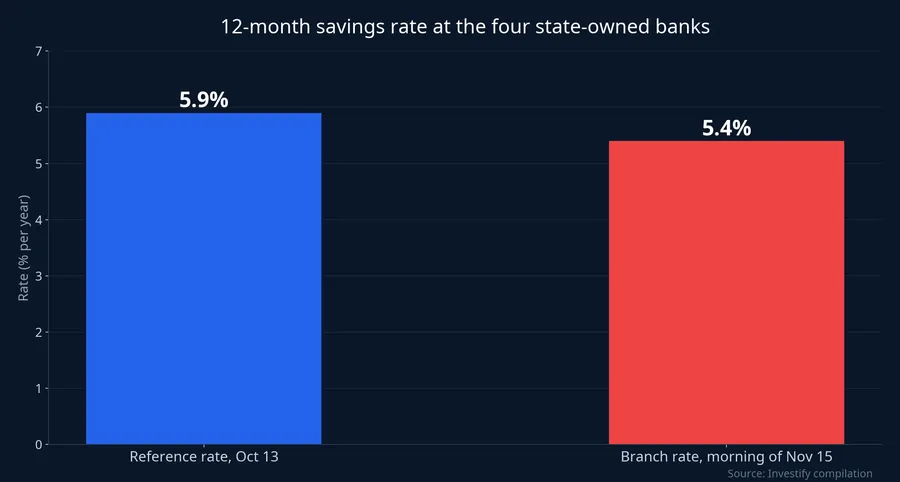
In plain terms, 9.5% is not a promotional rate reserved for year one. It comes out of the same formula that applies for all 7 years, built on a reference savings rate of 5.9% a year set on October 13, 2026.Thời báo Ngân hàng By the morning of November 15, the branch rate for 12-month deposits at all four state-owned banks was 5.4% a year.Lao Động The formula's starting point is therefore already 0.5 percentage points lower than when BVBank fixed the first-year rate.
How the rate is calculated
According to the offering notice published by Thời báo Ngân hàng on November 12, the bond pays a floating rate:Thời báo Ngân hàng
Interest rate = reference rate + 3.6% a year.
The reference rate is the average individual savings rate in Vietnamese dong, 12-month term, interest paid at maturity, as published on the websites of Vietcombank, VietinBank, BIDV and Agribank. Where a website lists several regions, the rate at the head-office location applies. The 3.6-point margin stays fixed for all 7 years.
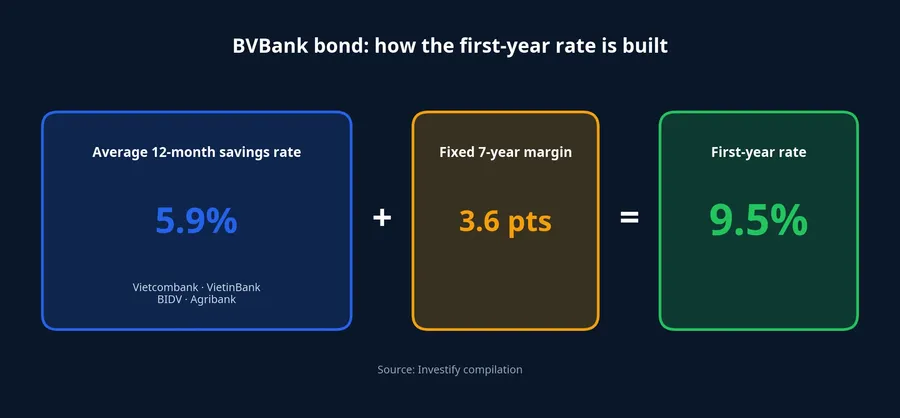
For the first interest period, BVBank used October 13, 2026 as the determination date, when the reference rate was 5.9% a year. Adding 3.6 points gives exactly 9.5%. From the second period on, the determination date is the seventh business day before the first day of each interest period, and BVBank posts the figure on its website within two business days. Each interest period lasts one year from the issue date, with interest paid in arrears once a year.
That means the year-two rate will be set around the end of 2027, when the bond is almost a year old. A buyer today locks in 9.5% for the first 12 months. For the six periods after that, the coupon moves up or down by exactly as many points as the 12-month savings rate at the four state-owned banks.
What it means for VND 10 million
An individual investor buys a minimum of 100 bonds, or VND 10 million of face value, in multiples of 100 bonds.Tin nhanh chứng khoán Institutions buy a minimum of 1,000 bonds, equal to VND 100 million.
On VND 10 million of face value, year one pays VND 950,000 in interest (Investify calculation from the 9.5% rate). Because the margin is fixed, every 0.5-point change in the reference rate moves one year's interest on VND 10 million by VND 50,000. Interest accrues on actual days over a 365-day year, so the real payment can differ by a few hundred dong.
Three paths for the later years
No one knows where state-bank savings rates will stand at the end of 2027. What can be worked out is that each path below has a clear condition and a concrete number.
Reference rate stays at 5.4%. This is the rate all four banks posted at their counters on the morning of November 15. If the average is still 5.4% on the second-period determination date, the year-two rate is 9.0% a year. On VND 10 million, that is VND 900,000 in interest, VND 50,000 less than in year one.
Reference rate keeps falling. Each further 0.5-point drop below 5.4% takes another VND 50,000 off a year's interest on VND 10 million. At a reference rate of 4.9%, the bond pays 8.5% a year, or VND 850,000.
Reference rate rises again. If the average returns to 5.9%, year two pays exactly what year one did, 9.5% a year. Every further 0.5 points above that adds VND 50,000 a year on VND 10 million.
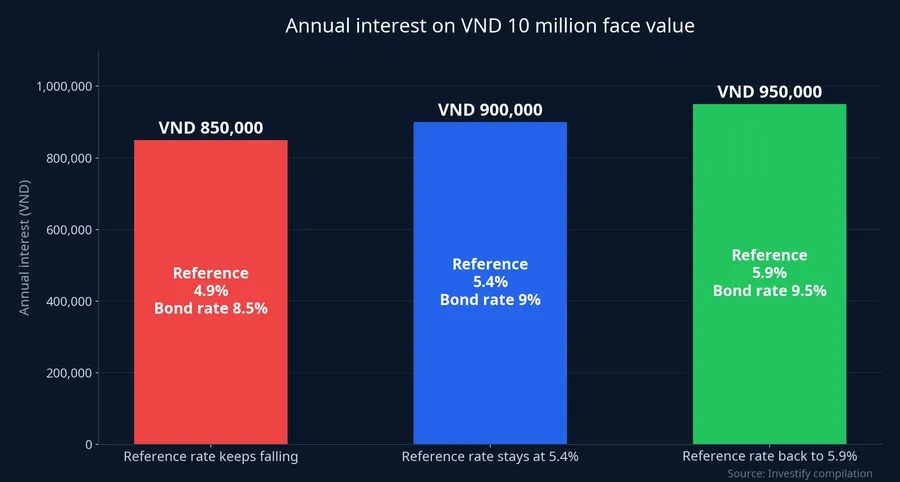
All three paths use the same yardstick: the average 12-month, paid-at-maturity rate of the four banks on the determination date BVBank announces. A buyer does not need to forecast rates to follow this investment. They only need to watch the 12-month deposit rate card of those four banks, which is public on their websites and changes infrequently.
Compared with a savings deposit, this bond differs in two ways. First, time: the money is tied up for 7 years and the rate is locked only for year one. Second, the nature of the debt: the offering notice describes it as non-convertible, without warrants, unsecured, subordinated debt that qualifies as BVBank's tier 2 capital.Thời báo Ngân hàng The bond code is issued by the Vietnam Securities Depository and Clearing Corporation (VSDC) after the offering is completed. The prospectus is posted on the websites of BVBank and ACB Securities, the advisor and bondholder representative. Buyers should read it for the payment ranking and the terms beyond interest.
For BVBank and BVB shareholders
According to the notice, the proceeds will be used to enlarge operating capital, raise tier 2 capital, keep the State Bank's prudential ratios in line with regulation, and add lending capital, especially for priority sectors.Tin nhanh chứng khoán A BVBank representative said the offering fits the bank's plan to diversify funding and widen room for credit growth, and that a successful issue would help balance its funding structure in fiscal 2026.FireAnt
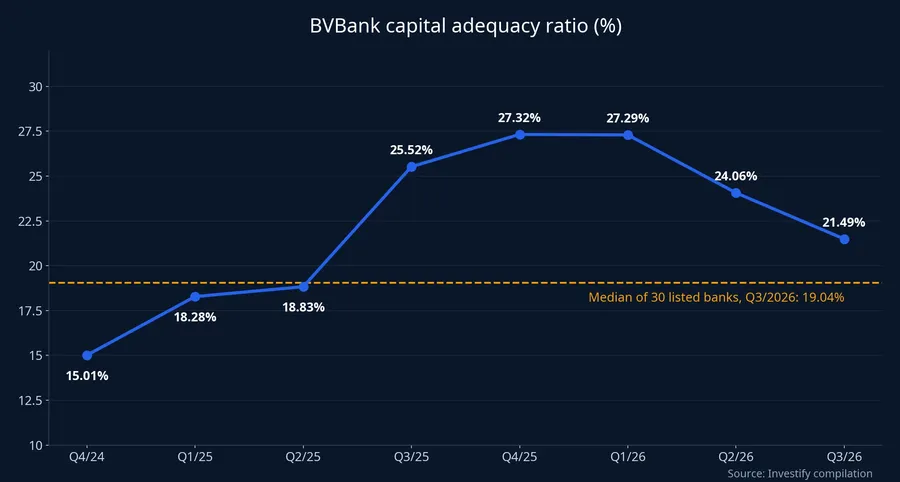
BVBank's capital adequacy ratio at September 30, 2026 was 21.49%, down from 24.06% at the end of Q2 and 27.29% at the end of Q1. It is still above the 19.04% median of the 30 listed banks with data for the same quarter. Tier 2 capital from the VND 1,300 billion bond would add to that cushion as loans keep growing.
The trade-off is interest cost. If the full VND 1,300 billion is sold, first-year interest comes to about VND 123.5 billion (Investify calculation). That is roughly 15% of pre-tax profit for the first nine months of the year, which was more than VND 825 billion. That nine-month profit rose 90% year on year and already equals 118% of the full-year plan. Total assets at the end of September exceeded VND 145,200 billion, up 9.2% from the start of the year, and outstanding loans exceeded VND 85,540 billion, up 9.3%.Tin nhanh chứng khoán
That cost floats in the same direction as the buyer's coupon. If the reference rate stays at 5.4%, year-two interest on VND 1,300 billion falls to about VND 117 billion (Investify calculation). When state-bank savings rates fall, BVBank's interest burden eases by exactly the amount bondholders lose.
Two dates to watch
The near one is December 9, the deadline for subscriptions and payment. The result will show how much of the planned VND 1,300 billion BVBank actually raises.
The far one is the determination date for the second interest period, the seventh business day before the bond's first anniversary. The figure BVBank publishes then will show whether 9.5% holds or whether bondholders enter year two on a different rate.
The takeaway is simple: this is a bond whose coupon floats with state-bank savings rates, and 9.5% is certain only for year one. In the meantime, the 12-month, paid-at-maturity rate card on the websites of Vietcombank, VietinBank, BIDV and Agribank is a direct gauge of the interest in the years ahead.