
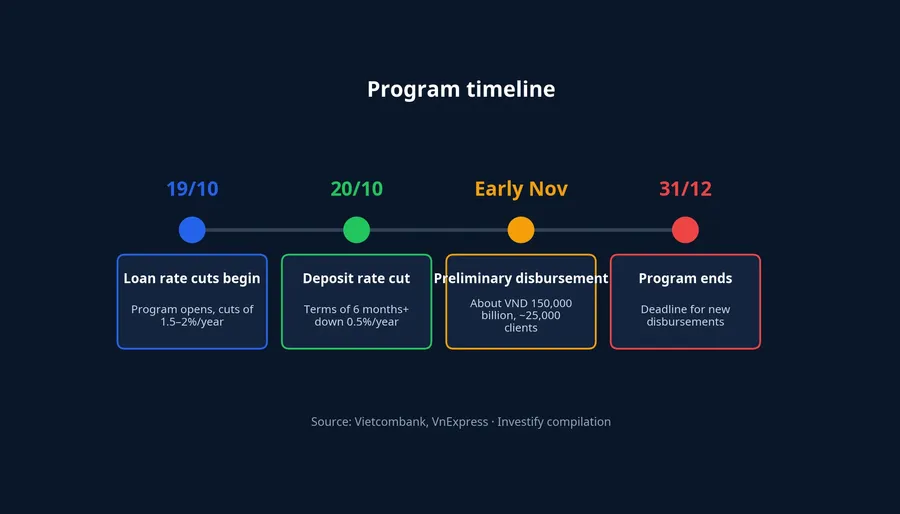
Less than a month after opening a loan-rate cut program for production and business, Vietcombank says it has disbursed about VND 150,000 billion to nearly 25,000 clients.VnExpress The loan-rate cut is 1.5–2% a year. On the other side of the balance sheet, listed savings rates for terms of 6 months and above have been 0.5% a year lower since 20 October.
The figures come from Bach Thanh Long, Deputy CEO of Joint Stock Commercial Bank for Foreign Trade of Vietnam (Vietcombank), in an interview published by VnExpress on the morning of 16 November. The bank had released preliminary numbers on the afternoon of 13 November.MarketTimes These are the bank's own preliminary statistics, covering the period to early November. The story has two sides, and both can be measured in money: how much interest borrowers save, and how much less savers receive.
Who the program covers, and how big the cut is
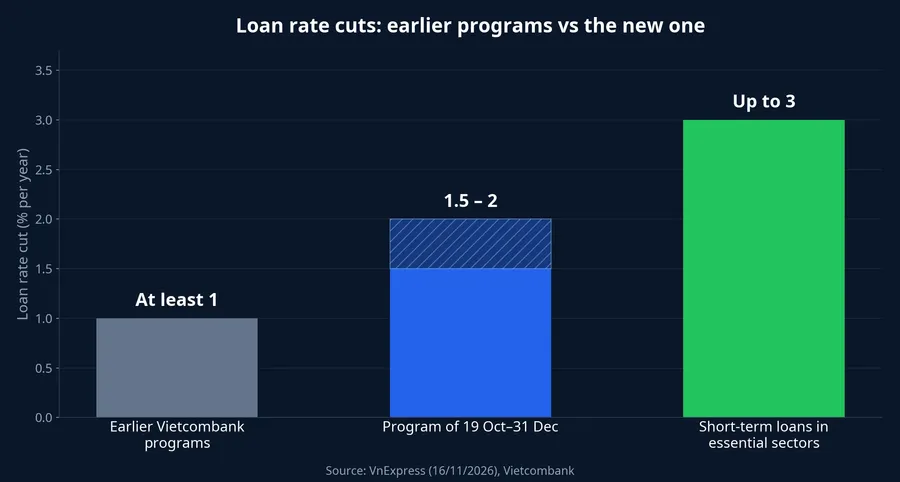
The full name is the "credit program to promote production and business and develop priority sectors." It runs from 19 October to 31 December 2026.Người Quan Sát Participants get 1.5–2% a year off Vietcombank's prevailing lending rate. Short-term loans in certain essential production and business sectors get up to 3% a year off.VnExpress
The cut is measured against Vietcombank's own prevailing rate. It is a deduction, not the final rate a borrower pays, which still depends on the loan's term, sector and the client's profile.
According to Mr. Long, the bank prioritizes short-term loans in essential sectors so that businesses can keep operating, keep goods moving and secure supply during the year-end peak, which in turn helps keep prices stable. Eligible borrowers include businesses, individuals and household businesses that need working capital for production and trade.
The program goes deeper than Vietcombank's earlier ones. Mr. Long said the credit program for growth-driver sectors and small and medium-sized enterprises had cut rates by at least 1% a year, and that lending rates under those preferential packages were then above 6% a year.VnExpress
VND 150,000 billion in under a month
Dividing about VND 150,000 billion by nearly 25,000 clients gives an average loan of about VND 6 billion each (a division of the two figures Mr. Long gave). It is only an average. The pool includes businesses, individuals and household businesses, so individual loans could be far larger or smaller.
To see how the cut touches costs, take that average VND 6 billion loan. A 1.5% cut saves about VND 90 million in interest if held for a full year; a 2% cut saves about VND 120 million. This is an illustration based on the announced cuts. Short-term loans usually mature within a few months, so what each client actually saves depends on how long the loan stays in the program.
The timing matters too. From 19 October to early November is only about two weeks, yet disbursement was already this large. The 31 December date is a clear deadline for businesses that need year-end capital: to qualify, a loan has to be disbursed before then.
Lending against cash flow
For small and medium-sized businesses, the interest rate is only half the story. Mr. Long said a lack of collateral, especially real estate, is one of the barriers these firms face in getting credit. That is why Vietcombank is gradually stepping up cash-flow-based lending.
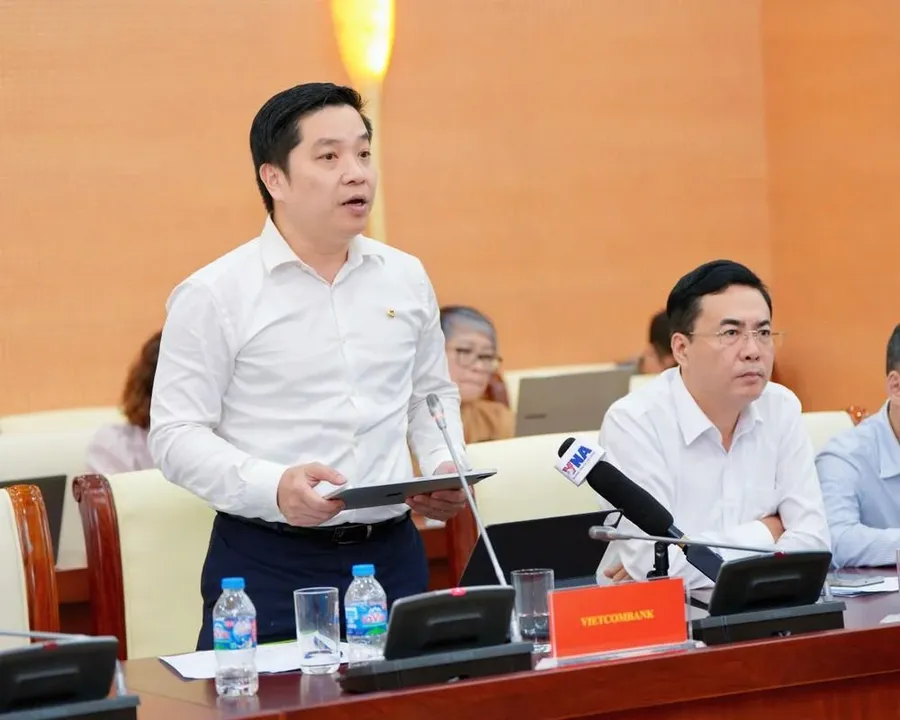
As Mr. Long described it to VnExpress, the method uses the business's own transaction data at the bank: payment history, revenue flowing through its accounts and other cash flows. The bank uses it to judge repayment capacity and extend credit that fits actual cash flow, relying less on collateral over time.VnExpress
For exporters, the bank may consider credit based on export contracts, orders or letters of credit, through pre-shipment financing, document discounting and factoring. For firms in production and supply chains, it draws on payment data among chain members, supply contracts and receivables.
One point needs careful reading. Cash-flow lending is a direction the bank is pushing. How far collateral requirements ease still depends on the financing structure and on each application's appraisal, as Mr. Long himself said. Businesses with a transaction history at Vietcombank have the clearest advantage under this approach.
The savers' side
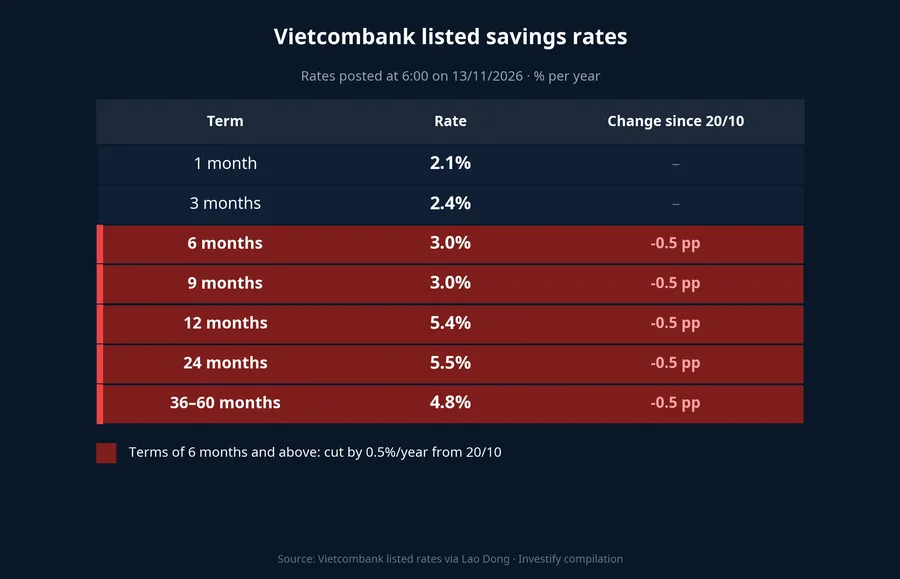
From 20 October, Vietcombank cut listed deposit rates by 0.5% a year for terms of 6 months and above. According to Mr. Long, this lowers funding costs and creates more room to cut lending rates, including on existing loans.VnExpress The bank also mentioned cutting operating costs, so deposit rates are one source of room, not the only one.
Per the rate table on Vietcombank's website at 6:00 on 13 November, as recorded by Lao Dong:Lao Dong
- 6 and 9 months: 3.0% a year.
- 12 months: 5.4% a year.
- 24 months, the highest in the table: 5.5% a year.
- 36, 48 and 60 months: 4.8% a year.
- Short terms not covered by the cut: 1 and 2 months at 2.1% a year, 3 months at 2.4% a year.
Online deposits carry the same rates as counter deposits for matching terms.
In money terms: a VND 100 million, 12-month deposit earns about VND 5.4 million in simple interest at maturity. A 0.5% cut is worth about VND 500,000 a year per VND 100 million (a calculation on the cut Mr. Long cited). The new table has applied since 20 October.
Cutting long-term deposit rates is not unique to Vietcombank. Per Vietnam+, banks are working both sides at once, lowering funding costs and raising operating efficiency, because if the cost of funds stays high, room to cut lending rates narrows.Vietnam+
What VCB shareholders should look at
When a bank gives up interest income for borrowers, the income earned per dong lent gets thinner. Lower deposit rates cut funding costs in return. The two forces pull in opposite directions. Shareholders will see their combined effect in the net interest margin (NIM) in the fourth-quarter financial statements, by which time the program will have run for more than two months. Until then, this article takes no side on which way NIM moves.
What to watch until 31 December
For people borrowing or planning to borrow for production and business, the program is clearly favorable: cuts of 1.5–2% a year, up to 3% in some sectors, and a 31 December deadline. The best-placed are businesses and household businesses whose cash flow already runs through Vietcombank accounts, since that is the data the bank uses for appraisal.
For savers the opposite is just as clear: from 6-month terms upward, every VND 100 million of new deposits earns about VND 500,000 less in interest per year. Both outcomes are measured by the same yardstick, interest in money terms, and both already have figures behind them.
The next marker is the disbursement figure Vietcombank updates when the program closes on 31 December, set against the roughly VND 150,000 billion recorded after the first two weeks. For shareholders, the answer on how falling loan rates and falling deposit rates net out sits in fourth-quarter NIM.