
From November 16, a new online savings deposit at Saigon Commercial Bank (SCB) earns no interest at all, whether the depositor picks a 31-day or a 36-month term. According to the new rate schedule reported the same day by Dan Tri and VnExpress, the online rate is 0% a year at every term and every payout option: interest paid upfront, monthly or at maturity.VnExpress
The 0% is only the visible part. The more useful question is the mechanism behind it. An ordinary bank cannot stop paying interest and still keep its depositors, so why can SCB, and why were exactly the 12- and 13-month terms left alone?
The new schedule: almost no term pays interest
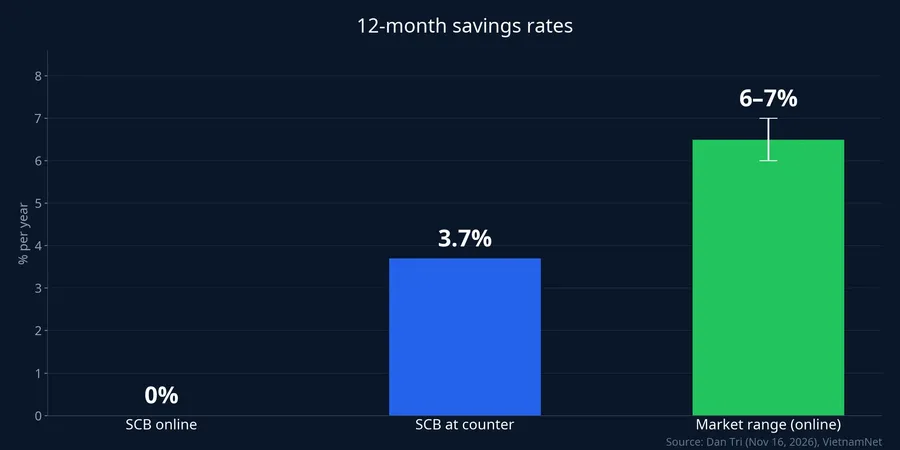
At the counter, the picture is nearly identical to online. A standard fixed-term savings product for new individual depositors is also 0% a year at every term from 1 to 36 months.Dan Tri Only two terms still pay, both with interest at maturity: 3.7% a year for 12 months and 8.7% a year for 13 months.VietnamNet
| Channel | 12 months | 13 months | All other terms |
|---|---|---|---|
| Online | 0% | 0% | 0% |
| At the counter (interest at maturity) | 3.7% a year | 8.7% a year | 0% |
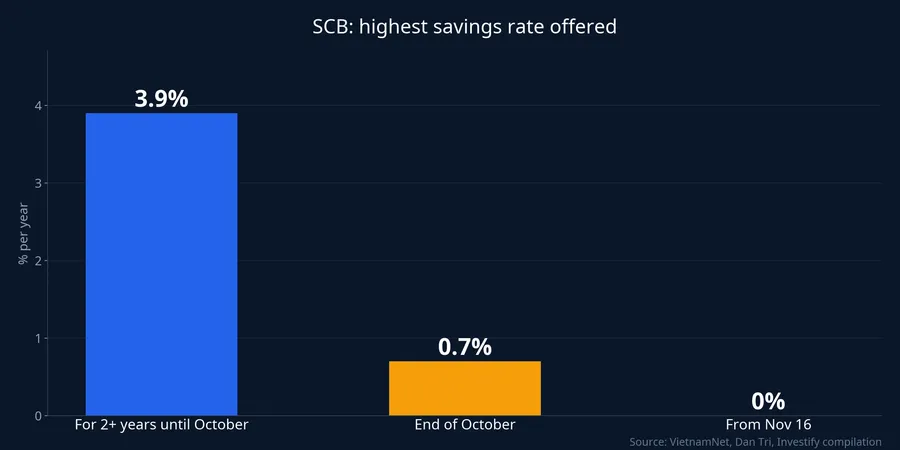
This is not the first cut. Before it, SCB's online savings rates were already down to roughly 0.1–0.7% a year depending on term and payout option, and VnExpress calls this the second cut within a month.VnExpress Per VietnamNet, SCB held its top deposit rate at 3.9% a year for more than two years, then lowered the top rate to 0.7% at the end of October. Less than a month later, the top online rate is 0%.VietnamNet
Existing account holders should note one more detail. VietnamNet reports that the upfront-interest column in the schedule carries a note saying it applies to existing accounts that roll over, and that this column is also at 0% a year.VietnamNet
It is a sharp reversal of SCB's old image. According to VnExpress, the bank used to pay about 1.5–2 percentage points more than the four state-owned banks (Agribank, BIDV, Vietcombank, VietinBank). Since the State Bank of Vietnam placed it under special control in 2022, SCB's rates have sat among the lowest in the market.VnExpress
Mechanism one: liquidity no longer depends on rates
Put simply, for an ordinary bank the deposit rate is the price of keeping depositors. Pay 0% and the money moves elsewhere, leaving the bank short of funds to lend and to repay maturing deposits.
SCB sits outside that equation because of its legal status. In VnExpress's analysis, based on the Law on Credit Institutions, a credit institution under special control is typically given liquidity support by the State Bank, can receive special loans and is exempt from deposit insurance premiums. With that support, the bank may not need to pay high rates to retain or attract depositors the way other banks do.VnExpress
Mechanism two: restricted lending means less need for funding
Banks raise deposits to lend them out. If lending is blocked, extra deposits simply sit idle and add cost.
VnExpress writes that a bank under special control must focus on resolving bad debt and earlier weaknesses. Lending is usually restricted, so the bank has little need for large funding, and raising more deposits at high rates would only add cost without improving performance.VnExpress
This explanation needs to be kept in its place: it is VnExpress's analysis based on the general rules for special control. A 0% rate is also not, by itself, evidence that the bank cannot repay depositors' principal.
Mechanism three: two terms tied to floating-rate loans
Why exactly 12 and 13 months? According to VnExpress, these two terms are usually the reference rates banks use to price floating-rate loans, so they are adjusted less often.VnExpress
SCB's 8.7% a year for 13 months is even higher than the online 18-month rate commonly offered in the market, at roughly 6.5–7.1% a year according to Dan Tri.Dan Tri A new deposit earns interest only if the depositor picks one of these two terms, at the counter, with interest paid at maturity.
The gap with the rest of the market
Per Dan Tri on November 16, online 6-month savings rates across the market range from 4.15% to 6.9% a year, while the 12-month rate is commonly 6–7% a year.Dan Tri So a 12-month online deposit at SCB earns 0%, while the same term at other banks commonly pays 6–7% a year. Even the 3.7% a year at the counter leaves SCB about 2.3–3.3 percentage points below the online market level.
Other changes for SCB customers
Interest rates are not the only change. SCB has cut the fast-transfer limit on its SCB Mobile Banking and Internet Banking apps to a maximum of VND 20 million a day. The bank says the move is meant to strengthen transaction security and protect customer accounts from fraud and asset theft.Dan Tri
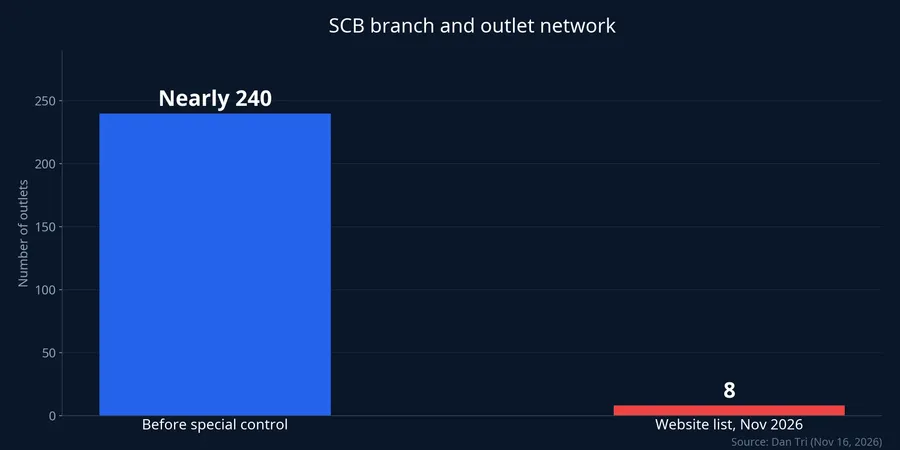
The network has also shrunk sharply. Before it came under special control, SCB had nearly 240 outlets, made up of 50 branches and 190 transaction offices, across 28 provinces and cities (before the mergers).Dan Tri According to Nguoi Quan Sat, the list updated to November 15 shows just 8: three in Ho Chi Minh City, one in Hanoi, and the rest in Da Nang, Gia Lai, Lam Dong and Vinh Long.Người Quan Sát VnExpress counts nearly 190 transaction offices closed in 2023–2025, and another 39 branches ceasing operations since mid-July.VnExpress
What depositors should take from the new schedule
The thesis is straightforward: SCB's 0% is not the result of a rate race. It follows from the bank's special position, where liquidity has its own support mechanism and lending is restricted. That explanation is VnExpress's analysis.
For anyone planning a new deposit at SCB, the window for earning interest has almost closed: every online deposit and every counter deposit under 12 months earns nothing. For borrowers on floating rates at SCB, the 3.7% and 8.7% figures are the most relevant detail in the new schedule, because by VnExpress's analysis these two terms are usually the reference rates for floating-rate loans.
The next signal to watch is the rate schedule for the 12- and 13-month terms in SCB's later announcements.