
On November 9, 2026, Becamex Group (HoSE: BCM), formally the Becamex Investment and Industrial Development Corporation, disclosed through the Hanoi Stock Exchange (HNX) that it had sold all 12,000 BCML12602 bonds, each with a face value of VND 100 million, raising VND 1,200 billion.CafeF The issue was distributed from October 21 to November 3, 2026, has a 36-month term and matures on October 21, 2029.MarketTimes
It is Becamex's second bond issue of 2026, and the second one used to repay bank loans. The first, BCML12601, finished selling in mid-September. Same issuer, same three-year term, same purpose, yet the terms differ on almost every point a bond buyer cares about. Side by side, they show how to read an offering document: look at the rate first, then at the state of the collateral.
Fixed rate: 12.5% versus 11%
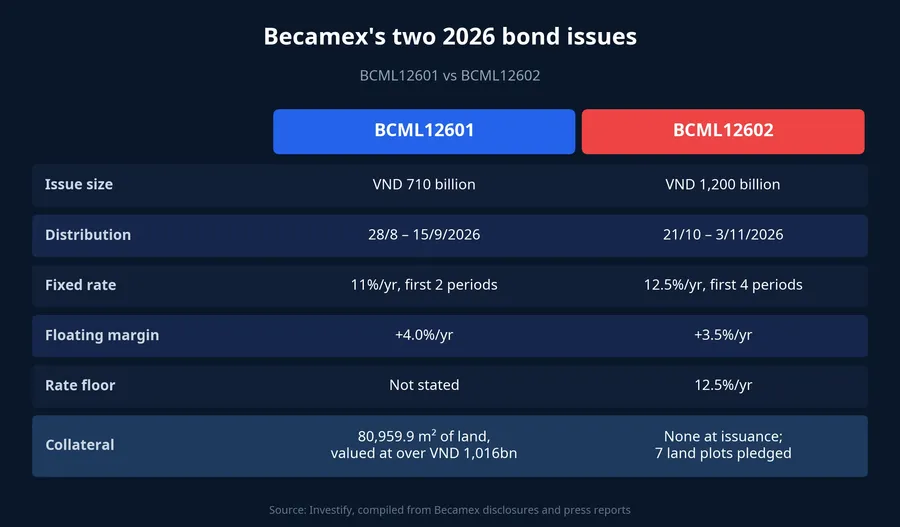
Under the issuance plan, the first four interest periods of BCML12602 carry a fixed rate of 12.5% a year.MarketTimes BCML12601, distributed from August 28 to September 15, 2026 and totaling VND 710 billion, fixed its rate at 11% a year for only the first two payment periods, with interest paid every six months.CafeF In other words, the fixed stretch on the older bond lasts one year.
The new bond keeps the rate fixed for four periods, twice as many, and starts 1.5 percentage points higher.
Floating rate: a smaller margin, but with a floor
After the first four periods, the BCML12602 rate floats. It then equals the lending rate for large corporate customers on terms of over 12 up to 60 months, as published by Military Commercial Joint Stock Bank (MB), plus a margin of 3.5% a year.MarketTimes The older bond adds a 4.0% margin to a reference rate.CafeF
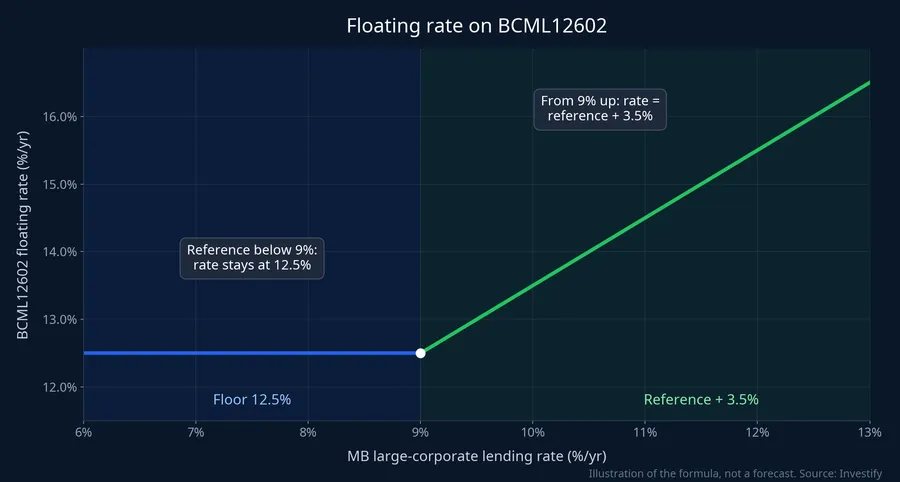
On margin alone, the new bond is 0.5 percentage points lower. The more important term is the floor: the actual rate on BCML12602 is never below 12.5% a year for the whole term.MarketTimes Finance and Life magazine (FiLi) also reported this term in its piece on the issuance plan, published October 21, 2026.FiLi
The arithmetic is simple: 12.5% minus the 3.5% margin is 9%. While MB's large-corporate lending rate is below 9%, the bondholder still receives 12.5%. Only when the reference rate rises above 9% does the bond pay more than 12.5%. So the smaller margin does not leave buyers of the new bond with less than the starting rate. It only makes any extra interest, if it arrives, slightly smaller than under the older bond's formula.
For Becamex, the floor means a clearly defined minimum interest cost. On VND 1,200 billion of principal, 12.5% a year works out to at least about VND 150 billion in interest per year for this issue. The VND 710 billion bond at 11% in its first year comes to about VND 78 billion.
Collateral: appraised land versus a pledge
This is the biggest difference between the two issues.
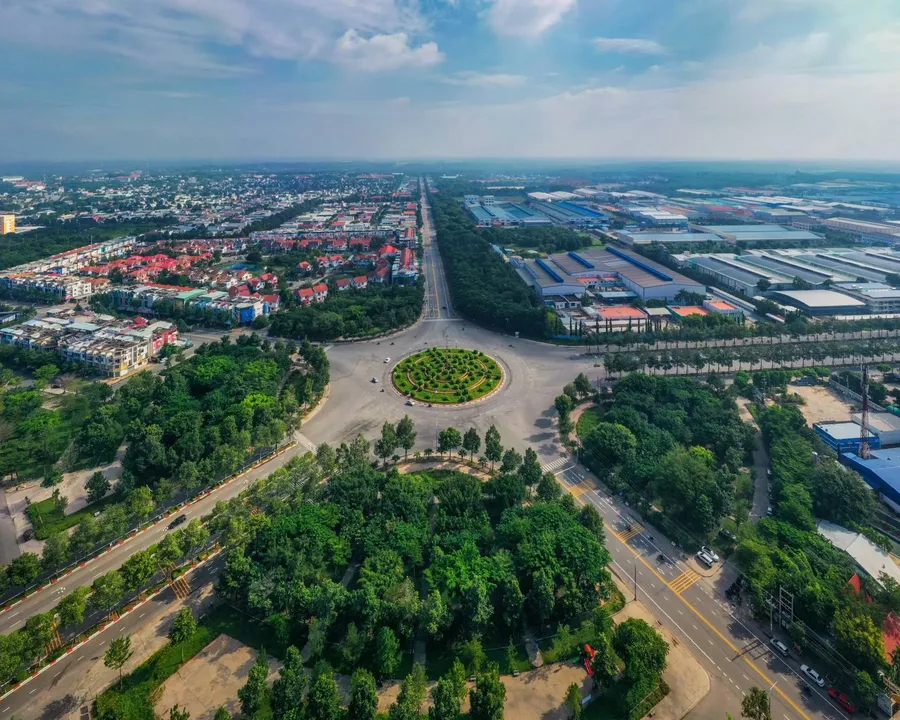
BCML12601 had collateral from the issuance plan onward: urban residential land use rights owned by Becamex, totaling 80,959.9 m² and appraised at more than VND 1,016 billion.CafeF That appraisal is higher than the VND 710 billion raised.
The press describes BCML12602 as bonds that are "non-convertible, carry no warrants and have no collateral".MarketTimes Tin Nhanh Chứng Khoán calls them "three-no" bonds.Tin Nhanh Chứng Khoán
Becamex has offered an explanation alongside. According to FiLi on October 21, BCM said that at issuance the bonds had not yet completed the collateral mortgage procedures, and that the company committed to mortgage seven land use rights totaling more than 12 hectares in Binh Duong ward, Ho Chi Minh City, along with assets attached to the land, to secure the issue.FiLi
So "no collateral" is accurate for the state at issuance, but it is not the whole story. The pledged land area is larger than for the older bond. The value of the seven plots can only be compared with the older bond's VND 1,016 billion once Becamex discloses the mortgage file with its appraisal.
The distinction matters to a bondholder for one reason. If a company defaults, a creditor holding a registered mortgage is first in line to recover from that asset. An unsecured creditor ranks behind, alongside other ordinary payables. A pledge to mortgage only changes the bondholder's position once the mortgage procedure is complete.
Use of proceeds: bank debt again
The older bond was specific: VND 110 billion to repay principal on a short-term loan at BIDV's Binh Duong branch, and VND 600 billion for a short-term loan at another bank's Dong Nai branch.CafeF The new issue puts the entire VND 1,200 billion toward principal on four loan contracts, to be disbursed in Q4 2026.Tin Nhanh Chứng Khoán MB Securities (MBS) is the organization involved in the issue.MarketTimes
Across both issues, Becamex has raised VND 1,910 billion through bonds in 2026.MarketTimes Because the purpose is to swap bank debt for bond debt, neither issue reduces total borrowings. They change the creditor and the terms. At the end of September, Becamex's financial debt on its consolidated statements was VND 26,259 billion.MarketTimes The 12.5% is therefore only the cost of the new debt. Whether the swap raises or lowers overall funding cost depends on the rates on the four bank loans being repaid.
Also in Q4: more capital for an expressway
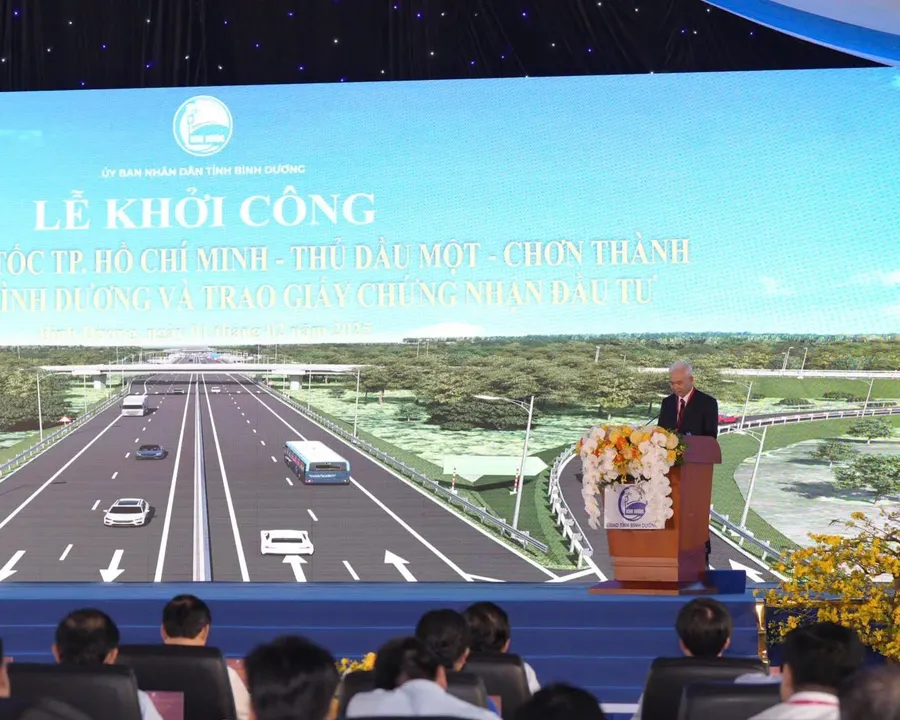
While the VND 1,200 billion is disbursed, Becamex's board has approved contributing nearly VND 375.5 billion more to Ho Chi Minh City – Thu Dau Mot – Chon Thanh Expressway JSC, due within Q4 2026.Báo Pháp luật
The project company plans to raise its charter capital from VND 100 billion to more than VND 866.2 billion. If Becamex pays in full, its stake rises from VND 49 billion to nearly VND 424.5 billion, keeping its ownership at 49%.CafeF The section through the former Binh Duong province runs about 52 km under a public-private partnership, with total investment of about VND 17,400 billion and completion expected in 2027.CafeF
This contribution is cash going out in the same quarter that interest on the new bonds starts to accrue. On the exchange, BCM closed at VND 38,350 on November 10, up 1.99%.
Who gets what, who accepts what
Holders of BCML12602 receive a higher rate than on the older bond from day one, a longer fixed stretch and a 12.5% floor for the whole term. The lower floating margin only affects interest above the floor. On the other hand, at issuance they are creditors without mortgaged collateral.
Holders of BCML12601 receive a lower rate, fixed for only one year, but have land appraised at more than VND 1,016 billion standing behind VND 710 billion of principal.
BCM shareholders see the new issue's minimum interest cost locked at 12.5% a year for three years, even if market rates fall. In the same quarter, the company also has a contribution of nearly VND 375.5 billion to the expressway.
Investors being pitched high-yield corporate bonds can use this pair as a real example: at the same company, the unsecured issue pays more than the secured one. Under current rules, privately placed bonds are open only to professional investors. Even so, the question to ask of any offering stays the same: is the collateral registered as mortgaged, and how is it valued against the principal?
Signals to watch
The clearest marker is a Becamex disclosure on HNX that the mortgage of the seven land use rights for BCML12602 is complete, together with the appraised value. Once that appears, holders of the new bond move from unsecured to secured creditors while keeping a higher rate than on the older bond. If the procedure drags on, they continue to rank behind creditors with mortgaged assets.
The second marker is the Q4 2026 financial statement, due within 30 days after quarter-end. Interest expense and the mix of bank versus bond debt in that report will show how the swap changes Becamex's funding cost.
Over a longer horizon, the number to remember for the new bond is 9%: while MB's large-corporate lending rate stays below it, bondholders still receive 12.5%; above it, the bond rate rises with it.