
On 3 November 2026, the first tranche of Vietnam Joint Stock Commercial Bank for Industry and Trade (VietinBank, ticker CTG) closed its new public bond offering. All 120 million CTG2632T2/01 bonds were distributed,Mekong ASEAN and the bank raised VND 12,000 billion from 1,773 domestic investors.Người Quan Sát Split evenly, each investor put in about VND 6.8 billion. That is a group average covering both individuals and institutions.
The bank's earnings backdrop is solid. Consolidated pre-tax profit for the first nine months came to VND 39,557 billion, up 34% year on year; the third quarter alone was close to VND 13,689 billion, up 29%.Mekong ASEAN So the VND 12,000 billion should not be read as a bank scrambling for cash. What deserves a closer look is what nearly 1,800 investors actually bought over the counter: not a savings account, but a loan to the bank itself for six years, which VietinBank counts toward its own capital.
What kind of debt this is
According to the offering result report, as relayed by Markettimes on 6 November, the bonds have a face value of VND 100,000, a six-year term and pay interest every six months. They are non-convertible, carry no warrants, have no collateral, and meet the conditions to count as VietinBank's Tier 2 capital under the law.Markettimes The coupon is a reference rate plus a 2.25%/year margin.Mekong ASEAN
The tranche 1 offering notice, published by Mekong ASEAN on 13 October, set a minimum purchase of 100 bonds, or VND 10 million at face value, with registration and payment running from 15 October to 3 November.Mekong ASEAN The same notice defines the reference rate for each interest period as the average 12-month personal savings rate at BIDV, VietinBank, Agribank and Vietcombank.Vietstock
A coupon that floats with savings rates
Put simply, the coupon has two parts. The first is the reference rate, reset every six months to the prevailing 12-month savings rate at those four large banks. The second is the 2.25%/year margin, which stays fixed for the whole term. If savings rates fall, the next coupon falls with them, and the reverse is also true.
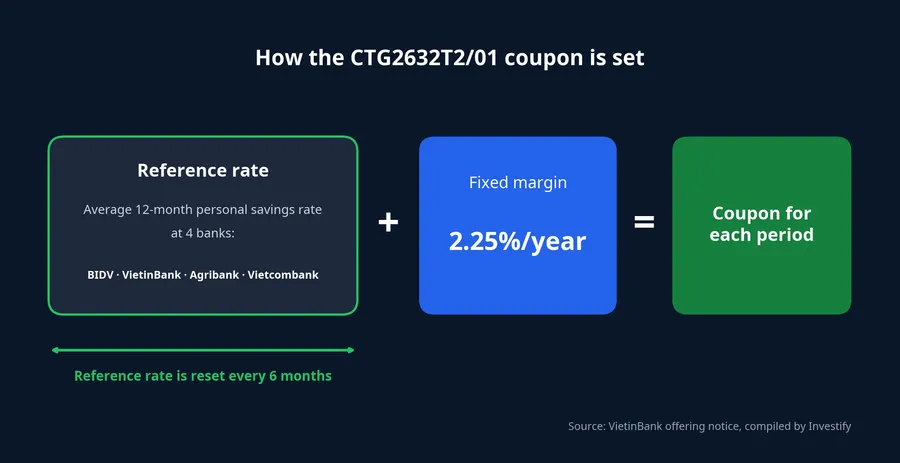
This bears directly on a bondholder's wallet. The gap to the four-bank average 12-month savings rate is always 2.25%/year, while the absolute coupon is not locked in for the full six years.
Money that stays put for six years
A savings account can be withdrawn early at the cost of lost interest. A six-year bond is different: it is money the bank has borrowed and will repay at maturity, so buyers should treat it as cash that sits still for six years. The 2.25%/year margin is what holders are paid for locking money up for that long, accepting debt with no collateral, and holding a loan the bank uses as capital.
Why a bank needs Tier 2 capital
A bank's own funds consist of Tier 1 capital (charter capital, retained earnings and reserves) and Tier 2 capital, which includes qualifying long-term debt. Circular 14/2025/TT-NHNN, effective from 15 September 2025, requires commercial banks to keep a Tier 1 ratio of at least 6% and a capital adequacy ratio of at least 8% against risk-weighted assets.Báo Chính phủ Tier 2 capital counts toward that 8% ratio.
The mechanism is straightforward. Every additional dong lent raises risk-weighted assets, so the bank needs more capital to keep its ratio from sliding. Raising Tier 1 means retaining profit or issuing new shares. Issuing bonds that qualify as Tier 2 is another route, and it does not dilute shareholders.
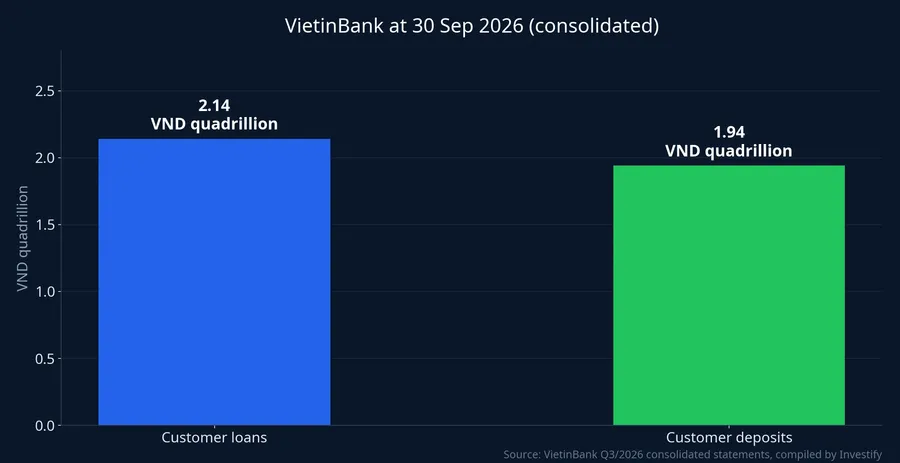
On scale, per the consolidated third-quarter financial statements, VietinBank had customer loans of VND 2.14 quadrillion and customer deposits of VND 1.94 quadrillion at 30 September 2026.Tin nhanh chứng khoán Total assets exceeded VND 2.95 quadrillion.Mekong ASEAN
Two brokerages raised capital in their updates on VietinBank's third-quarter results. SHS, in its banking-sector report of 2 November, flagged the capital adequacy ratio and the bank's capital top-up plans as items to watch.SHS MASVN, in its 3 November report, listed limited room for credit growth as a risk, since the loan-to-funding ratio is close to its ceiling.MASVN Those are the brokerages' views. VietinBank's own stated reasons, per Mekong ASEAN on 7 November, are to expand operating capital, add Tier 2 capital, meet the State Bank's safety ratios and lend to the economy.Mekong ASEAN
Where the money is meant to go
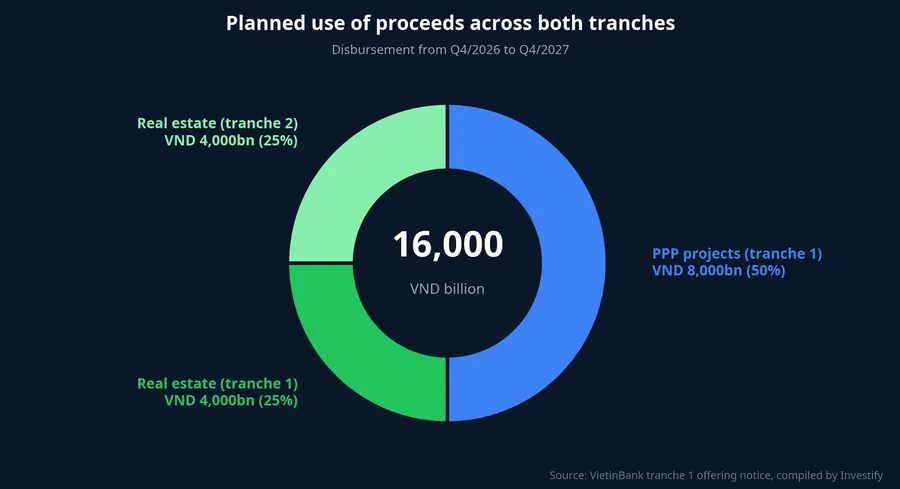
According to the offering notice published on 13 October, tranche 1 earmarks VND 4,000 billion for real estate lending and VND 8,000 billion for public-private partnership (PPP) projects. Tranche 2 is set aside entirely for real estate, at VND 4,000 billion. Disbursement is planned from Q4/2026 to Q4/2027, and the actual amount per sector depends on how many bonds are sold and on lending progress.Mekong ASEAN
Both are long-dated lending. Six-year funding fits project loans better than 6- or 12-month deposits, which must roll over constantly. Against a loan book of VND 2.14 quadrillion, VND 12,000 billion is only about 0.56%. The main effect of this bond for the bank is therefore added capital to keep its safety ratios, while the extra lending capacity is small.
The same notice says VietinBank is halting tranches 2 and 3 of its 2025 public bond plan (Certificate No. 420/GCN-UBCK of 12 November 2025) and moving to the new plan. A public bond offering is therefore not a first for this bank.
What tranche 1 buyers receive, and when
Per Markettimes, within 30 days of the offering closing on 3 November 2026, VietinBank delivers the bond ownership certificate to investors at the branch or transaction office where they registered and paid.Markettimes That means buyers will hold their certificates by early December at the latest.
Interest is paid every six months, each period at that period's reference rate plus 2.25%/year. How the reference rate is determined and the exact payment schedule are set out in the offering prospectus. The prospectus and the certificate are the two documents that define a holder's rights over the six years, so they are worth keeping safe.
For shareholders, the offering does not change the number of shares outstanding because the bonds are non-convertible. CTG shares closed on 6 November at VND 31,850.
Tranche 2: VND 4,000 billion remaining
Certificate No. 471/GCN-UBCK, issued on 6 October 2026, allows VietinBank to offer a total of 160 million bonds in two tranches. Tranche 2 is expected to be 40 million CTG2632T2/02 bonds, worth VND 4,000 billion, lifting the total to VND 16,000 billion if fully sold.Người Quan Sát According to Vietstock, each tranche runs no longer than 90 days and the two are no more than 12 months apart.Vietstock
The sell-out of tranche 1 shows there is demand for bonds sold over a bank counter at a 2.25%/year margin. For a saver who may be pitched tranche 2 at a branch, the framework to keep in mind is this: the bond pays the four-bank average 12-month savings rate plus a margin, and in return the money sits for six years in uncollateralised debt that counts as capital for the bank. A savings account and this bond differ in term, in how interest is set, and in where the holder stands in the bank's capital structure, so they should not be read as two names for the same product.
The next milestones to watch: the tranche 2 offering notice, which will give the registration window; the prospectus, which sets out how the reference rate is calculated and every condition attached to this debt; and the ownership certificate that tranche 1 buyers will receive within 30 days.