
In the first nine months of 2026, Vietnam International Bank (VIB) reported consolidated pre-tax profit of VND 7,591.5 billion, up 7.7% from VND 7,046.3 billion a year earlier.Kinh tế Môi trường In Q3 alone, pre-tax profit was VND 2,405.8 billion, up 18.5% year on year. Against a full-year plan of VND 11,550 billion, VIB has delivered about 66% after nine months.Doanh Nhân VN
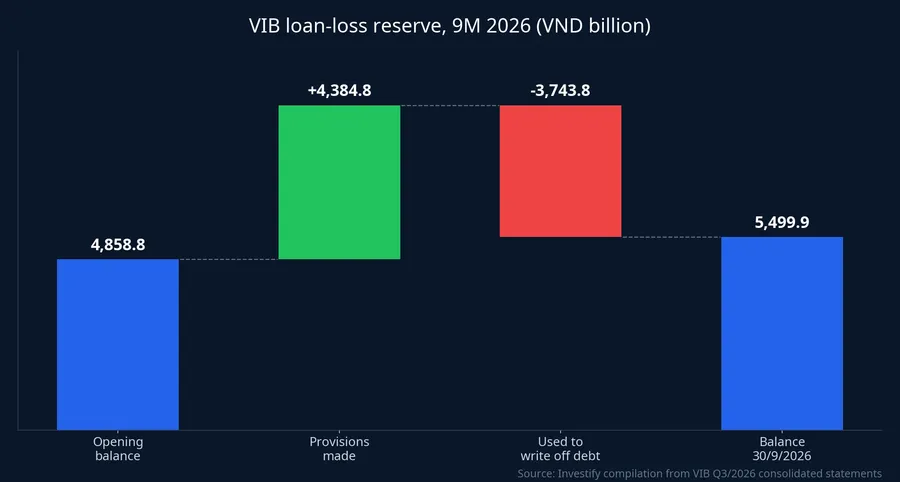
Beneath that profit figure sits a detail worth reading closely. The bank booked VND 4,384.8 billion in credit-loss provisions, nearly double the VND 2,215 billion of the same period in 2025.Mekong ASEAN Over the same months, VIB used VND 3,743.8 billion of provisions to handle risky loans. Subtract what was used from what was booked, and the customer-loan reserve grew by only about VND 641 billion. Put plainly, this is a bank earning clearly more money, with most of the increase set aside for provisions.
Where the extra income came from
Total operating income for nine months reached more than VND 17,329 billion, up 17.7%.Doanh nhân trẻ The fastest-growing line was services: net service income hit VND 4,054.7 billion, 3.19 times the prior-year period.Điện tử & Ứng dụng According to the notes the magazine cited, payment-service revenue was VND 3,948.2 billion, up 93.3% and more than 71% of total service revenue, while payment-service costs barely moved. In Q3 alone, net service income was VND 990.3 billion, double a year earlier.Kinh tế Môi trường
On costs, nine-month operating expenses fell 2% to VND 5,352.8 billion, and the cost-to-income ratio dropped from 37.1% to 30.9%. Interest expense rose 45.9%. Kinh tế Môi trường linked this to a decline in demand deposits and heavier funding through debt securities.
One line moved the other way: foreign-exchange trading. It lost nearly VND 1,147 billion over nine months, against a gain of nearly VND 124 billion a year earlier, with almost VND 368 billion of that lost in Q3.Doanh nhân trẻ Điện tử & Ứng dụng attributed the loss mainly to currency-derivative costs of VND 2,898.2 billion.
Adding it up, pre-provision profit came to nearly VND 11,976 billion, up 29.4%.Doanh nhân trẻ On that line alone, VIB is having a very good year.
Most of the increase went into provisions
Pre-provision profit grew by about VND 2,700 billion year on year, while provision expense grew by about VND 2,170 billion (from VND 2,215 billion to VND 4,384.8 billion). What was left to reach pre-tax profit was about VND 545 billion, exactly the gap between VND 7,591.5 billion this year and VND 7,046.3 billion last year. In other words, of every VND 5 of added operating profit, roughly VND 4 went to provisions. Nine-month profit did not rise because VIB provisioned less. It provisioned far more, and profit still grew because operating income grew faster.
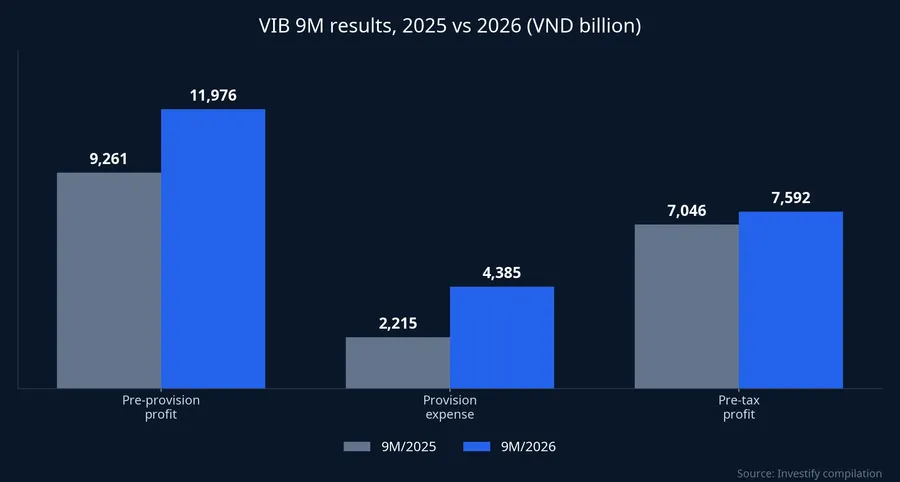
Q3 shows the same mechanism. Provision expense for the quarter was VND 1,899 billion, up 64% year on year, and absorbed 44% of pre-provision profit. Pre-provision profit for the quarter rose 35%, so even after provisions, profit still grew 18.5%.Điện tử & Ứng dụng
On the quality of Q3 income, Viet Dragon Securities (VDSC) recorded VND 700 billion in recoveries of written-off bad debt, up 61% and more than half of the quarter's non-interest income. VDSC treats this as a one-off source.Doanh Nhân VN Over nine months, recoveries on written-off debt brought in VND 1,491 billion, up 16.5%.Kinh tế Môi trường So Q3 profit had three supports: service fees, an improved margin (VDSC puts Q3 net interest margin at 3.3%, up 0.2 percentage points from Q2), and cash recovered from old debt. The third is harder to repeat consistently than the first two.
Large provisions, a reserve that grew little
The customer-loan reserve at end-September stood at VND 5,499.9 billion, up 13.2% from the start of the year. Meanwhile, bad debt (groups 3 to 5) rose to VND 13,167.1 billion, up 16.2% from VND 11,334.7 billion at the start of the year.Kinh tế Môi trường Bad debt grew slightly faster than the reserve, so the NPL coverage ratio slipped from 42.9% to about 41.8%. Simply put, for every VND 100 of bad debt, VIB holds about VND 42 of provisions behind it.
The mix of bad debt changed as well. Group 5 debt (likely to be lost) fell 11.2% to VND 5,650.3 billion, consistent with the bank having cleared old loans. By contrast, group 3 debt (substandard) rose 85.7% to VND 3,991.1 billion and group 4 rose 24.8%. Newly souring loans are arriving faster than old ones are being cleared.
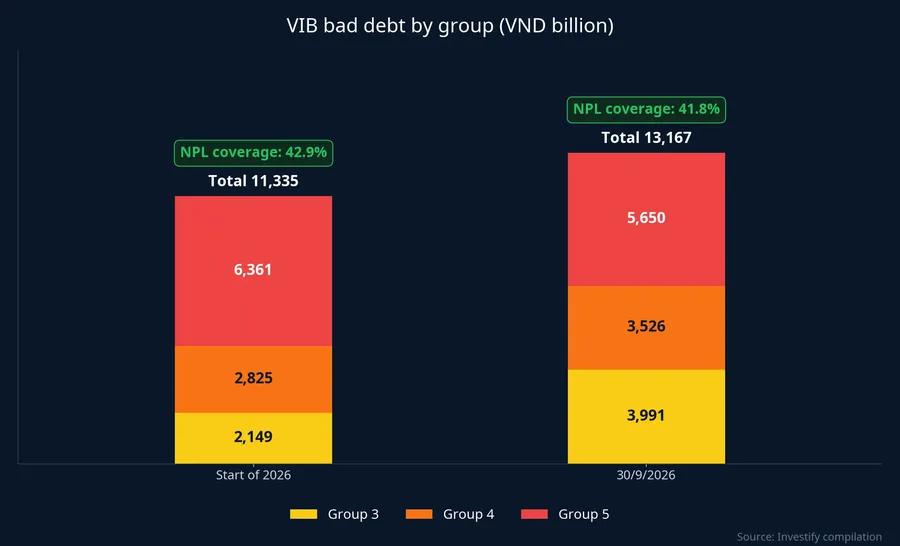
According to VDSC, net new bad debt in Q3 was about VND 3,000 billion, the highest quarterly level since Q1 2023, and 42% coverage puts VIB among banks with a thin provision buffer in the system.Doanh Nhân VN
The NPL ratio VIB reports is 2.29%, versus 2.16% at the end of 2025.Doanh nhân trẻ Behind that figure, special-mention debt (group 2) reached VND 11,466.4 billion, up 25.4%.Kinh tế Môi trường Group 2 covers loans that are overdue but not yet classed as bad debt, so it is an early indicator of provisioning pressure in coming quarters.
Capital and liquidity remain within limits
A reserve that has not thickened does not mean the bank is short on capital or liquidity. According to VIB, its Basel III capital adequacy ratio is above 11%, against an 8% minimum. The loan-to-deposit ratio (LDR) is 77%, below the 85% ceiling, and ROE is 16.2%.CafeF
Total assets at end-September reached VND 599,583.8 billion, up 7.8% from the start of the year. Customer loans were VND 411,311.7 billion, up 7.7%.Kinh tế Môi trường On the exchange, VIB shares closed at VND 14,250 on November 4, up 2.52% in a rising market session.
Two lines to watch in the Q4 report
The nine-month numbers show VIB earning clearly more before provisions, thanks to payment fees, an improved margin and lower operating costs. At the same time, newly souring loans are arriving fast enough that most of the extra provisions are used immediately to handle debt, so the buffer does not thicken in proportion. Both things are true. The thesis of this piece is that nine-month profit is real, but the quality of the buffer will decide whether profit keeps its momentum in the coming quarters.
To meet the full-year plan, Q4 needs about VND 3,958 billion of pre-tax profit, above the VND 2,405.8 billion of Q3. The Q4 report, usually published at the end of January, will answer through two lines. The first is group 2 and group 3 debt: if these stop rising, provision expense has grounds to level off and more pre-provision profit will flow through to earnings. The second is NPL coverage: holding at or edging above roughly 42% would mean the reserve has caught up with bad debt. If it keeps falling, profit in the coming quarters will still go largely to provisions, however fast service fees grow.