
In Q3 2026, Vinh Hoan Corporation (HoSE: VHC) booked net revenue of VND 3,316.69 billion, down 4.4% year on year. Profit after tax attributable to parent-company shareholders fell 50.8% to VND 213.12 billion.Tin nhanh chứng khoán Consolidated profit after tax, which includes minority interests, was VND 229 billion against VND 455 billion in Q3 2025.FireAnt
For balance, the quarter needs to sit next to the year-to-date figures. After nine months, net revenue stands at VND 9,665.34 billion, up 3.8%. Profit after tax attributable to parent-company shareholders is VND 954.46 billion, down 16.3% and equal to 59.7% of the VND 1,600 billion full-year plan. Revenue has reached about 69% of its VND 14,000 billion target.Tin nhanh chứng khoán The nine-month decline is milder than the Q3 drop, partly because Q2 2026 carried a high gross margin.
The open question is why revenue fell by a few percent while Q3 profit fell by half. On the numbers, most of the answer sits in the financial line rather than in fish sales alone.
Where about VND 270 billion of operating profit went
Net operating profit in Q3 was VND 260 billion, down 51%, a gap of about VND 270 billion from a year earlier.FireAnt Four lines of the income statement explain almost all of it:
- Gross profit fell 17.9%, or VND 104.43 billion, to VND 479.43 billion. Gross margin slipped from 16.8% to 14.5%.
- Financial income fell 70.7%, or VND 82.14 billion, to VND 34.02 billion.
- Financial expenses rose 266.4%, up VND 58.72 billion to VND 80.76 billion.
- Selling and administrative expenses rose 18%, up VND 26.27 billion to VND 172.55 billion.Tin nhanh chứng khoán
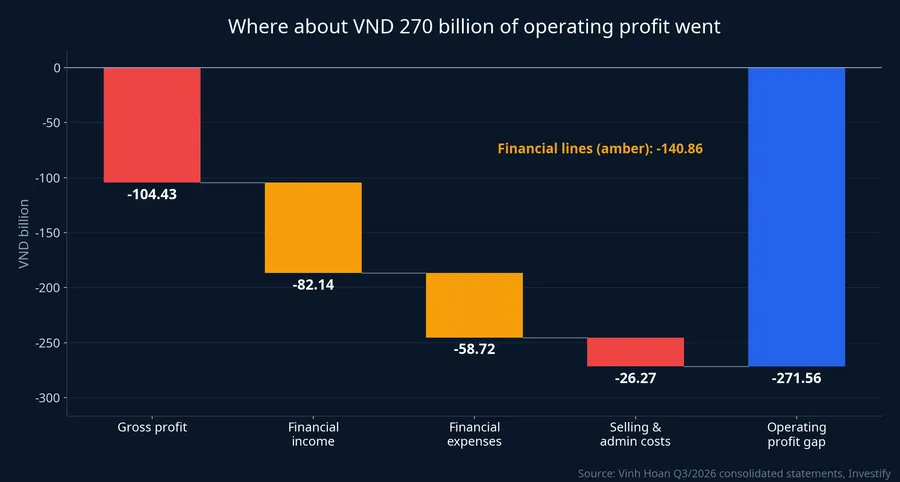
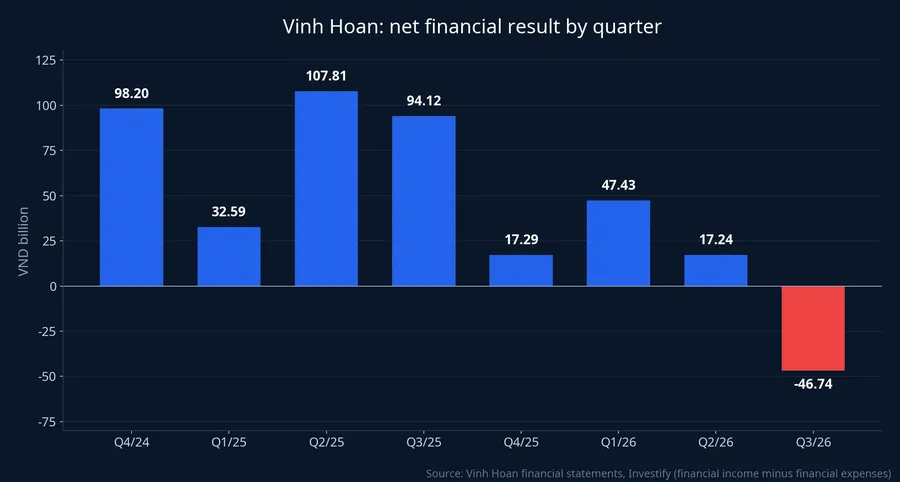
Netting financial income against financial expenses, the financial line swung from a net gain of VND 94.12 billion in Q3 2025 to a net loss of VND 46.74 billion in Q3 2026. That swing of about VND 141 billion is larger than the VND 104 billion fall in gross profit and accounts for more than half of the operating profit gap. Other profit came to VND 9 billion against VND 1 billion a year earlier, too small to offset it. Pre-tax profit therefore dropped from VND 534.71 billion to VND 269.17 billion.
The lower gross margin means every VND 100 of sales kept about VND 2.3 less in gross profit. That is the core business at work. The larger part of the gap sits in the financial line.
The financial line turns from plus to minus
Of the VND 80.76 billion in Q3 financial expenses, interest expense was VND 36.78 billion, against VND 10.94 billion a year earlier. It has climbed through the year: VND 15.63 billion in Q1, VND 29.38 billion in Q2, then VND 36.78 billion in Q3.
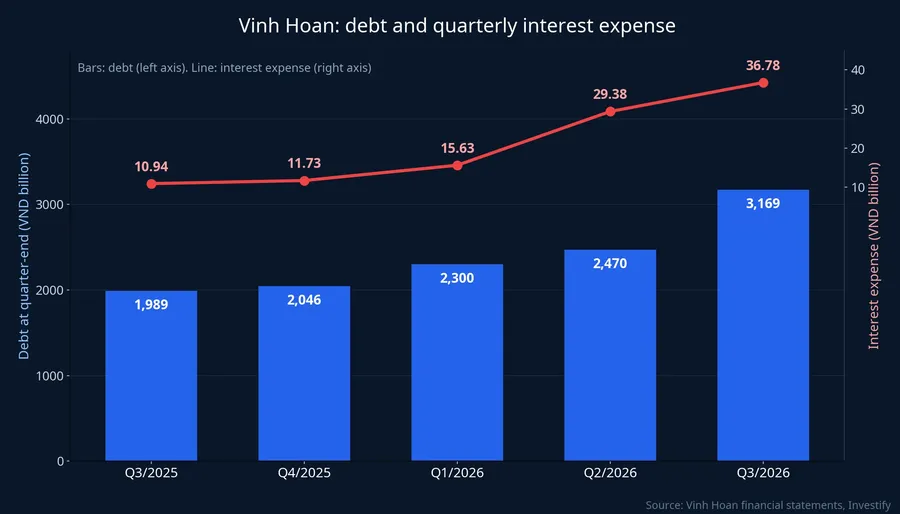
Interest expense follows debt. At September 30, 2026, Vinh Hoan's total borrowings were VND 3,169.2 billion, up 54.9% from the start of the year, or roughly VND 1,123 billion more. Most of it is short-term: VND 2,863.4 billion short-term and VND 305.8 billion long-term.Báo Pháp luật At the end of Q3 2025, debt stood at VND 1,989.32 billion, so debt rose about 59% in a year while interest expense more than tripled. Part of that is a larger loan balance, part is a higher average cost per dong borrowed.
Still, interest rose only about VND 26 billion, a small slice of the VND 141 billion swing in the financial line. The bigger part comes from financial income falling VND 82 billion, plus other financial expenses besides interest. Over the same period, short-term financial investments, mainly term deposits, fell from VND 2,401 billion at the start of the year to VND 1,900 billion, so less cash was earning interest.FireAnt
The comparison base matters too. Vinh Hoan's financial line has always swung between quarters: net VND 107.81 billion in Q2 2025 and VND 94.12 billion in Q3 2025, but only VND 17.29 billion in Q4 2025 and VND 17.24 billion in Q2 2026. Q3 2025 was a high bar. Even so, Q3 2026 is the first negative reading in the eight quarters since Q4 2024.
Cash flowing into long-term assets
The Q3 balance sheet shows Vinh Hoan borrowing more and drawing down deposits while spending heavily on long-term assets. Construction in progress rose from VND 97 billion at the start of the year to VND 578 billion, almost sixfold. Over nine months the company incurred VND 644 billion of purchase and construction costs. The closing balance includes VND 289 billion for factory and office construction, VND 253 billion for fixed-asset purchases and VND 35 billion for fish ponds.FireAnt
Short-term receivables also rose, to VND 2,624 billion, of which VND 1,931 billion is trade receivables. On the funding side, borrowings rose VND 1,123.1 billion while short-term deposits fell about VND 500 billion. The statements show these lines moving over the same period but do not tie any specific loan to any specific outlay, so this article does not assign a purpose to the borrowing.
On financial strength, the picture is still sturdy. Cash and short-term financial investments at quarter-end were VND 3,928.5 billion, 27.3% of total assets and more than total borrowings of VND 3,169.2 billion. Borrowings equal about 31.6% of equity of VND 10,043 billion.Tin nhanh chứng khoán The difference from last year is that this cash pile no longer produces a net financial gain.
A 14.5% gross margin: low against last year, not unusual for the series
The 14.5% gross margin is below Q3 2025, but across recent quarters it is not an abnormal level for Vinh Hoan. Gross margin was 14.6% in Q1 2026, rose to 20.7% in Q2 2026, then returned to 14.5% in Q3. In 2025 it ranged from 12.7% in Q1 to 19.8% in Q2.
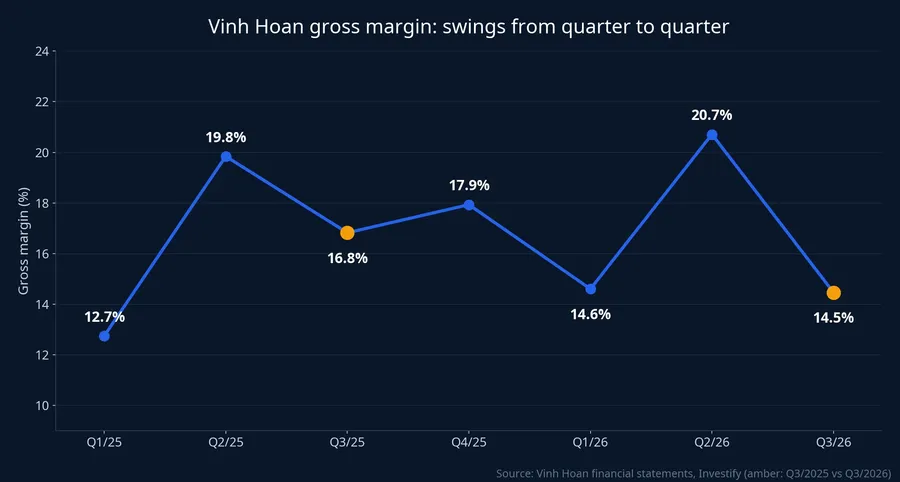
Given that swing, Q2 2026 looks like the unusually high point rather than Q3 being an unusual low. Raw-fish prices, feed prices and selling prices in each market could all play a part, and only the company's own reporting can separate their contributions.
In the market, VHC closed on October 30 at VND 50,300 per share, 17.7% below the VND 61,100 recorded on June 25.Tin nhanh chứng khoán
Two parts of the story behave differently
Interest expense is the recurring part. As long as debt stays around VND 3,169 billion, interest of about VND 37 billion a quarter will keep appearing in later quarters. It shrinks only if Vinh Hoan repays debt or borrows at lower rates. Financial income is harder to predict, since it depends on deposit balances and other financial items.
Gross margin is the unanswered part. The monthly revenue figures Vinh Hoan publishes will show sales by market. The Q4 financial statements will show whether the margin climbs back toward the Q2 level or stays near 14.5%. If it recovers, most of the Q3 shortfall was one quarter of high cost of goods. If it stays flat, quarterly profit will sit on a lower base than last year while interest expense stays at its new level. With 59.7% of the profit plan already reached after nine months, Q4 is the deciding quarter.