
In Q3 2026, VietinBank (CTG) posted consolidated pre-tax profit of VND 13,689 billion, up 29% year on year. Vietcombank (VCB) earned VND 11,218 billion, down 0.2%. The gap in the quarter was VND 2,471 billion.Tạp chí Kinh tế - Tài chính Over the first nine months, though, Vietcombank still leads: pre-tax profit of VND 40,440 billion, up 22.1%, against VND 39,557 billion, up 33.9%, at VietinBank. The difference is VND 883 billion.
Where did the Q3 ranking flip? The answer sits in the provision line, so it helps to put the two banks side by side on each line of the income statement: net interest income, pre-provision profit, provisions, and only then pre-tax profit.
Income: both had a strong quarter
Vietcombank's Q3 net interest income was VND 20,386 billion, up 39.1%. Foreign-exchange trading income doubled to VND 2,576 billion, while net fee income slipped 3.6% to VND 904 billion.Người Quan Sát According to Vietcap Securities, as relayed by CafeF, Vietcombank's net interest margin (NIM) rose to 3.09% this quarter, up 12 basis points from the previous quarter.CafeF After operating costs, Vietcombank's pre-provision profit came to VND 17,402 billion, up 44.8% from Q3 2025.
VietinBank grew more slowly but from a larger base. Q3 net interest income was VND 21,816 billion, up about 27%, and fees brought in VND 2,487 billion net, up 56.7% and nearly three times Vietcombank's figure.Người Quan Sát Its pre-provision profit was VND 21,469 billion, up 30.3%.Mekong ASEAN
On growth, then, Vietcombank's pre-provision profit rose faster. On scale, VietinBank earned about VND 4,067 billion more before provisions.
Provisions: where the ranking flipped
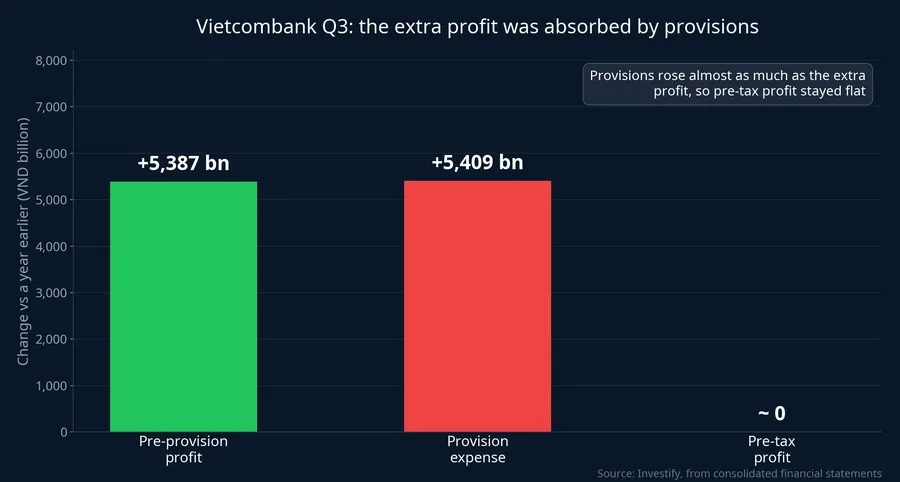
Vietcombank booked VND 6,184 billion of credit-loss provisions in Q3, almost 8 times the VND 776 billion of a year earlier. The increase alone, more than VND 5,400 billion, roughly equals the rise in pre-provision profit during the quarter. That is why pre-tax profit stayed almost flat even as the business grew. Q3 also accounted for over 67% of the bank's nine-month provision expense of VND 9,180 billion.Người Quan Sát
Which assets is the provision for? According to Vietcap's analysts, about VND 5,000 billion was set aside for a batch of corporate bonds tied to a client in the energy sector. Vietcap says Vietcombank moved these bonds into the bad-debt group in Q4 2025 without fully provisioning them at the time, and in Q3 2026 provisioned 100% of the batch's value. The analysts call it an isolated case, outside their expectations.CafeF The financial statement notes show specific provisions for unlisted corporate bonds rising from VND 3,307 billion at the start of the year to VND 6,304 billion at end-September.Người Quan Sát
VietinBank also raised provisions, but at a steadier pace: VND 7,780 billion in Q3, up 32.7%, about VND 1,596 billion above Vietcombank's figure.Người Quan Sát
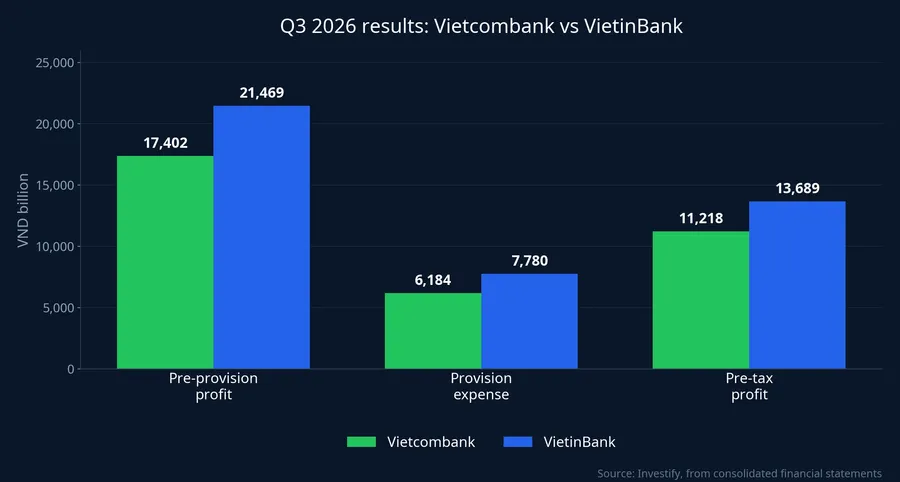
The Q3 arithmetic is therefore simple. VietinBank earned about VND 4,067 billion more before provisions and provisioned about VND 1,596 billion more, so its pre-tax profit came out exactly VND 2,471 billion higher.
A year earlier the order was reversed. Backing out the reported growth rates, Q3 2025 pre-tax profit was roughly VND 11,240 billion at Vietcombank and roughly VND 10,610 billion at VietinBank. Over the year, Vietcombank's pre-provision profit grew by about VND 5,387 billion, more than VietinBank's roughly VND 4,991 billion. The ranking flipped because Vietcombank's extra provisions exceeded VietinBank's by about VND 3,500 billion.
Nine months: Vietcombank leads on lower provisions
Over the full nine months the picture is clearer than in one quarter. Vietcombank's pre-provision profit was VND 49,620 billion, up almost 40%.CafeF VietinBank's was about VND 60,338 billion, which is pre-tax profit of VND 39,557 billion plus provision expense of VND 20,781 billion.Người Quan Sát
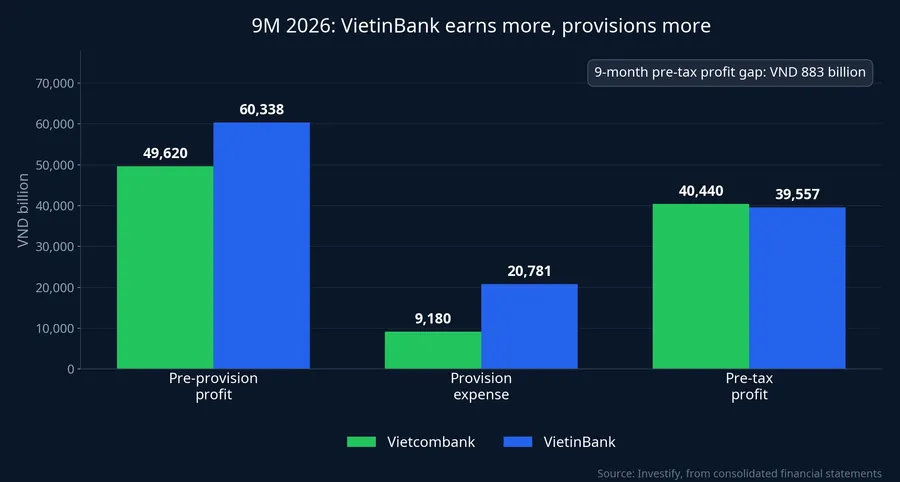
Before provisions, VietinBank earned about VND 10,700 billion more than Vietcombank. On provisions, it booked about VND 11,600 billion more (VND 20,781 billion versus VND 9,180 billion). The difference between the two is the VND 883 billion by which Vietcombank leads. Put differently, Vietcombank's nine-month first place comes from much lower provision expense, while VietinBank has the larger earning power before provisions.
Asset quality: two different baselines
The different provisioning levels reflect two different bad-debt baselines. At end-September, Vietcombank's on-balance-sheet bad debt was VND 12,818 billion, a ratio of 0.71%, up from 0.58% at the start of the year. Vietcap notes the ratio rose 10 basis points from the previous quarter but fell 33 basis points from a year earlier. The coverage ratio dropped from 279% at the end of Q2 to 243%, which Vietcap still rates as the highest in the sector.CafeF Group 3 and group 4 loans combined exceed VND 4,200 billion, nearly 4 times the start of the year.Người Quan Sát
VietinBank's on-balance-sheet bad debt is VND 25,781 billion, a ratio of 1.20%, up from 1.10% at the start of the year. Some roundups cite 2.89%, but the figure in the financial statements is 1.20%, consistent with bad debt divided by loans of VND 2.14 quadrillion. Its coverage ratio rose to 160.4% from 134% at the end of Q2. Group 3 and group 4 loans combined stand at VND 10,480 billion, against VND 2,069 billion at the start of the year. VietinBank says its bad debt is concentrated in transport construction, real estate, consumer loans, steel and textiles.Người Quan Sát
The two sets of numbers move in opposite directions. Vietcombank has the lower bad-debt ratio and the thicker cushion, but the cushion thinned in Q3 because of the bond batch. VietinBank has the higher ratio, provisions heavily and steadily, and its cushion thickened in Q3.
BIDV moved the other way
Bank for Investment and Development of Vietnam (BIDV) shows that the provision line can pull quarterly profit in the opposite direction. Its Q3 pre-tax profit was VND 10,579 billion, up 39.3%, while net interest income rose only 12.4%. The gap came from provision expense falling 25% to VND 4,640 billion. VPBank earned VND 11,031 billion, just VND 187 billion below Vietcombank.Tạp chí Kinh tế - Tài chính Three large banks, three directions from the same cost line. When reading a quarterly profit ranking, look at provisions before pre-tax profit.
Market reaction
On 2 November, the first session after the two banks' reports were rounded up by the press, VCB fell 4.80% to VND 53,600 on about 14 million shares traded, nearly 4 times the 30 October volume. CTG fell 1.82% to VND 29,750. The VN-Index closed at 1,710.72, down 1.77%.
The drop in VCB cannot be pinned entirely on the provision. In the same session BID fell 4.19% despite BIDV's strong Q3, and the market declined broadly, with 295 decliners against 50 advancers. The surge in VCB volume suggests the provision news may have contributed, but the broad slide in bank stocks was also a major force.
What to watch in Q4
The Q3 gap between the two banks mostly comes from one large provision at Vietcombank, which Vietcap treats as an isolated case. Vietcombank's pre-provision profit is still growing faster, while VietinBank has the larger earning power before provisions.
What decides the 2026 full-year leader is each bank's Q4 provision expense relative to its pre-provision profit. If Vietcombank returns to provisioning close to earlier quarters, its fast-growing pre-provision profit flows straight into pre-tax profit and the VND 883 billion lead has a basis to hold. If VietinBank sustains its Q3 provisioning pace and its group 3 and group 4 loans do not slip into group 5, its scale advantage before provisions will keep narrowing that gap. The Q4 and full-year financial statements will show which branch plays out.