
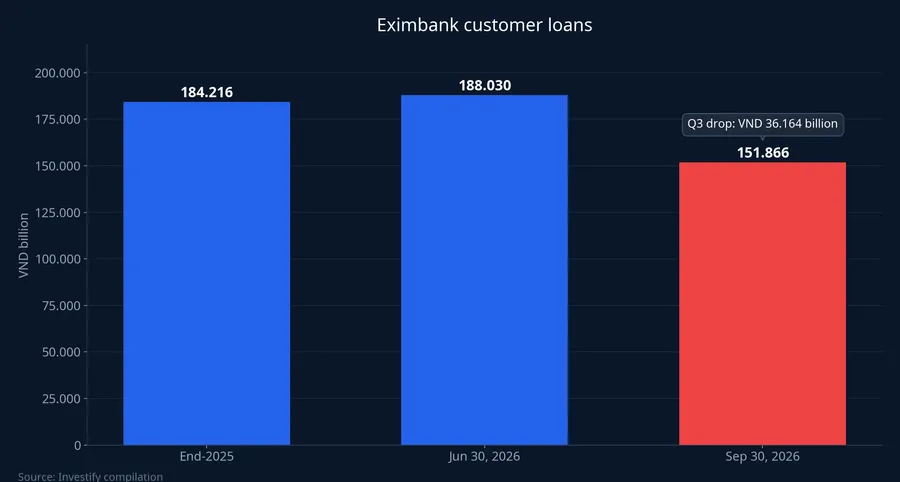
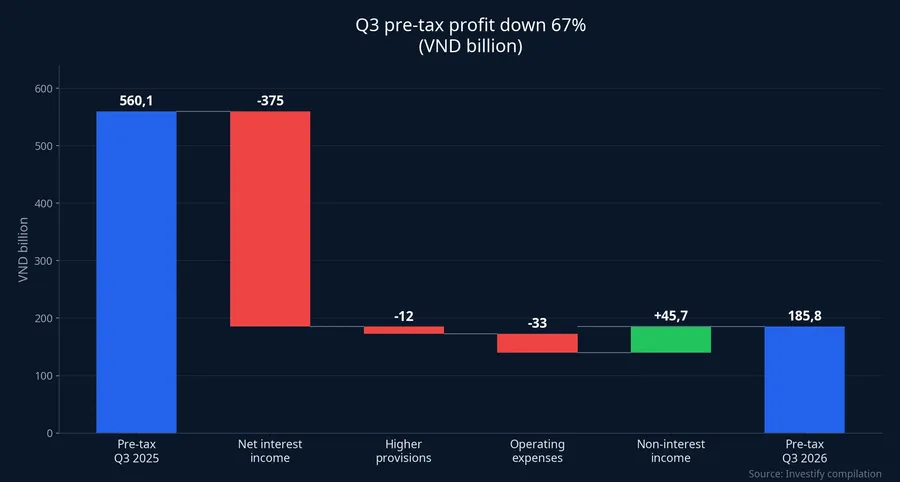
Between June 30 and September 30, 2026, customer loans at Vietnam Export Import Commercial Joint Stock Bank (Eximbank, HoSE: EIB) went from about VND 188,030 billion to VND 151,866 billion. That is a drop of roughly VND 36,164 billion, more than 19% from the end of Q2.Kinh tế Chứng khoán In the same quarter, pre-tax profit came to VND 185.8 billion, down 66.8% from VND 560.1 billion in Q3 2025.Kinh tế Chứng khoán It is tempting to read the two numbers as one sentence: less lending, less profit.
The consolidated financial statements do not support that reading. Interest income still rose in Q3, and the main drag on earnings was interest expense. On safety, Eximbank reports a capital adequacy ratio above 13%, an LDR of 73%, and a bad-debt ratio that eased to 2.62%.Thời báo Tài chính Việt Nam Nine-month pre-tax profit was VND 864.3 billion, about 57% of the full-year plan.Báo Đầu tư This post covers three things: how much smaller the bank got, why Q3 profit fell, and which layer of debt is left for Q4.
Scale: Smaller at Both Ends of the Balance Sheet
Figures are consolidated. Loans before provisions on September 30 stood at VND 151,865.6 billion, about VND 32,350 billion (17.6%) below end-2025.Kinh tế Chứng khoán Loans were still growing in H1, up more than VND 3,800 billion from January, so the entire contraction landed in a single quarter.
Funding also fell, though more slowly. Customer deposits at end-September were VND 158,298.9 billion, about VND 12,310 billion below end-June and more than VND 19,000 billion below the start of the year. Total assets fell from VND 273,270.4 billion to VND 241,495.1 billion, down 11.6% from end-2025.Kinh tế Chứng khoán According to Doanh nhân Việt Nam, this runs against most of the system, where balance sheets are still expanding, and against an earlier MBS Research forecast of roughly 5% Q3 credit growth at Eximbank.Doanh nhân Việt Nam
Eximbank says it is stepping up debt resolution, restructuring its credit portfolio and deliberately shrinking high-risk or low-return segments, and that it prioritizes growth quality over size and short-term profit.Thời báo Tài chính Việt Nam For depositors, the two figures worth more than size are the capital ratio above 13% and the 73% LDR, both self-reported: the bank is smaller, but deposits still exceed loans. The notes to the statements also record a Q3 debt sale to the Vietnam Asset Management Company (VAMC), with a provision reversal of VND 380.6 billion.Kinh tế Chứng khoán
Q3 Profit: Interest Expense Outran Interest Income
If a shrinking loan book were the reason profit fell, interest income would have dropped first. It did the opposite: Q3 total interest income was VND 4,507.9 billion, up 16.8% year on year, while interest expense reached VND 3,417.7 billion, up 42.8%.Kinh tế Chứng khoán In money terms, interest income rose by about VND 649 billion and interest expense by about VND 1,024 billion (computed from the two growth rates).
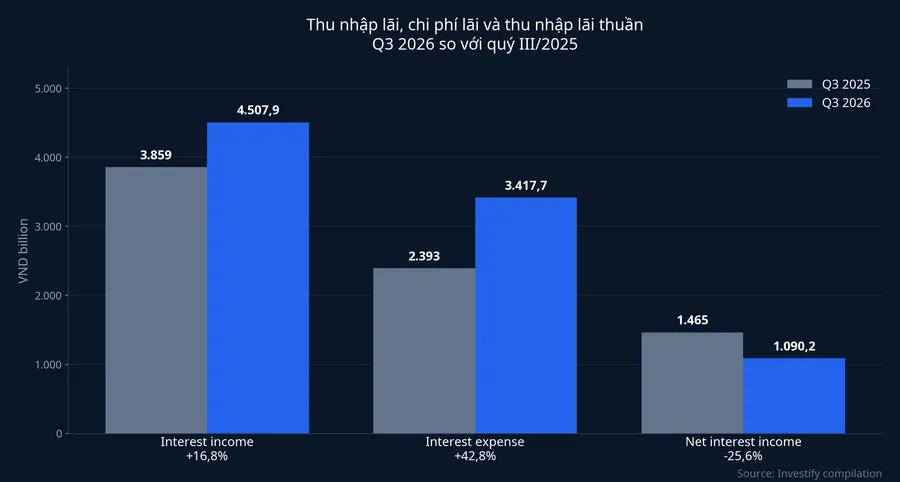
As a result, net interest income, the bank's main earnings line, fell 25.6%, from VND 1,465 billion to VND 1,090.2 billion.Kinh tế Chứng khoán That gap of about VND 375 billion is close to the entire drop in Q3 pre-tax profit, around VND 374 billion. One caveat: interest income and expense are flows over the whole quarter, while loans are a September 30 snapshot, so the effect of the contraction should show up more clearly in later quarters.
The other lines roughly offset each other. Net foreign-exchange trading income fell from VND 100.1 billion to VND 26.2 billion, while net other income rose from VND 83 billion to VND 186 billion.Báo Đầu tư Operating expenses rose 3.6% to VND 957.9 billion.Doanh nhân trẻ Credit provisions for Q3 alone were VND 199.2 billion, up only 6.2%, so provisions were not the main driver this quarter.Kinh tế Chứng khoán Separately, valuable papers issued by the bank rose 7% from January to VND 21,470 billion, moving against customer deposits.Doanh nhân trẻ
Nine Months: Provisions Are the Big Item
Over nine months the picture changes. Cumulative pre-tax profit is VND 864.3 billion, down 57.8% year on year. Nine-month credit provisions were VND 997.4 billion versus VND 516 billion a year earlier, higher than pre-tax profit itself.Báo Đầu tư At the annual general meeting, management said it would keep provisioning at a high level,Doanh nhân Việt Nam and most of that charge already sits in Q1 and Q2.
The 2026 pre-tax profit plan put to shareholders is VND 1,515 billion.Báo Pháp luật To reach it, Q4 would need about VND 651 billion, roughly 3.5 times Q3's VND 185.8 billion.
Debt Quality: Bad Debt Down, Group 2 More Than Doubled
On the positive side, group 3 to 5 bad debt at end-September was just under VND 3,973 billion, about VND 1,821 billion lower than VND 5,794 billion at end-June. The NPL ratio fell from about 3.08% to 2.62%.Kinh tế Chứng khoán The VAMC sale in the quarter is one of the channels behind that decline.
On the other side, group 2 (special mention) debt rose to VND 4,613.6 billion, from about VND 3,060 billion at end-June and VND 2,191.6 billion at end-2025, an increase of 110.5% since January.Doanh nhân trẻ Group 3 debt also rose, from VND 701.5 billion to VND 1,868.9 billion since the start of the year.Kinh tế Chứng khoán
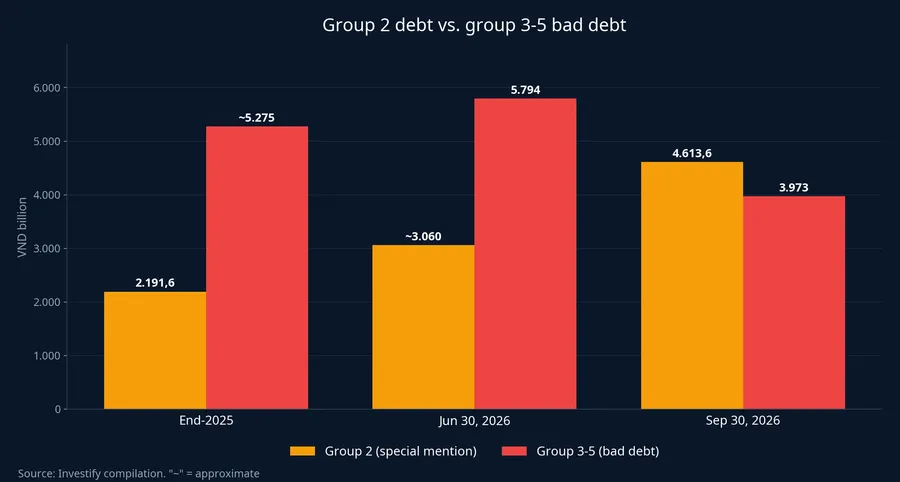
Group 2 is not bad debt. It covers loans overdue by 10 to 90 days or flagged for monitoring under classification rules, and it can move back to group 1 once borrowers pay on time again. Even so, groups 2 to 5 together total about VND 8,587 billion, or 5.65% of loans, versus 4.05% at end-2025.Kinh tế Chứng khoán Part of the rise in the ratio comes from a smaller loan base, but the absolute amount also grew, from about VND 7,464 billion in January.
The bad-debt coverage ratio at end-Q3 was 41%, below 44% at the start of the year and among the lowest in the system.Báo Đầu tư Loan-loss reserves stood at about VND 1,644.5 billion at end-September, against VND 2,314.1 billion at end-2025.Kinh tế Chứng khoán Put side by side: older bad debt has been cleared, partly through the debt sale, while a group 2 layer larger than total bad debt awaits Q4.
Market Reaction
On October 30, when the Q3 report came out, EIB fell 4.17% to VND 16,100. On November 2, as the VN-Index dropped 1.77% to 1,710.72 points, EIB closed at VND 16,050, down a further 0.31%, for a market capitalization of about VND 29,900 billion.
What Q4 Will Answer
The thesis: Eximbank's Q3 profit fell because the gap between interest income and interest expense narrowed, not because the loan book got smaller. The contraction is a decision the bank describes as deliberate, and its published safety ratios remain within limits. The Q4 report will settle two specific points.
First, the roughly VND 4,613.6 billion of group 2 debt. If it falls without a matching rise in groups 3 to 5, most of it went back to group 1. If group 2 falls while bad debt rises, loans have slipped down, and with 41% coverage the bank would have to book more provisions within the quarter.
Second, full-year profit. If Q4 net interest income returns to near last year's level, the VND 1,515 billion target has a basis. If it stays around Q3's VND 1,090 billion while loans are about 19% below mid-year, full-year profit is likely to land below plan. Both signals are worth tracking when Eximbank publishes its Q4 report.