

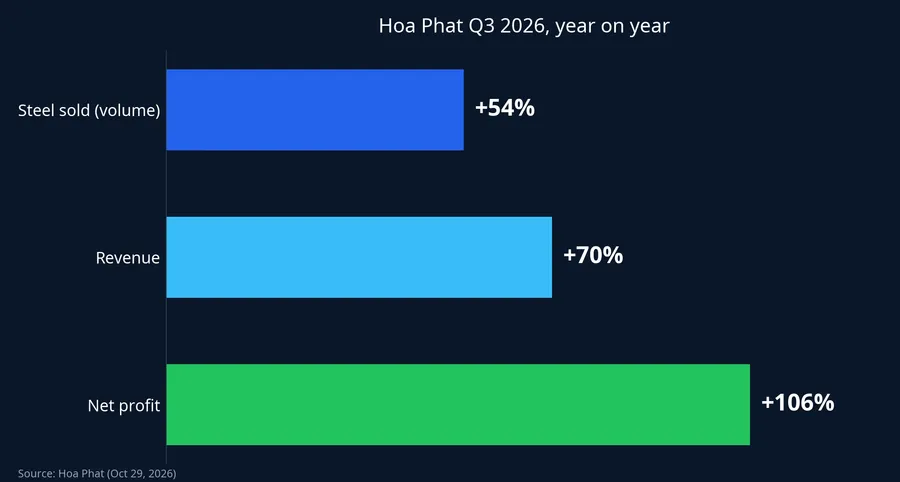
On the morning of October 29, 2026, Hoa Phat Group (HPG) reported Q3 net profit of VND 8,265 billion, up 106% from a year earlier. Revenue for the quarter was VND 62,669 billion, up 70%. Steel sold came to 3.8 million tonnes, up 54%.Hòa Phát
The three growth rates are not equal. Volume grew slowest, revenue a little faster, and profit nearly twice as fast as volume. For anyone holding HPG, the gap between the three numbers is the part worth reading closely. It shows whether a bigger plant has turned into more profit for shareholders, and what that profit rests on.
Per tonne, profit is about a third thicker
The simplest read is to divide profit by steel sold. In Q3 2026 Hoa Phat sold 3.8 million tonnes and earned VND 8,265 billion, roughly VND 2.2 million of profit per tonne. A year earlier it sold about 2.47 million tonnes and earned about VND 4,010 billion (both backed out from the 54% and 106% growth rates Hoa Phat reported), or about VND 1.6 million per tonne. Average profit per tonne is therefore about 34% higher.
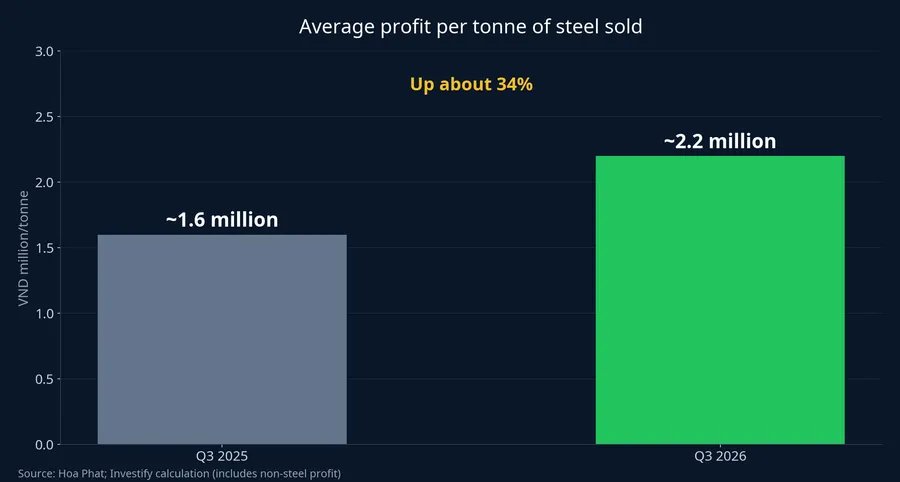
This division also folds in profit that does not come from steel, so it is a rough yardstick. Still, steel made up 97% of revenue and 77% of nine-month profit,Hòa Phát large enough that the direction of the calculation reflects the steel business.
Net margin points the same way. In Q3 2026, net profit was about 13.2% of revenue. In Q3 2025 it was about 10.9% (profit of about VND 4,010 billion on revenue of about VND 36,860 billion, again derived from the reported growth rates). For every VND 100 of revenue, Hoa Phat kept roughly VND 2.3 more in profit than a year ago.
Scale: most of the jump came before Q3
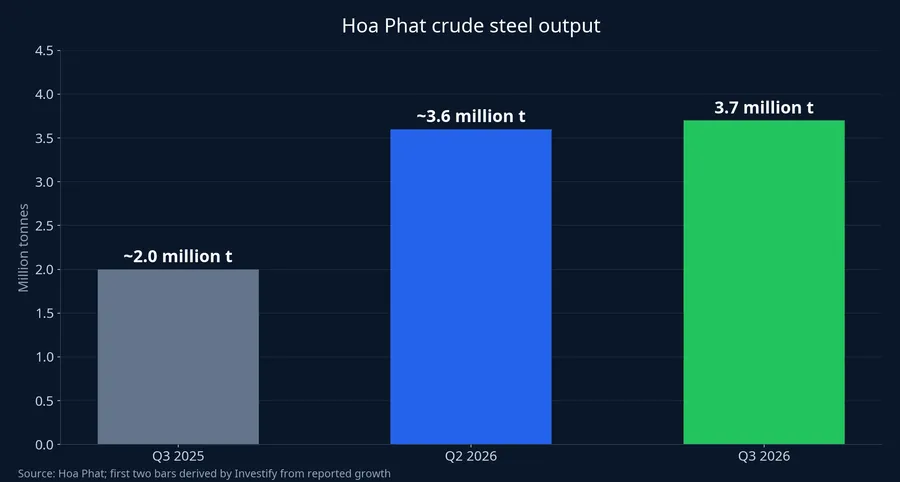
In Q3 2026 Hoa Phat produced 3.7 million tonnes of crude steel, up 85% year on year but only 3% on Q2.Hòa Phát Set side by side, the two growth rates show that the step-up in capacity happened in earlier quarters. In Q3 the furnaces mostly ran steadier rather than adding new capacity.
Most of the added capacity is tied to the Dung Quat 2 complex in Quang Ngai. According to VCBS, Dung Quat 2 is running both phases and its Q3 utilization is estimated at about 95%.Tin Nhanh Chứng Khoán That is a brokerage estimate, not a figure Hoa Phat has reported.
Sales ran ahead of production in the quarter: 3.8 million tonnes sold, up 8% on Q2, while crude steel rose only 3%. Hot-rolled coil alone exceeded 2 million tonnes, up 64% year on year, the largest product line.Hòa Phát
From volume to revenue: about 10% more per tonne
Revenue rose 70% while volume rose 54%. Per tonne sold, revenue is about 10% higher than a year ago. That 10% blends three things: the average selling price, the product mix, and revenue from non-steel businesses and downstream products such as steel pipe (681,000 tonnes in nine months) and coated sheet (more than 307,000 tonnes), none of which sit inside the 3.8 million tonne figure.Hòa Phát
Product mix is one clear force. Hot-rolled coil grew 64%, faster than the 54% for total sales, so its share of the basket is larger than a year ago. Price is the second force. Its contribution will only be visible once the consolidated Q3 statements disclose cost of goods sold, so this post does not assign the gap to price.
From revenue to profit: the advantage of a nearly full plant
Profit growing faster than revenue has three possible explanations. First, cost per tonne falls when furnaces run near capacity, because depreciation, labor and other fixed costs of a large complex are spread over more tonnes. Second, selling prices rise faster than raw material prices. Third, non-operating items such as financial income.
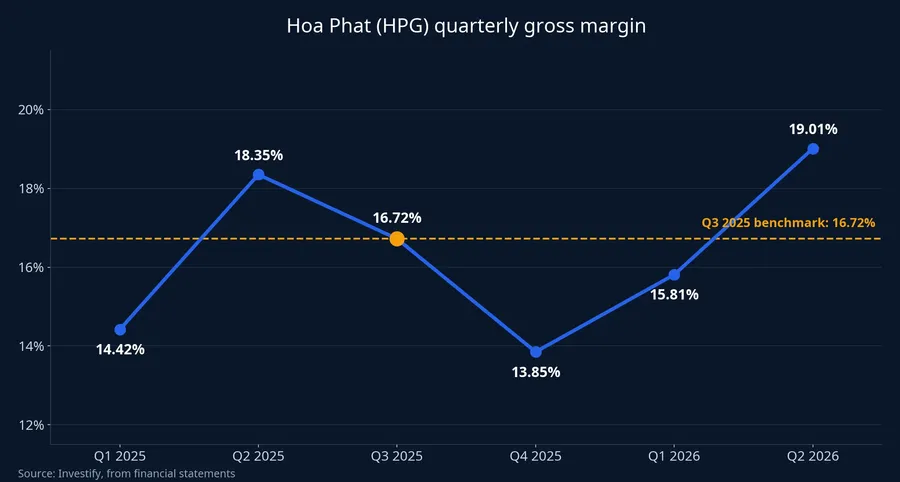
Earlier quarters show that Hoa Phat's gross margin swings quite widely. In 2025 the quarterly gross margin ranged from 13.85% to 18.35%, with Q3 2025 at 16.72%. In 2026, Q1 was 15.81% and Q2 was 19.01%, even though Q2 revenue was only about 4% above Q1 (VND 55,159 billion against VND 52,901 billion). A margin jump of more than 3 percentage points in one quarter, with revenue barely changed, suggests selling prices and raw material prices are still a major force. Scale efficiency and price effects both operate, and the Q3 gross margin will show which weighs more.
The third explanation is also present this year, but in Q1, not Q3. In Q1 2026, net profit attributable to the group's shareholders was VND 8,994 billion, and financial income reached VND 5,938 billion, against only VND 616.7 billion in Q2. Q2 profit attributable to shareholders was VND 6,371 billion. The Q3 figure is consolidated profit, including minority shareholders' share, so set beside those two quarters it only gives a sense of scale. Even so, the direction is fairly clear: Q3 profit is below Q1 but well above Q2, and compared with Q1, Q3 leans much more on operations.
23% of profit does not come from steel
Steel contributed 77% of nine-month profit. The remainder is about VND 5,460 billion out of VND 23,746 billion in total.Hòa Phát Agriculture is the second-largest contributor: Hoa Phat Agriculture (HPA) earned VND 948 billion in nine months,Hòa Phát less than a fifth of the non-steel profit. Most of the rest comes from real estate, home appliances and other items, including the large financial income of Q1.
This means steel's 77% share of nine-month profit may be lower than its share of Q3 alone. With Q1's financial income not repeating, profit in later quarters will lean more heavily on steel.
The annual plan is done, what is left for Q4
Hoa Phat set its 2026 plan at VND 210,000 billion of revenue and VND 22,000 billion of net profit. After nine months, revenue was VND 171,539 billion, 82% of plan, and profit was VND 23,746 billion, 108% of plan.Hòa Phát This is consolidated net profit, including the share of minority shareholders in subsidiaries.
Over nine months Hoa Phat produced 10.7 million tonnes of crude steel, up 35%, and sold 10.3 million tonnes, up 39%. The next project is the Dung Quat railway and special steel plant, with capacity of 700,000 tonnes a year, 80% complete and expected to deliver rail products from Q2 2027. It adds no output in 2026.Hòa Phát
On the exchange, in the middle of the morning session on October 29, HPG was up 3.37% at VND 21,450. That is an intraday price, not a closing price.
How durable the extra profit is
The extra volume at Hoa Phat has turned into profit, and at a wider margin than a year ago. Profit per tonne is about a third higher, net margin is about 2.3 percentage points wider, and the full-year profit plan was exceeded by 8% before Q4 began.
The open question is where the wider margin comes from. A margin that comes from lower cost per tonne at a nearly full plant lasts longer than one that comes from selling prices, because the benefit of spreading fixed costs over more tonnes remains when steel prices turn. Hoa Phat's quarterly gross margin has ranged from 13.85% to 19.01% in nearly two years, so steel prices cannot be set aside.
When the consolidated Q3 statements are published, the Q3 gross margin is worth placing next to two markers: 16.72% in Q3 2025 and 19.01% in Q2 2026. If cost of goods sold per tonne is below a year ago, the extra profit mainly reflects a more efficient plant. If cost per tonne has not fallen and the margin is still wide, profit is leaning more on selling prices and will be more sensitive to steel prices in coming quarters.