

OCB's cumulative pre-tax profit for the first nine months came to VND 4,123 billion, up 20.2% year on year, or 59% of its full-year plan of VND 6,960 billion.Bnews That sounds healthy. But the remainder is about VND 2,837 billion to be earned in the last three months of the year, more than any single quarter so far. At the same time, the NPL ratio has risen to 3.99% and customer deposits are below their end-Q2 level. This post sets the Q3 2026 numbers side by side to see where the quality of that profit sits.
The report landed as Mr. Dương Đức Hùng, General Director (CEO) of Orient Commercial Joint Stock Bank (OCB), took office on October 26, under an appointment announced on October 21.CafeF That is context only. The sources do not say what the new management will do differently, so this post does not speculate on strategy.
What Q4 has to deliver
The VND 6,960 billion pre-tax profit plan is 39% above 2025's result.Vietstock Subtract the VND 4,123 billion already booked and OCB has about VND 2,837 billion left to make.
Compare that with earlier quarters: Q1 was about VND 1,224 billion (derived from Q2 profit of VND 1,246 billion, up 1.9% on Q1), Q2 was VND 1,246 billion,Tạp chí Kinh tế Tài chính and Q3 was just over VND 1,653 billion, up 7.5% year on year.Bnews Q4 would therefore need to be about 1.7 times the best quarter of the year so far.
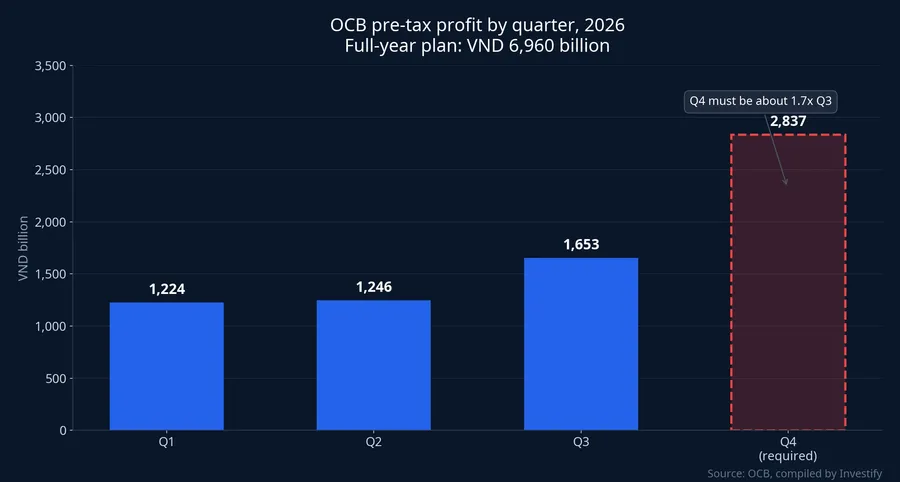
Another yardstick: VND 2,837 billion is about 56% of the bank's full-year 2025 pre-tax profit of VND 5,046 billion.Nhà đầu tư In other words, the final three months must produce more than half of what all of last year did.
Where Q3 profit came from
The bank's press release stresses growth. Q3 net interest income was VND 2,768 billion, up 14.2% year on year, and total operating income reached VND 3,291 billion, up 12.3%.Bnews Net fee income rose about 62% to VND 300.9 billion.Nông nghiệp và Môi trường
Other lines moved the other way. Trading securities income fell 80.2% to VND 13.3 billion, investment securities posted a VND 12.2 billion loss, and income from other activities dropped 44% to VND 145.4 billion. That is why Q3 pre-tax profit grew only 7.5% year on year, far slower than the 20.2% for nine months.Nông nghiệp và Môi trường
Against Q2, Q3 pre-tax profit was about VND 407 billion higher (1,653 versus 1,246). Over the same period, provisioning expense went from VND 905 billion to VND 494.6 billion, about VND 410 billion less.Tạp chí Kinh tế Tài chính The two figures are close, so the quarter-on-quarter profit gain almost exactly matches the money the bank set aside less.
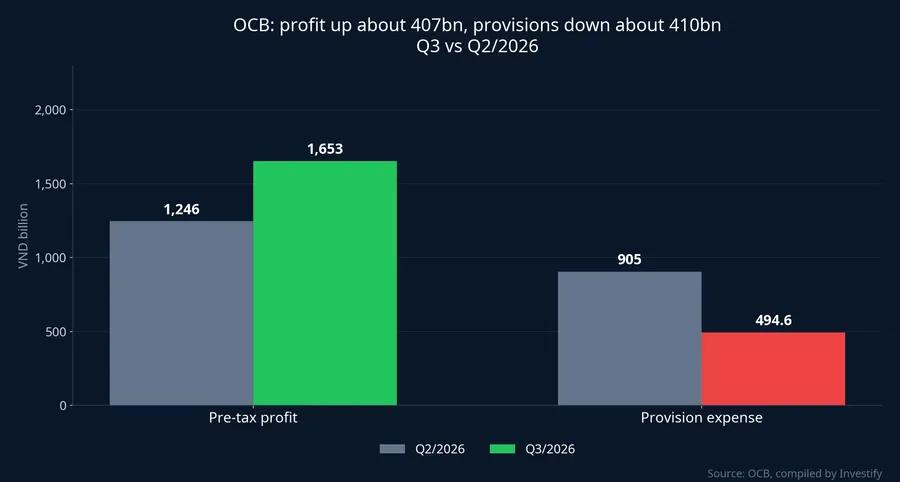
This deserves a fair reading. Interest and fee income still grew year on year, so the core business is not standing still. Some provisioning may also have been front-loaded in Q2, when it rose 85% on Q1, which would make a lighter Q3 reasonable. Still, with bad debt rising through Q3, provisioning this low is hard to sustain.
NPLs move further from the sub-3% target
At September 30, 2026, OCB's non-performing loans were VND 8,767 billion, up 38.2% year on year, or 3.99% of outstanding loans. The bank's full-year target is below 3%.Nông nghiệp và Môi trường At the end of Q2 the ratio was 3.5%.Tạp chí Kinh tế Tài chính
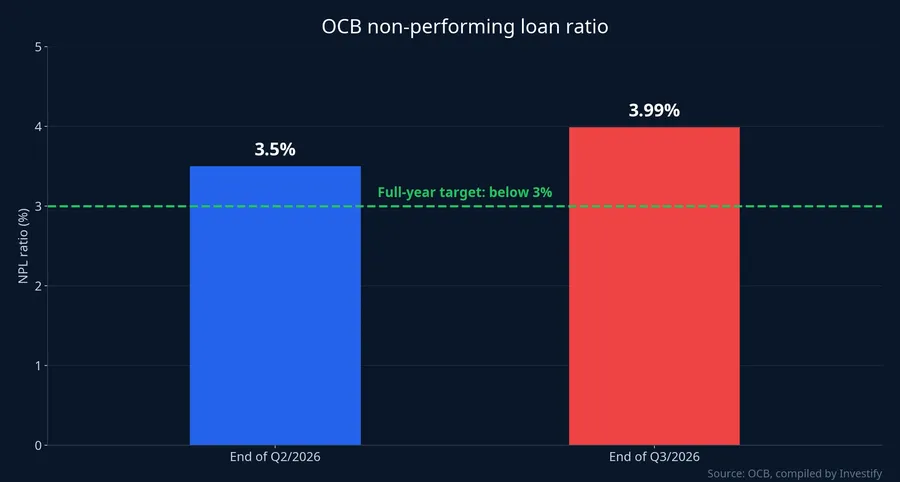
Of the VND 8,767 billion, substandard loans were VND 1,408 billion, doubtful loans VND 1,508 billion, and loans likely to be lost VND 5,851 billion, about two-thirds of the total. That last category carries the heaviest provisioning requirement. It was VND 5,438 billion at the end of Q2, so it grew by about VND 413 billion in Q3.
Loan-loss reserves at September 30 stood at VND 5,096 billion.Nông nghiệp và Môi trường Divided by NPLs, coverage is roughly 58%, below the 59.4% at the end of Q2.Tạp chí Kinh tế Tài chính Bad debt is growing faster than the reserves behind it. If the bank wants to hold coverage near 60% while NPLs keep rising, Q4 provisioning is unlikely to be as low as Q3's, and that comes straight out of the VND 2,837 billion it needs to earn.
A note on sourcing: the Q3 NPL ratio appears in only one outlet so far, and the bank's press release does not state it. It is worth cross-checking once the full financial statement notes are published.
Customer deposits fell in Q3
At September 30, 2026, customer deposits were VND 152,005 billion, up 1.3% from the start of the year.Nông nghiệp và Môi trường The nine-month figure hides the quarterly move: at the end of Q2, customer deposits were VND 159,695 billion.Tạp chí Kinh tế Tài chính So deposits fell by about VND 7,690 billion in Q3, roughly 4.8%.
The fastest-growing source of funding was other banks. Deposits from other credit institutions at OCB rose to VND 87,155 billion, up 59% since the start of the year, while valuable papers issued grew only 3.34%. The figure needs reading both ways: OCB also placed VND 74,805 billion with other credit institutions, up 41%.Nông nghiệp và Môi trường Inflows exceed outflows by about VND 12,350 billion. Net reliance on other banks is therefore still small against nearly VND 152,000 billion of customer deposits, but it has grown quickly this year.
Interbank funding tends to be short-dated, with costs that reset frequently, while retail deposits are steadier. According to OCB's press release, liquidity safety ratios, including the loan-to-deposit ratio (LDR), are within regulatory limits.Bnews That is the bank's own assessment, and the release gives no specific figure.
Quality of growth and what to watch
Taken together, OCB's nine-month profit growth of over 20% rests on interest and fee income, so the core business is still moving up. But the Q3 jump over Q2 came mainly alongside lighter provisioning, while NPLs rose to 3.99% and coverage slipped. The extra funding also leaned toward other banks rather than household deposits.
Earning VND 2,837 billion in Q4 takes two things at once: operating income growing much faster than in earlier quarters, and provisioning not rebounding. Those pull in opposite directions while loans likely to be lost keep climbing. A one-off item, such as a bad-debt sale or recovery of written-off loans, could narrow the gap, but the bank has not announced one. So if Q4 profit reaches the plan while provisioning falls again and NPLs keep rising, the headline number will look better than the quality behind it.
The Q4 2026 financial statements, due in early 2027, will show whether the VND 6,960 billion plan is met. Three signals deserve a close read: Q4 provisioning expense, the NPL ratio against the 3.99% mark, and whether customer deposits return above the VND 159,695 billion of end-Q2.