

At its annual shareholder meeting on October 20, Coteccons (CTD) said carried-over contracts at the end of fiscal 2025–26 reached VND 70,000 billion, up 98% year on year and the highest in the company's history.Tin nhanh Chứng khoán Yet management spent most of its presentation on something else: how much cash has actually come in, and why the company signed fewer new contracts last quarter.
The two topics are one. To see why, start with how a general contractor earns money.
How big is VND 70,000 billion of work?
In fiscal 2025–26 (ended June 30, 2026), Coteccons booked revenue of VND 34,340 billion and net profit of VND 788 billion.Tin nhanh Chứng khoán The carried-over book is therefore about twice last year's revenue. Against the VND 42,000 billion revenue plan for fiscal 2026–27, it covers roughly one year and eight months of construction even if the company signs nothing new.
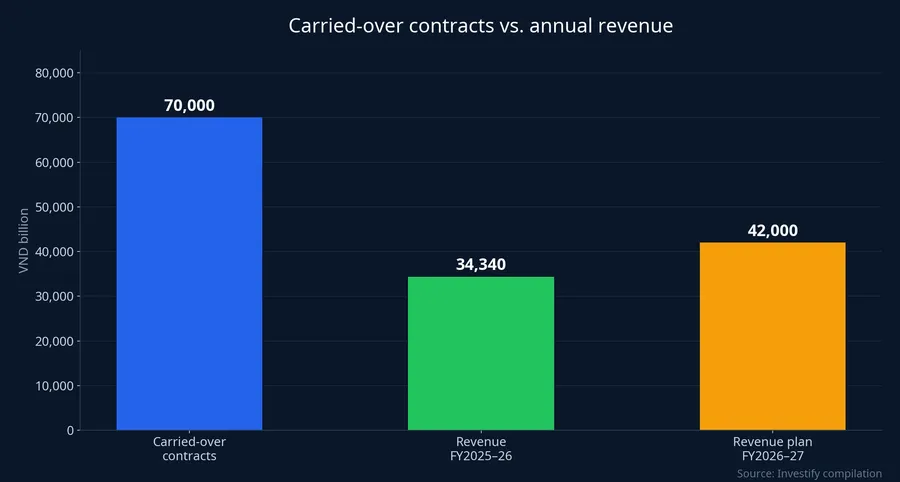
The figure nearly doubled in a year because new signings ran far ahead of revenue. New contract wins for the full year came to VND 60,307 billion, up 107% and about 1.8 times revenue booked over the same period.Tin nhanh Chứng khoán Work came in faster than it went out, so the backlog swelled.
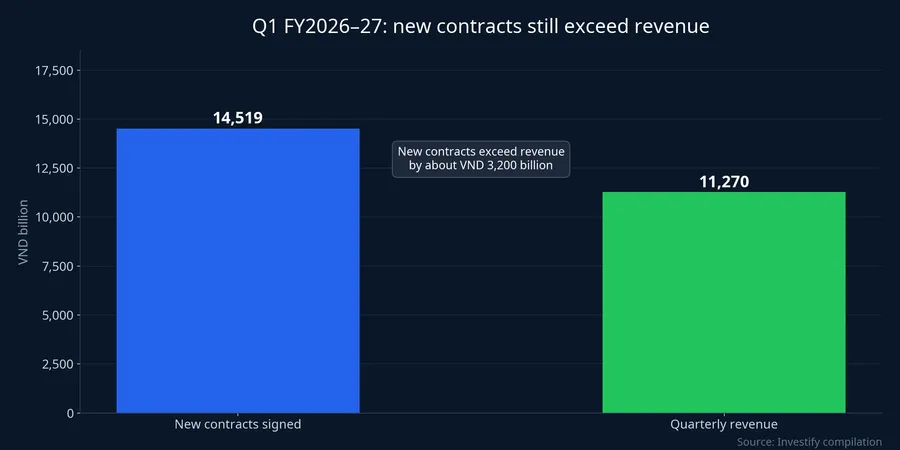
In the first quarter of fiscal 2026–27 (July 1 to September 30, 2026), signings slowed. Coteccons signed VND 14,519 billion of new contracts, below the same period a year earlier, while quarterly revenue was VND 11,270 billion and profit VND 306 billion, roughly 27% and 29% of the full-year plan.Tin nhanh Chứng khoán Even so, new signings exceeded quarterly revenue by about VND 3,200 billion, so the backlog has not shrunk. Coteccons is signing less while it still has plenty of work, not because it is short of work.
Why a contractor with a full book signs less
Bolat Duisenov, Chairman of Coteccons, told the meeting that the lower first-quarter signings versus a year earlier do not signal anything negative.Tin nhanh Chứng khoán The company is applying stricter financial conditions when it picks projects. In his words, finishing a building is only half the journey in construction; the other half depends on whether the owner pays.
That sentence sums up how a general contractor makes money. Revenue is recognized as completed, accepted work, while cash arrives according to the payment terms in the contract. In the gap between the two, the contractor fronts money for materials, subcontractors and site wages. If the owner pays late or cannot pay, booked profit never turns into cash, and the costs already advanced may be lost.
For a thin-margin business, that risk weighs more than it looks. Management says Coteccons' gross margin used to sit at only 3–4%.Tin nhanh Chứng khoán At that level a VND 1,000 billion contract leaves roughly VND 30–40 billion of gross profit before overhead and interest. One owner defaulting on 10% of a contract's value is enough to wipe out the profit of two or three similar projects.
Nguyễn Chí Thiện, Deputy CEO of Coteccons and CEO of its CTD Business Unit 02, said at the meeting that losses on past projects were a lesson that pushed the company to screen customers more tightly, and that it keeps a rule of not taking projects at any price.Tin nhanh Chứng khoán The VND 70,000 billion backlog is what lets the company say that. A contractor short of work has to accept contracts with poor payment terms to keep crews and equipment busy. One with nearly two years of work can say no.
To be clear, this is a reading of the numbers. Management did not disclose how many projects it turned down in the first quarter or why. Part of the drop in new signings could also reflect a high comparison base, since signings rose 107% in the prior fiscal year.
Signal one: cash collected exceeds revenue
If selectivity works, it should show up in two places: cash collected and margin.
On cash, Coteccons said it collected about VND 13,000 billion in the first quarter, more than revenue booked in the period, or roughly 115% of quarterly revenue.Tin nhanh Chứng khoán Over fiscal 2025–26 it recovered VND 39,476 billion of receivables, also around 115% of annual revenue.Tin nhanh Chứng khoán
A ratio above 100% does not mean the company collected more than it built. Three components sit inside that number. Payments from owners usually include value-added tax, while recognized revenue does not. With a large batch of new contracts, part of the cash may be advances for work not yet started. Only the remainder is money collected on old debts. Management did not split the three. What can safely be said is that cash is keeping pace with revenue; the VND 13,000 billion figure alone does not show a strong recovery of legacy receivables.
This matters because Coteccons' operating cash flow swings sharply between quarters. According to its financial statements, operating cash flow was negative VND 1,733 billion in January to March 2026 and positive VND 2,585 billion in April to June 2026. Contractors tend to spend early in a project cycle and collect late, so one good quarter of cash is not enough to conclude that collection habits have changed.
Signal two: gross margin above 5%
On margin, management said first-quarter gross margin exceeded 5%, up from the previous 3–4%, thanks to better operating efficiency and cost optimization. The company also said it is using the advantage of buying materials in large volumes.Tin nhanh Chứng khoán
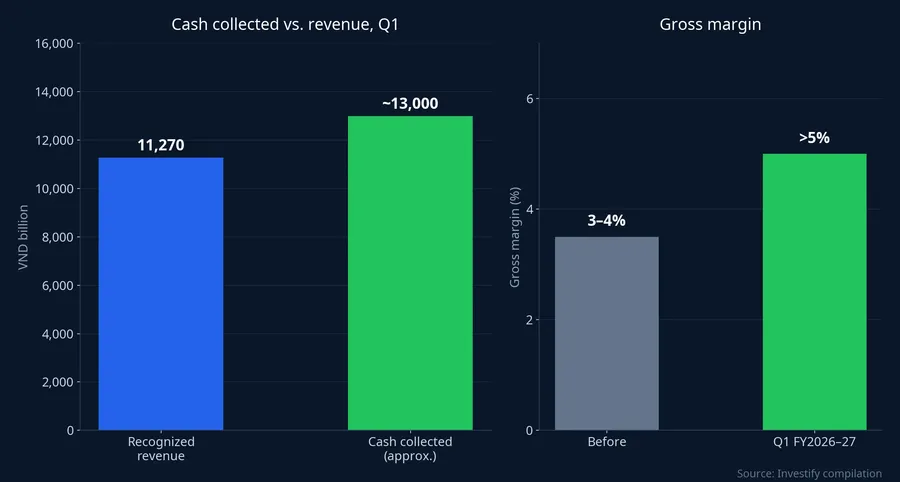
One percentage point of gross margin sounds small, but at this scale it is not. On a VND 70,000 billion backlog, each point equals roughly VND 700 billion of gross profit over the life of the work, close to last fiscal year's entire net profit. That is why margin, not contract value, decides what the VND 70,000 billion is worth to shareholders.
Treat the 5% figure with care. It covers a single quarter, was presented by management at the meeting, and came before the quarterly financial statements were released. A contractor's margin moves with the mix of projects accepted in each quarter. Besides the operating-efficiency explanation the company offers, a high margin could also come from accepting several high-yielding work packages in the first quarter. The two explanations can only be told apart if a margin above 5% repeats over several quarters.
Factories, data centers, overseas: not necessarily higher margins
Coteccons also wants to change its mix of work. It expects non-residential construction to contribute about 50% of revenue in fiscal 2026–27, covering industrial building, infrastructure and specialized services. According to Võ Hoàng Lâm, a board member, factories alone contributed about 15% of revenue in fiscal 2025–26. The company is running six overseas projects, in Georgia and Taiwan (China), and is gradually moving into data centers.Tin nhanh Chứng khoán
The logic of this shift ties directly to collection. Owners of factories and foreign-funded projects tend to have steadier funding than domestic housing developers. Nguyễn Quang Thuân, founder of FiinGroup, told the meeting that Coteccons needs to be selective with customers to avoid a rise in bad receivables, in particular by diversifying toward foreign-invested clients.Tin nhanh Chứng khoán
Management itself, however, says the company does not assume the new segments carry higher margins, and instead assesses each project on technical requirements, execution capacity, client relationships and risk.Tin nhanh Chứng khoán For overseas markets, profit is not the focus in the early stage. The value of the shift therefore lies mainly in lower collection risk, not yet in higher margins.
A big book also needs big funding. Nguyễn Hồng Sơn, Deputy Chief Financial Officer of Coteccons, said that besides roughly VND 4,000 billion of short-term funding, the company has issued VND 1,400 billion of bonds and uses additional long-term bank loans.Tin nhanh Chứng khoán When capital is advanced to many projects at once, every month an owner pays late is another month the contractor carries the interest.
What is reported, and what is only a plan
By 2030, Coteccons targets revenue of VND 68,000 billion and ROE of 16–18% a year. That is a plan. What has numbers so far is only the first quarter: revenue of VND 11,270 billion, profit of VND 306 billion, cash collected of about VND 13,000 billion, and gross margin above 5% by management's account. The meeting also approved a 25% cash dividend for the past fiscal year.Tin nhanh Chứng khoán
CTD shares closed at VND 66,000 on October 20, up 4.43%. The gain coincided with the meeting, but the available data cannot isolate how much of it came from the information just disclosed.
For holders of CTD, the VND 70,000 billion backlog is settled fact. What remains open is how much real cash that work produces, and the test for the coming quarterly reports is clear. If gross margin holds above 5% and cash collected keeps pace with revenue for two consecutive quarters, the selectivity strategy is turning into profit, and the VND 1,050 billion net profit plan for this fiscal year stands on firm ground.Tin nhanh Chứng khoán If margin slides back to 3–4% while receivables keep growing with scale, the VND 70,000 billion is mostly workload rather than profit, and the provision for bad debts will be the first line to check.