

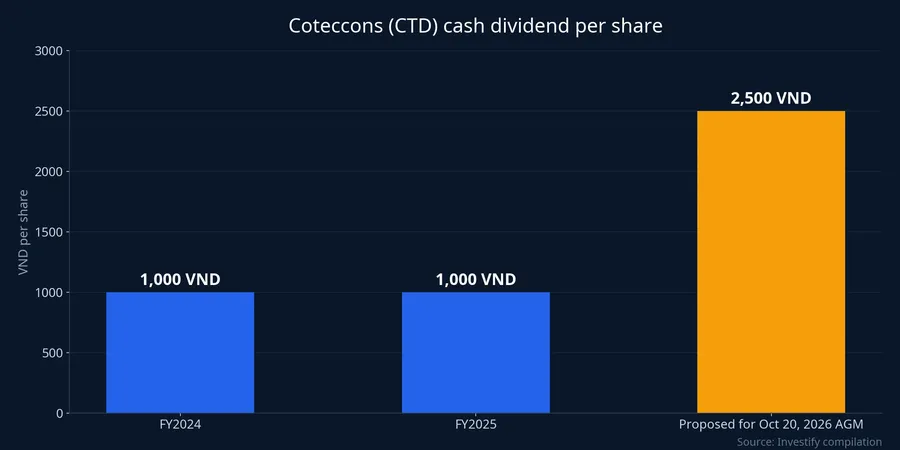
At the end of September, the annual shareholder meeting materials of Coteccons Construction JSC (CTD) carried a very short profit-distribution proposal: the board recommended no appropriation to funds and no dividend.CafeF Less than three weeks later, supplementary documents released ahead of the October 20 meeting changed course. Coteccons is now asking shareholders to approve a 25% cash dividend, or VND 2,500 per share, for a total payout of nearly VND 279.6 billion.Doanh nhân Pháp luật
For anyone holding CTD, this lands directly in the brokerage account. The October 20, 2025 meeting approved only a 10% dividend, or VND 1,000 per share.Mekong ASEAN This year's proposal is 2.5 times that. Using the numbers from the fiscal year that ended June 30, 2026, this article looks at the position Coteccons is paying from, what the meeting will decide, and which milestones remain before cash reaches shareholders.
What the October 20 meeting will vote on
The items that touch shareholders are the dividend, shares for employees and the business plan for the new fiscal year.
On the dividend, the 25% payout comes from retained earnings through June 30, 2026. With more than 111.8 million shares outstanding, the total is about VND 280 billion.Người Quan Sát Against net profit of VND 788 billion for the year just ended, the payout equals about 35.5% of earnings. At the October 16 close of VND 62,400, VND 2,500 is roughly 4% of the share price.
On employee shares, Coteccons proposes two alternatives at the same price of VND 10,000: selling 1,154,347 treasury shares, about 1.03% of shares outstanding, and issuing 1.5 million new shares, about 1.3%.Tin nhanh chứng khoán Both tranches carry a two-year transfer restriction from the end of the sale and could be carried out through the end of fiscal 2028 (June 30, 2028). The company says the aim is to retain key staff at the parent and its subsidiaries.
On the business plan for fiscal 2026–2027, the targets are revenue of VND 42,000 billion, up 22%, and net profit of VND 1,050 billion, up 34%.Tin nhanh chứng khoán If achieved, CafeF notes, it would be the first time in nine years that Coteccons returns to a trillion-dong profit.CafeF
The supplementary documents do not explain why the distribution plan moved from no dividend to 25%. The answer, if there is one, will come in the meeting's discussion and resolutions.
A record revenue year was also a year of near-doubled borrowing
In the fiscal year from July 1, 2025 to June 30, 2026, Coteccons reported consolidated net revenue of VND 34,340 billion, up 38%, and net profit of VND 788 billion, up 72.7%. Both beat plan, by 14.5% and 12.6% respectively.Doanh nhân Pháp luật
On the same balance sheet, debt grew faster than profit. Total borrowings and finance leases at June 30, 2026 stood at VND 5,943 billion, almost double the VND 2,987 billion a year earlier. Short-term bank loans accounted for VND 4,297.7 billion, with Techcombank, VietinBank and BIDV the three largest lenders. The company also has a VND 1,400 billion bond at a fixed 9% a year, maturing in early 2029.Doanh nhân Pháp luật
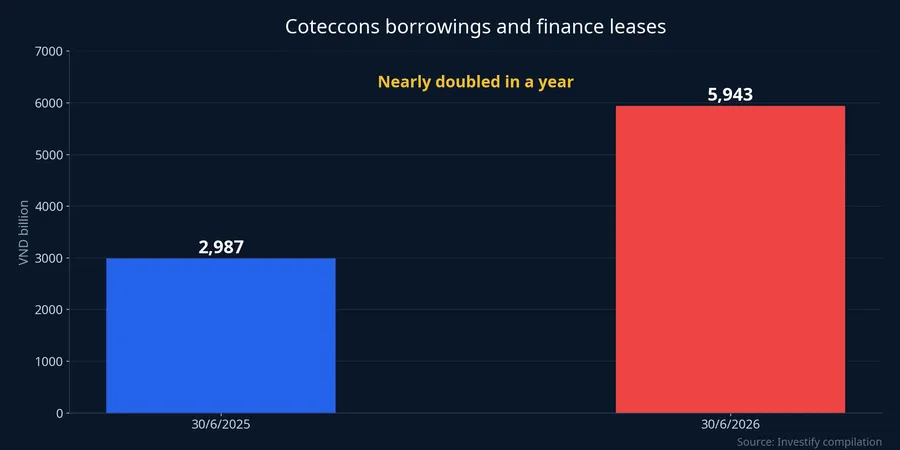
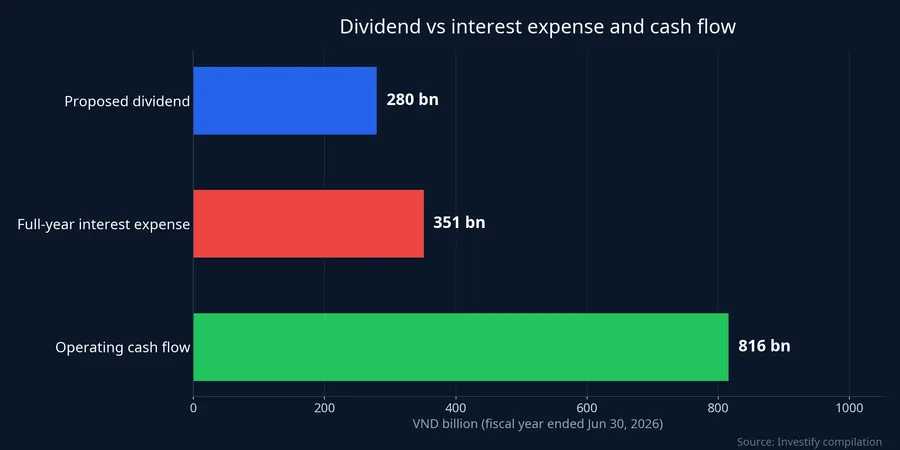
The cost of that debt is already in the income statement. Full-year interest expense reached VND 350.97 billion, up 145.6%. In the final quarter of the fiscal year alone, interest expense rose from VND 39.3 billion to VND 135.3 billion year on year.Doanh nhân Pháp luật One quarter of interest is already close to half the proposed dividend payout. If debt stays near its year-end level, interest expense in the new fiscal year is unlikely to be lower than last year's.
Why does a contractor borrow this much? The report shows cash sitting on construction sites. Inventories rose 66% to VND 9,905.8 billion, mostly work in progress, meaning work already built but not yet accepted by project owners. Short-term receivables stand at VND 16,544.2 billion.Doanh nhân Pháp luật Revenue up 38% means Coteccons had to front more materials and labor, and part of that was funded by short-term borrowing. That is the most common explanation for contractor debt, though the report does not break out how much borrowing went into each project.
Where the payout money comes from
Set against the figures above, the roughly VND 280 billion payout can be viewed through cash, cash flow and the risks the report itself flags.
On cash, cash and deposits at June 30, 2026 were VND 7,823 billion, about VND 1,880 billion more than total borrowings.Doanh nhân Pháp luật The dividend would take about 3.6% of that. A contractor's cash is not entirely free cash: part comes from customer advances, and part may be pledged as collateral for performance guarantees. The report cited does not separate these.
On cash flow, this is the biggest change of the year. Net operating cash flow was positive VND 815.8 billion according to Doanh nhân Pháp luật. CafeF reports VND 829 billion, after negative VND 1,153 billion in the prior fiscal year.CafeF The two sources differ by about VND 13 billion but point the same way: after a deeply negative year, construction operations generated more cash than the proposed dividend. This is the strongest basis for the 25% payout.
On risk, bad debt stands at VND 1,835.2 billion with provisions of VND 1,315.1 billion, leaving roughly VND 520 billion unprovisioned. The two largest items, tied to projects of Ngôi Sao Việt Real Estate Investment and Minh Việt Investment, were provisioned almost in full, according to the outlet.Doanh nhân Pháp luật The remainder could weigh on future profits if it cannot be recovered.
Read together, the data point to a fairly clear conclusion: Coteccons has enough cash to pay about VND 280 billion without borrowing more, and last year was the year operating cash flow could cover that payout. What is uncertain is next year. A VND 42,000 billion revenue plan demands even more working capital while interest expense is already rising quarter by quarter. The 25% payout reflects a year of strong cash flow, not proof that it will be repeated.
How much the holder's ownership changes
If both employee share alternatives are approved and sold in full, a total of 2,654,347 shares would be issued at VND 10,000. Against more than 111.8 million shares outstanding, the share count rises about 2.37%. A holder of 1% of the company would be left with about 0.977%.
That dilution is small. The sale price deserves more attention. Against the October 16 share price of VND 62,400, VND 10,000 is about 84% lower. Across all 2.65 million shares, the gap between market and sale price comes to roughly VND 139 billion, nearly half the dividend. That is value moving from existing shareholders to employees in exchange for a two-year commitment. The actual figure depends on the share price at the time of sale and the number of shares actually sold. The two sales can run to June 30, 2028, so dilution may arrive in stages rather than all at once.
Milestones before cash reaches the account
The dividend is for now only a proposal. Cash arrives only after the meeting approves it, the board announces the record date and the payment date comes.
The list of shareholders attending the meeting was fixed at the record date of September 18, 2026;Doanh nhân Pháp luật the right to the dividend is a separate list, fixed later. The record date for the dividend has not been announced. For reference, last year, after the October 20, 2025 meeting, Coteccons fixed the list on December 2 and paid on December 22, 2025.Mekong ASEAN This year's schedule need not match.
The ex-dividend date usually falls one trading session before the record date. From that session, CTD's reference price is cut by VND 2,500, and buyers from that session no longer receive this dividend. Holders on the record-date list receive cash on the payment date stated in the notice.
Conclusion
Coteccons is proposing a payout that last year's cash flow can carry: about VND 280 billion, below the more than VND 800 billion of operating cash flow and a small slice of the VND 7,823 billion in cash and deposits. The price of a growth year sits on the debt side: borrowings nearly doubled, and interest expense in the latest quarter alone reached VND 135.3 billion.
The October 20 resolution will show whether the 25% payout stands, and the record-date notice that follows will show when the cash arrives. After that, the two indicators to watch are operating cash flow and outstanding debt in the new fiscal year's quarterly reports. If cash flow stays positive while borrowing stops rising, the 25% payout has a base to repeat. If cash flow turns negative while debt keeps climbing, this year will more likely prove a one-off high payout.