
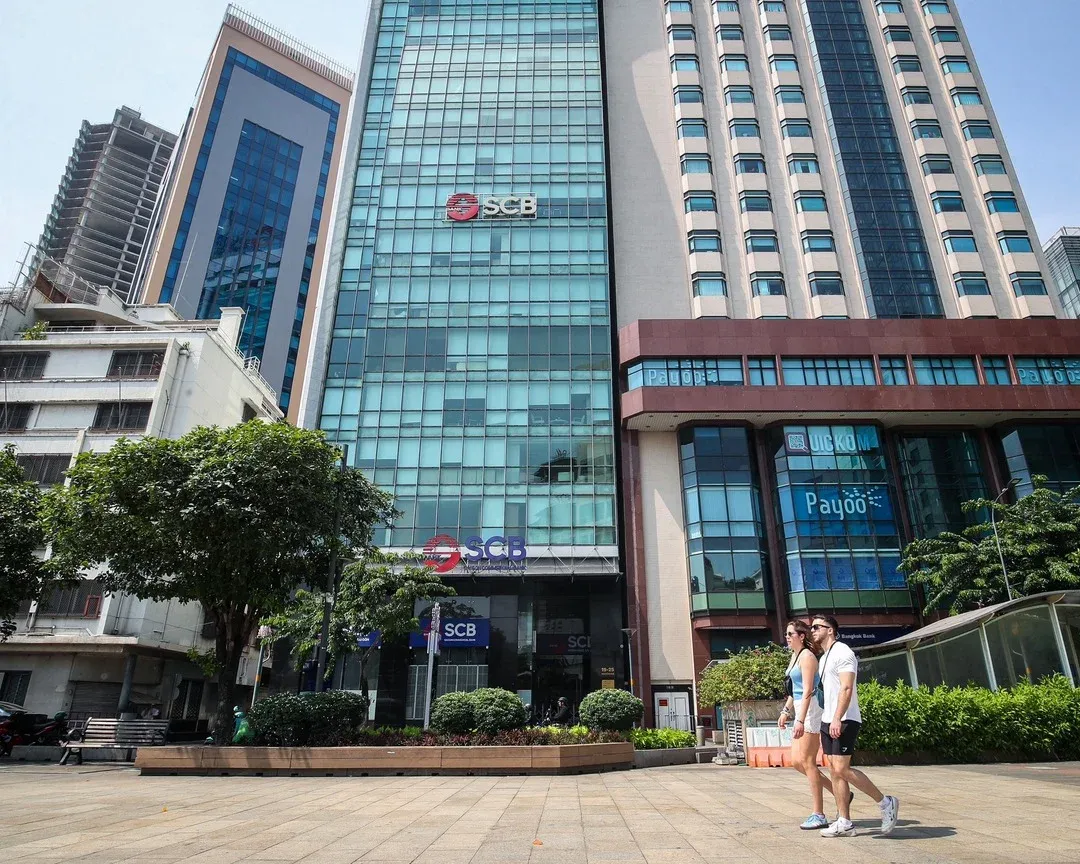
Saigon Joint Stock Commercial Bank (SCB) shut two branches, in Ho Chi Minh City and Dong Nai, during the week of October 5–9, and will close two more during October 12–16. According to VnExpress and Znews on October 11, its network is now just 10 branches, in Ho Chi Minh City, Hanoi, Da Nang, Gia Lai, Lam Dong and Vinh Long.VnExpressZnews
Taken alone, these are two more closure notices. Set against the four years since SCB was placed under special control, they show where the bank now stands. The network has shrunk fastest since mid-July 2026, while the job the bank itself calls a priority has moved to disposing of collateral to recover debt.
2022: A Starting Point of Nearly 240 Outlets
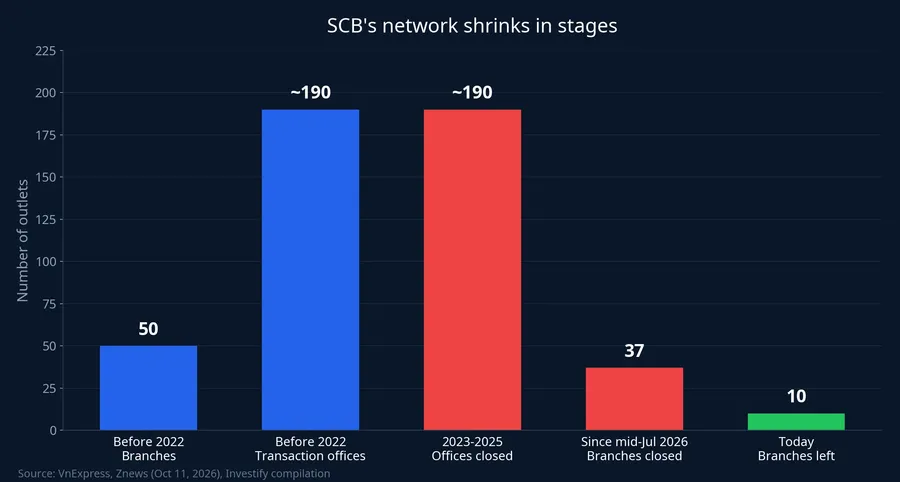
Before the State Bank of Vietnam placed it under special control in October 2022, SCB had nearly 240 outlets: 50 branches and about 190 transaction offices across 28 provinces and cities, by the administrative map before the mergers.VnExpress Ho Chi Minh City alone once had 16 branches and 100 transaction offices.
SCB is the bank tied to the Van Thinh Phat case. This article does not retrace the case. It follows only what has happened to the network and to the bank's own work.
2023–2025: Transaction Offices Go First
The first stage of the retreat happened at the smallest level. Over the three years 2023–2025, SCB closed nearly 190 transaction offices nationwide.VnExpress Almost the entire layer disappeared while most branches stayed open.
The two types of outlet matter differently to customers. A branch is a dependent unit of the bank that can handle many functions, such as taking deposits, lending and payments. A transaction office is smaller and is managed by a branch. Closing an office removes a place to serve customers. Closing a branch removes the whole local operation.
Since Mid-July 2026: Branches Are Next
The second stage began in mid-July 2026, and the pace changed completely. Since then, 37 branches have stopped operating, and in August alone the bank announced the closure of 13.Znews The earlier stage took about three years to close nearly 190 offices. This one took about three months to close 37 branches, taking the count from 50 down to 10.
Why did the pace of branch closures jump from mid-July? In the October 11 reports, neither SCB nor the State Bank gave a specific reason for the new pace. The outlets only placed it within the broader restructuring under the State Bank's supervision. This article therefore does not assign it a specific cause.
After closing, SCB announced it would liquidate many assets of the branches and offices that had ceased operating.VnExpress
September 15 and October 5–9: Headquarters Moves, Network Down to 6 Localities
On September 15, 2026, SCB's head office moved from 19-21-23-25 Nguyen Hue to 242 Cong Quynh, Ben Thanh Ward, Ho Chi Minh City.CafeF The building on the Nguyen Hue pedestrian street had long been the bank's visual identity.
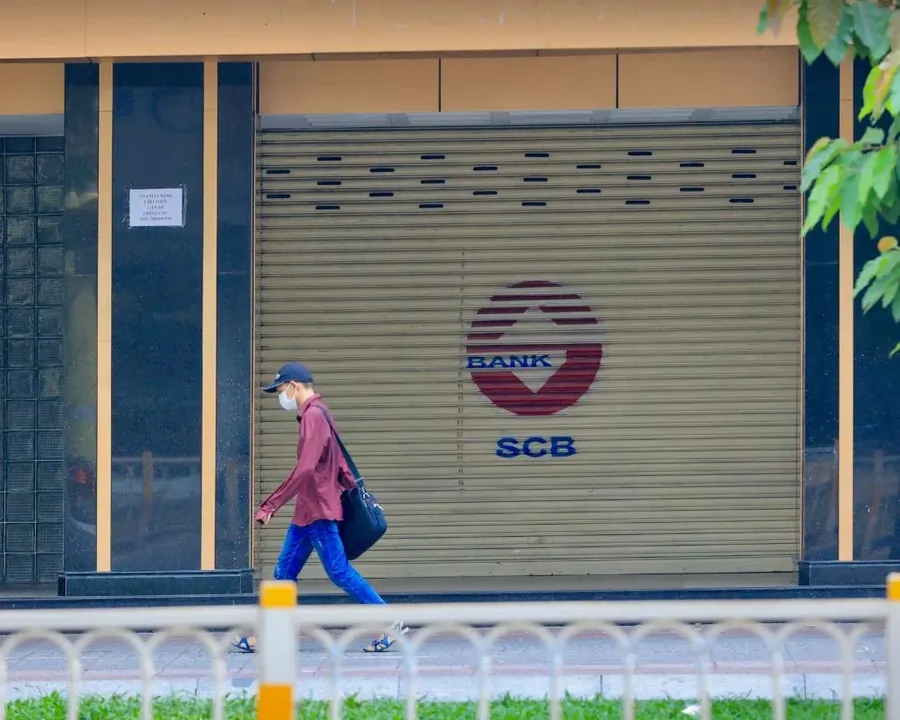
Three weeks later, the two branches in Ho Chi Minh City and Dong Nai closed, and two more are due to close during October 12–16. The names of these four branches, and where their customers will be moved, have not appeared in the reports checked. That information will be in SCB's own notices.
One discrepancy needs flagging. A report by Nguoi Dua Tin, republished by CafeF the same day, says SCB has 12 outlets in 7 localities, adding Tay Ninh, and will close only one more branch next week.CafeF This article uses the VnExpress and Znews figures: 10 branches in 6 localities, with two more closing. Anyone banking in Tay Ninh should check directly against the bank's notices.
The Main Job Has Changed: Disposing of 1,120 Collateral Assets
While the network shrinks, SCB says its core work lies elsewhere. In a bulletin posted on its website in mid-September, the bank called disposing of collateral to recover debt one of its top priority tasks.CafeF
According to that bulletin, SCB has set up an independent management unit, reviewed and standardized its data, and sent more than 7,200 documents to the authorities to establish management and disposal rights over 1,120 assets.VnExpress The bank splits the disposal into two stages. The first is choosing an advisory firm to survey, set criteria, run the tender and assess bids. The second is choosing a firm able to value the assets and hold public auctions. For high-value assets or those with complex legal issues, SCB says it is finalizing procedures under the guidance and supervision of the State Bank and the Special Control Board.
In other words, most of the work is still at the paperwork and contractor-selection stage. From the sources cited, it is not possible to tell how many of the 1,120 assets have been valued or put up for auction.
The government has also named the task. Resolution 262/NQ-CP, on the regular August cabinet meeting and issued on September 5, 2026, asks the State Bank to step up supervision, implement the plan for weak credit institutions under special control effectively, and coordinate with the relevant units to speed up the disposal of SCB's collateral.Znews In the press coverage cited, the resolution sets no separate deadline for SCB.
What the Reports Leave Out: Where Depositors and Borrowers Stand
For people with money at SCB, two changes are already visible.
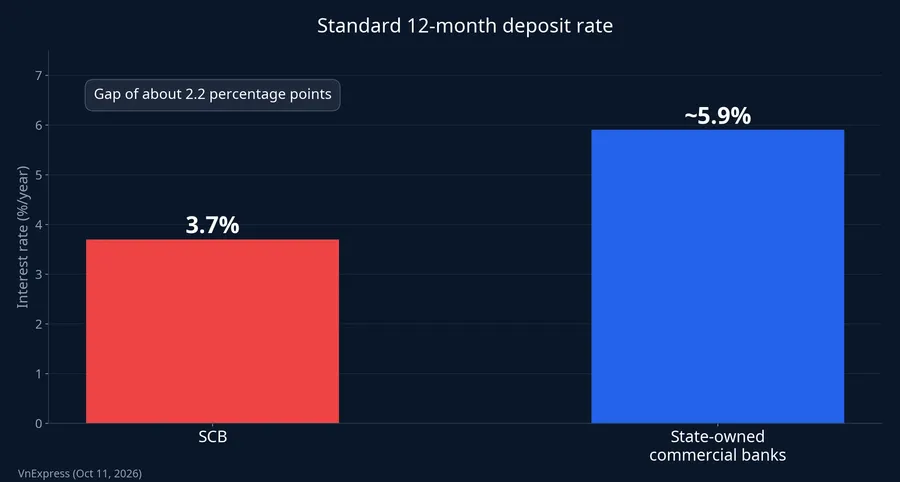
The first is the interest rate. SCB lists its standard 12-month deposit rate at 3.7% a year, about 2.2 percentage points below the published schedules of state-owned commercial banks.VnExpress
The second is the distance to a counter. With 10 branches in 6 localities, depositors in provinces with no branch left must transact elsewhere or move online. Each closure notice will say where that branch's customers are being transferred.
For borrowers, SCB's average lending rate on loans originated in September was 5.35% a year.VnExpress Anyone with property, vehicles or machinery pledged to SCB should understand that collateral is the area the bank is putting the most effort into. And anyone thinking of buying assets SCB puts up for auction will meet lots that go through the two-stage process above: choose a valuer, then hold a public auction.
What Is Not Yet Known and What to Watch
SCB's final resolution plan has not been announced, and this article does not speculate on what it will be. SCB's status remains that of a bank under special control, shrinking its network and handling assets under State Bank supervision.
Put the stages side by side and the trajectory is clear: from a retail bank present in 28 provinces and cities, SCB is becoming a small operation in a few locations, with most of its effort going into debt recovery. For depositors, what is certain is lower interest than the market and fewer branches. What is uncertain is the bank's own destination.
Two signals are worth watching in the short term. The first is SCB's notice on the two branches closing during October 12–16, which will show which areas lose their branches next and where customers are transferred. The second is further bulletins on the 1,120 assets: once SCB announces that valuers and auctioneers have been selected, debt recovery will move from paperwork to real sales at scale.