
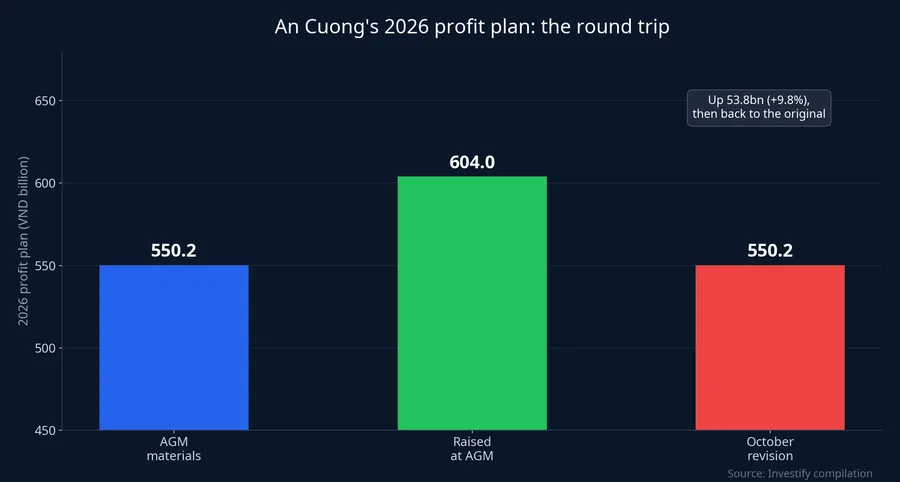
An Cuong Wood (ACG, HoSE) has just brought its 2026 profit plan back to where it started. According to Tin nhanh Chứng khoán, the company revised full-year net profit down to VND 550.2 billion, 8.9% below the VND 604 billion approved by shareholders at the annual general meeting. Planned net revenue fell 9.2%, from VND 5,300 billion to VND 4,811.9 billion.Tin nhanh Chứng khoán
What sets this apart from an ordinary guidance cut is that neither new figure is new. Viet Times reports that VND 4,811.9 billion in revenue and VND 550.2 billion in profit are exactly the targets An Cuong had written into its 2026 AGM materials.Viet Times One number made a full lap of the year and came back to the same spot. This post retraces each stage of that lap, then names the data point that will show whether the current level holds.
The cautious figure in the AGM materials
When it drafted the AGM materials, An Cuong set its profit plan at VND 550.2 billion. Management later explained the caution at the meeting: "When we built the 2026 plan, the global geopolitical situation was pretty bad."Viet Times In other words, the company itself describes the VND 550.2 billion figure as written under unfavorable conditions. Keep that in mind for the stages that follow.
A strong first quarter and a higher target
Q1 2026 gave An Cuong reason for optimism. Net revenue came to VND 1,109.93 billion, up 38.39% year on year, and net profit reached VND 111.07 billion, up 30.65%.
At the AGM, management said the company had been "dizzyingly busy" in the first four months and that Q1 growth was "higher than expected," so targets were reset to VND 5,300 billion in revenue and VND 604 billion in profit.Viet Times That raised the bar roughly 10% above the materials sent to shareholders earlier.
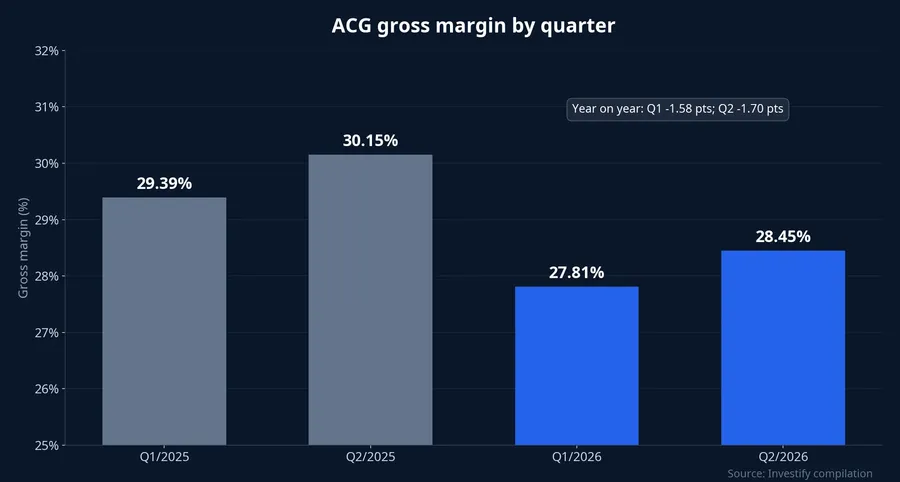
One detail was easy to miss even in Q1. Profit rose 30.65%, but gross margin had already slipped from 29.39% to 27.81%. The company sold more, yet each dong of revenue left less gross profit. The decision to raise the plan rested on volume while the margin signal pointed the other way.
Q2: revenue up, profit down
By Q2 the two lines clearly diverged. Net revenue still grew 28.97% to VND 1,239.48 billion, but net profit fell 5.32% year on year to VND 130.59 billion. Gross margin in Q2 was 28.45%, below the 30.15% of the same quarter last year.
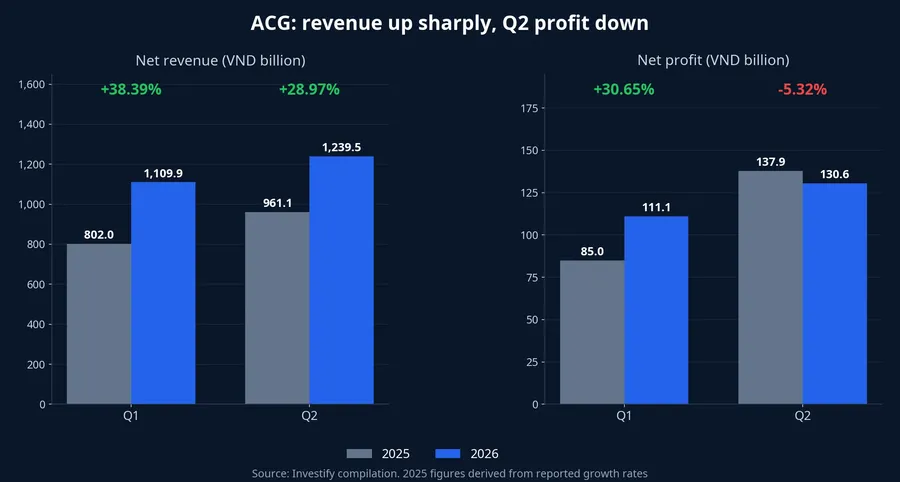
For the first half, An Cuong reported revenue of VND 2,349.4 billion, up 33.3%, and net profit of VND 241.66 billion, up 8.4%. Measured against the VND 604 billion plan, that is only 40% completed after six months. Half-year gross margin slipped from 29.8% to 28.1%.Tin nhanh Chứng khoán
Revenue up 33%, profit up 8%: where did the gap go?
The gap can be split into two layers. The first is gross margin. From first-half figures, gross profit is roughly VND 661 billion against roughly VND 525 billion a year earlier, an increase of about 26%. A thinner margin pulled growth down from 33% at the revenue line to about 26% at gross profit.
The second layer sits below gross profit: selling expenses, administrative costs, financial costs and provisions. Going from about 26% at gross profit to 8.4% at net profit, most of the gap lies here. Gross margin explains only part of the picture; the larger share comes from costs that come with a bigger revenue base.
Bad debts tied to the Hung Thinh group are often mentioned in this context. As of June 30, 2026, An Cuong had provisioned VND 97.6 billion against VND 109.7 billion of trade receivables, of which Hung Thinh Furniture JSC alone accounted for VND 77.8 billion, with VND 74.08 billion provisioned.Tin nhanh Chứng khoán These are cumulative balances at the reporting date, not an expense incurred in the six months alone. The available sources do not isolate the additional provisioning made during the period, so the hit to first-half profit cannot be measured. What is more certain is that the Hung Thinh receivable is almost fully provisioned, leaving only about VND 3.7 billion of exposure on the books.
So the Hung Thinh debt is unlikely to be the main explanation for slower profit growth. A thinner gross margin and higher operating costs are the two forces with clearer data behind them.
Back to VND 550.2 billion, with no reason given
An Cuong recently announced a revised plan that puts revenue and profit back at the levels in the AGM materials. According to Tin nhanh Chứng khoán, the company did not disclose a reason.Tin nhanh Chứng khoán Any explanation of the cause is therefore inference from the numbers.
The numbers show that the VND 604 billion plan was raised on Q1 momentum, and that Q2 did not sustain it. Returning to its own earlier figure, rather than setting a wholly new one, suggests the company treats the AGM increase as the upside portion and the original number as the level it believes it can reach. That is a reading of the company's action, not an explanation the company gave.
How much the second half needs
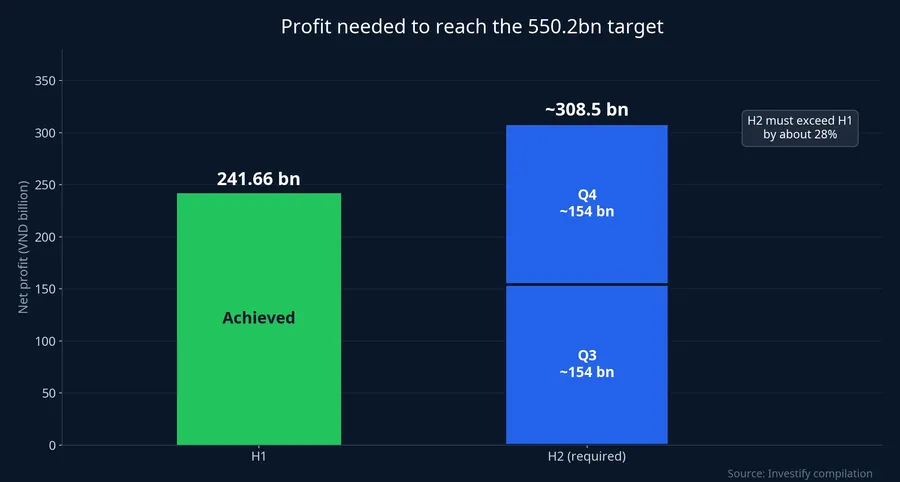
At the new level, An Cuong needs about VND 308.5 billion of net profit in the second half (550.2 billion less the 241.66 billion already booked). That is about 28% above first-half profit. Split evenly across two quarters, each needs about VND 154 billion, while the best quarter this year was Q2 at VND 130.59 billion. Even the lowered target requires both Q3 and Q4 to be the strongest quarters of the year.
So the cut does not mean the pressure has gone away. A plan that is 8.9% lower means the earnings per share the company itself is aiming for is lower by the same proportion, assuming the share count is unchanged. Profit is also the source of dividends. The latest dividend An Cuong paid was VND 1,000 per share, settled on September 30, 2026, and it belongs to fiscal year 2025. The dividend for 2026 will depend on this year's profit.
The share price has partly absorbed the slowdown. From February 23 to the October 9 session, ACG fell 16.9%, from VND 35,840 to VND 29,800.Tin nhanh Chứng khoán Liquidity is very thin: only 2,100 shares changed hands on October 9. At that volume, the daily price is a poor gauge of how the market values the company.
The Q3 report: the first data point to test the plan
Based on the usual disclosure deadline, the Q3 2026 financial statements should appear around October 20. They are the first data that will show how close VND 550.2 billion is to reality, and two metrics need to be read side by side.
The first is Q3 net profit against the roughly VND 154 billion per quarter benchmark. If Q3 profit lands around or above it, the lowered plan has a credible path to completion. If Q3 stays in the VND 110-130 billion range of the first two quarters, Q4 has to carry the largest share of the year, and the VND 550.2 billion target then rests almost entirely on a single quarter.
The second is gross margin. If it returns to the 29-30% range of last year, revenue growth will convert into proportionate profit growth. If it stays around 28% or lower, the company is selling more to hold profit steady, something revenue figures alone do not reveal.
The thesis here is that the VND 604 billion plan rested on a strong Q1, and that momentum did not carry into Q2. VND 550.2 billion still requires a second half better than the first. That conclusion would change only if Q3 profit clears VND 154 billion with a recovering gross margin. The Q3 report will show whether this number's lap ends here or whether another revision is still to come.