
On the morning of September 24, shareholders of Masan High-Tech Materials (MSR) woke up to news that The Elmet Group, a NASDAQ-listed tungsten producer, will buy 4.99% of MSR for USD 124.75 million. The price implies an equity valuation of USD 2.5 billion for the whole company.CafeF That USD 2.5 billion figure is the one you will hear most over the coming days.
Look at how the deal is built, though, and the equity is only half of it. The other half is an agreement for MSR to supply tungsten mined at Nui Phao, in Thai Nguyen province, and to provide tungsten conversion services to Elmet for more than eight years. To read this deal properly, start with the buyer: what Elmet needs, and why it is sourcing it from Vietnam.
Elmet needs tungsten that is already flowing
Elmet describes itself as the only US-owned, vertically integrated tungsten producer, with facilities in Maine, Michigan and Ohio. It listed on NASDAQ in early 2026.CafeF Tungsten is prized for its heat and wear resistance, and it goes into semiconductors, aerospace, energy and defense.
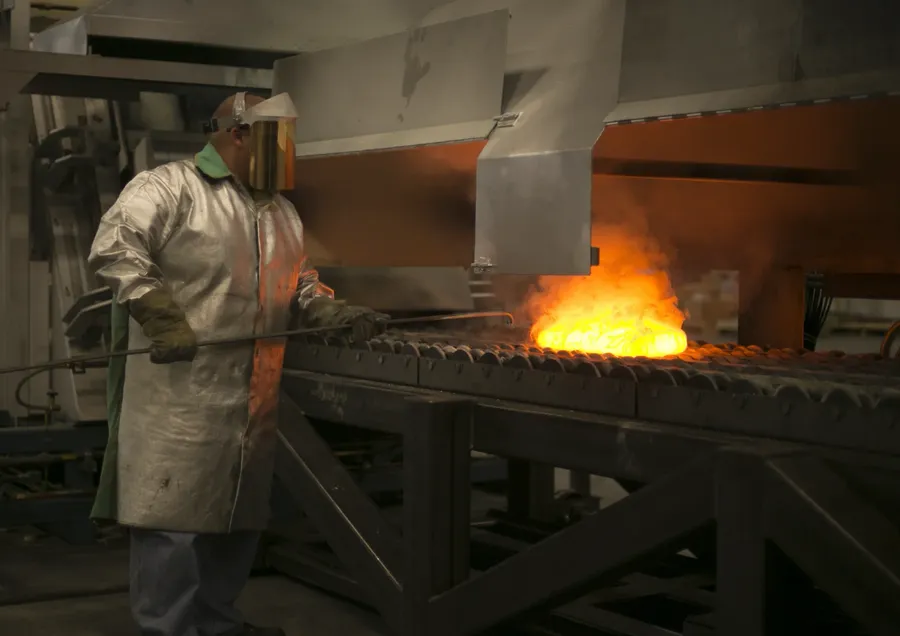 *Photo: The Elmet Group*
About ten days before the MSR announcement, Elmet lined up two large commitments on the US side. According to CafeF, citing Reuters, the company plans to use a committed USD 450 million investment to expand its domestic plants and develop raw material sources in allied countries. Separately, Elmet holds a contract to supply tungsten to the US Defense Logistics Agency for the national stockpile, worth up to about USD 2 billion.CafeF
Once the money is committed, the metal has to be delivered. Most of the world's mined and refined tungsten comes from China, which has placed the metal under export controls. And some of the new capacity Elmet is building in the US will not come online until 2027-2028.CafeF To bridge that gap, it needs a source that is operating today, sits outside China, and already knows how to work with it.
Nui Phao ticks every box. It is the largest operating tungsten mine outside ChinaCafeF, and MSR has been selling tungsten to Elmet for more than 12 years.CafeF
The supply contract is the core of the deal
According to MSR's announcement, the two sides committed to roughly 1,250 tonnes of WO₃ equivalent a year for more than eight years, with estimated gross revenue of about USD 1.5 billion over the initial term, at current tungsten prices.CafeF Because it is pegged to today's prices, the roughly USD 1.5 billion is an estimate, not a fixed sum.
Spread evenly over eight years, that works out to about USD 187 million a year. MSR's full-year 2026 plan calls for revenue of about USD 1.4 billion and net profit of about USD 233 million.CafeF So the Elmet revenue amounts to roughly 13% of the annual plan.
In other words, this contract does not transform MSR's top line. Its value lies in having a committed buyer for part of the output over many years. That gives the company better revenue visibility and lets it run its processing plant at a steadier utilization rate.
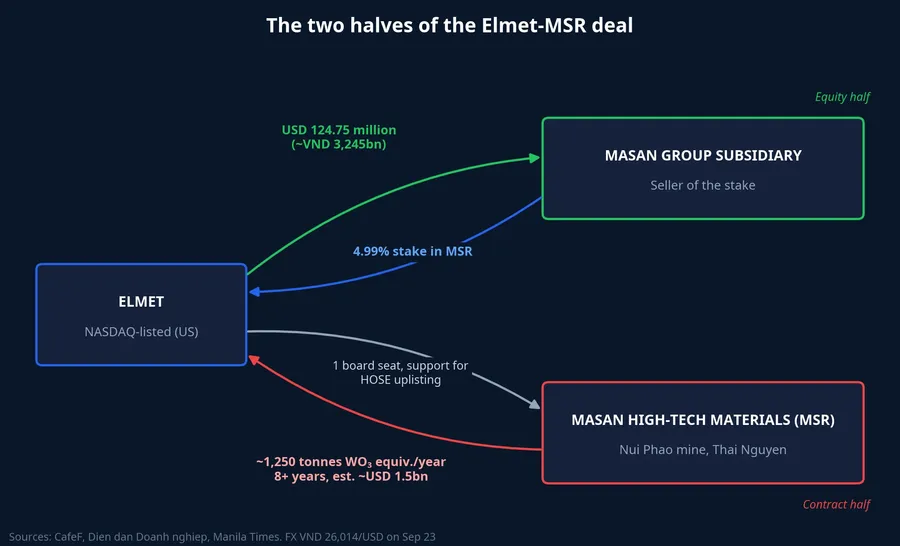
Next to the contract, the USD 124.75 million paid for the stake is small. Elmet is not buying 4.99% to run anything, either. In return, it gets one seat on MSR's board and will support MSR's planned uplisting to the Ho Chi Minh Stock Exchange (HOSE).Manila Times The stake works more like a tie that binds the two companies than a pure financial investment. As a shareholder with a board seat, Elmet has a direct interest in keeping the supply relationship going.
The sale proceeds go to Masan, not MSR
This is the detail most easily missed. Elmet is buying the 4.99% from a wholly owned subsidiary of Masan Group.Diễn đàn Doanh nghiệp It is a transfer of existing shares; MSR is not issuing new stock.
That means the USD 124.75 million, about VND 3,245 billion at the September 23 rate of VND 26,014 per dollar, flows to Masan rather than into MSR's coffers. What MSR gains is the contract, a board member and a strategic US shareholder. What Masan Group (MSN) gains is cash from selling part of its stake above the market price. MSN closed at VND 69,800 on September 23.
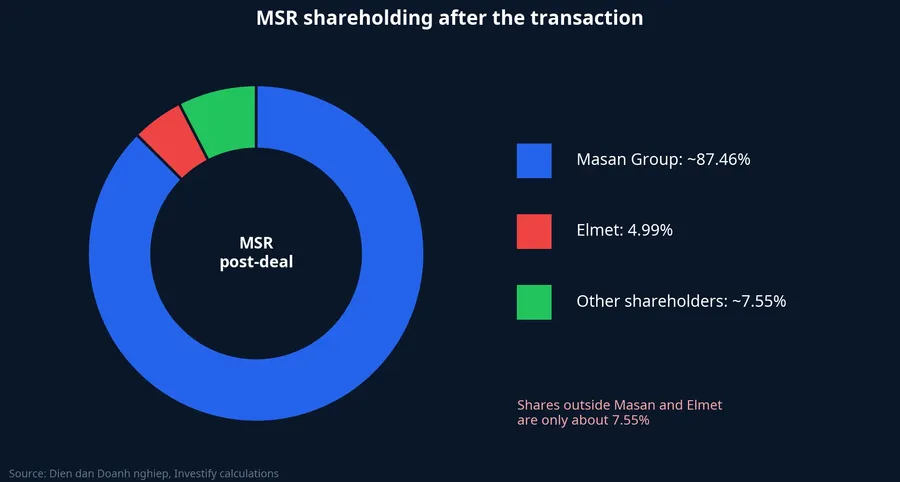
After the transaction, Masan Group remains the controlling shareholder with about 87.46%.Diễn đàn Doanh nghiệp The deal has not closed yet. Completion is subject to regulatory and corporate approvals, the commercial agreements only take effect once it closes, and both sides are targeting completion in the first half of October.CafeF
What USD 2.5 billion means per share
MSR has 1,099,829,520 shares outstanding. Dividing USD 2.5 billion by that count gives about USD 2.27 per share, or roughly VND 59,100 at VND 26,014 per dollar. MSR closed at VND 53,500 on September 23, so the deal price sits about 10.5% above the market.
Two caveats apply to that figure of about VND 59,100. First, it is derived from the total deal value; the parties have not disclosed a per-share price. Second, it is the price of a strategic transaction bundled with a multi-year supply agreement, so the buyer is paying extra for a long-term relationship, a board seat and secure supply. It is not a target price for the listed shares, and nothing guarantees the market will converge on it.
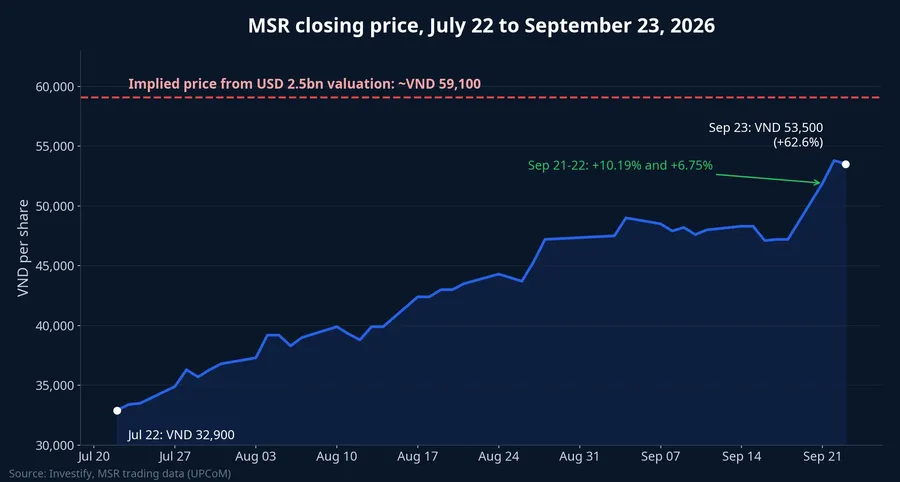
The 10.5% gap is also small next to the distance the stock has already traveled. MSR closed at VND 32,900 on July 22 and had gained about 62.6% by September 23. In the two sessions of September 21 and 22 alone, it rose 10.19% and then 6.75%, from VND 47,200 to VND 53,800, before the Elmet news came out.
Several drivers overlapped in that run: first-half earnings, the news in mid-September that Elmet had secured US funding, and MSR's September 22 notice seeking shareholder approval. The available data cannot separate how much each contributed. What is visible is that the market had already priced in expectations around the tungsten story before this morning.
The business behind the deal
The first half of 2026 marked a clear turnaround for MSR. Net revenue reached VND 11,131 billion, up 270.2% year on year. Net profit came in at VND 2,202.3 billion, against a loss of VND 216.4 billion a year earlier. MSR attributes the result to higher sales volumes, sustained high realized tungsten prices and better operating efficiency. The company has also announced its first-ever dividend, worth VND 1,100 billion in total.CafeF
What stands out in the financial statements is the other side of the picture. Operating cash flow for the half was only VND 448.8 billion, about a fifth of reported profit, because cash was tied up in inventory. Inventory reached VND 8,726 billion at June 30, up from VND 2,881 billion a year earlier. Net debt remained at VND 10,856 billion, and six-month interest expense was VND 546.9 billion.
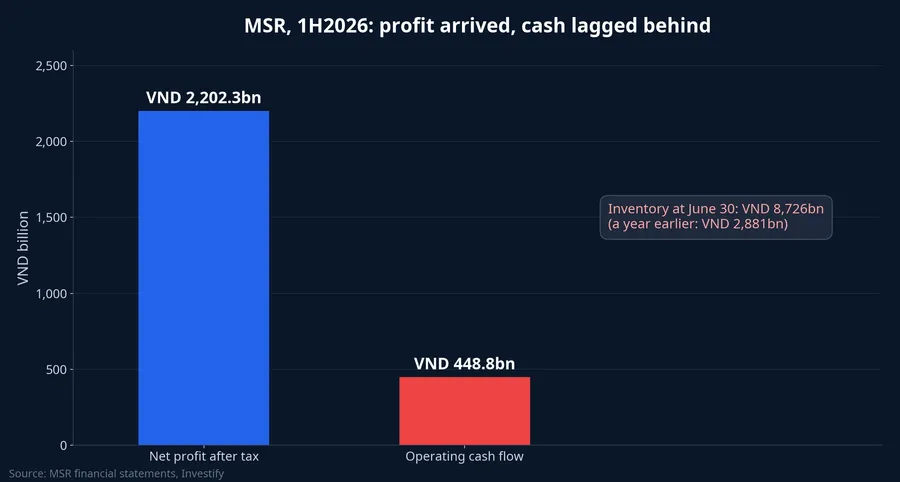
Put simply, the profits have arrived but the cash has not kept pace. A long-term offtake agreement may help MSR turn its inventory more steadily, but that is something the coming quarters will have to confirm.
Risks that sit outside the deal
Tungsten prices drive most of the story. MSR's first-half profit leaned heavily on high selling prices, and even the roughly USD 1.5 billion value of the Elmet contract is calculated at current prices. The detailed pricing terms, such as whether prices are fixed or float with the market, have not been disclosed. A long-term contract locks in volume, but not necessarily price.
The free float is very thin. After the deal, Masan holds about 87.46% and Elmet 4.99%, leaving only about 7.55% for all other shareholders. With so few freely tradable shares, modest flows can move the price a long way in either direction. On September 23, only 1,579,200 MSR shares changed hands, thin liquidity for a company worth about VND 59,000 billion.
The profit track record is short. Just a year ago MSR was reporting losses. The first half of 2026 was a strong period within a favorable price cycle, not proof that the company can stay profitable through both the upswing and the downswing of tungsten prices.
Milestones to watch
Taken together, this deal improves the quality of MSR's sales more than their scale: a long-standing US customer now takes an equity stake and a board seat, and commits to buying part of the output for more than eight years. The USD 2.5 billion valuation is, as Masan describes it, an independent reference point for MSR's value, but the cash from the transaction belongs to Masan. That reading only changes if the contract's pricing mechanism turns out to be unfavorable, or if the deal fails to close.
Today, the good news could make MSR and MSN volatile, especially MSR given its thin float. A single session's price reaction says more about market sentiment than about the value of the deal. Signals worth tracking over the next few months:
- Deal completion in the first half of October, since the commercial agreements only take effect then.
- The contract's pricing mechanism, if more details are disclosed. Market-linked pricing means the contract mainly secures volume; a price floor or fixed price would shield MSR from part of the cycle.
- Q3 financial statements, to see whether operating cash flow has caught up with profit.
- Progress on the HOSE uplisting, which could improve liquidity.
Vietnamese tungsten is now being valued not just on commodity prices but on its place in the US supply chain. For individual investors, though, the geopolitical story still has to pass through some very ordinary numbers: the tungsten price, cash flow and the free float.