
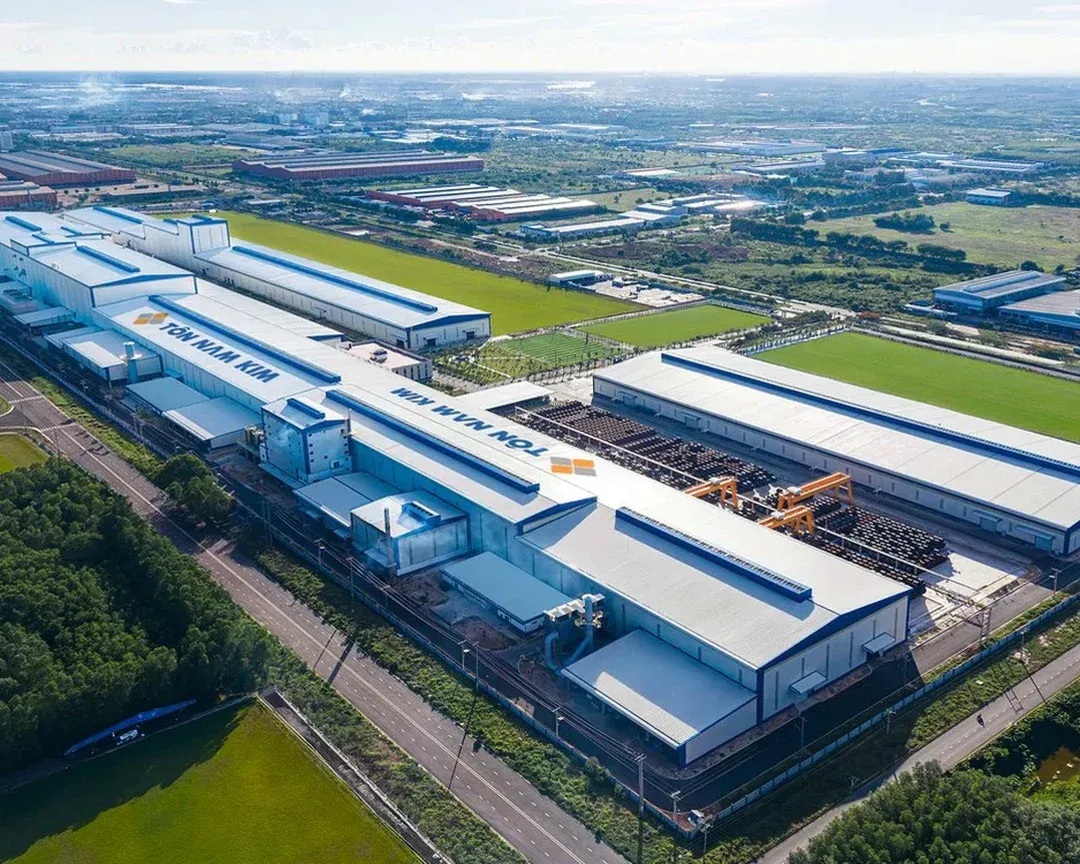
On November 21, Nam Kim Steel Joint Stock Company (NKG, listed on HoSE) opened its Nam Kim Phu My coated-steel plant in the My Xuan B1 - Dai Duong Industrial Park, Ho Chi Minh City. The plant carries total investment of about VND 6,200 billion, covers 32.2 hectares and has a design capacity of 1.2 million tonnes a year.CafeF With Phu My running, the design capacity of Nam Kim's six plants rises to more than 2.2 million tonnes a year, so roughly half of the company's production capability now sits in a plant that has just been opened.
The current numbers are solid. In Q3 2026, net revenue was above VND 5,472 billion, up 45% year on year, and pre-tax profit was above VND 185 billion, up 214.4%.CafeF What matters from here is that the VND 6,200 billion has been spent. It earns a return only if Nam Kim sells the steel this plant turns out.
What Phu My adds to Nam Kim
Nam Kim has long been known for galvanized, aluminum-zinc alloy-coated and color-coated steel sheet. Phu My is designed as an integrated chain, from processing hot-rolled steel through cold rolling and annealing to coating and painting.Tạp chí Tài chính The main lines are continuous pickling and cold rolling at 1.2 million tonnes a year, metallic coating at 500,000 tonnes, continuous annealing at 400,000 tonnes and color coating at 150,000 tonnes.CafeF
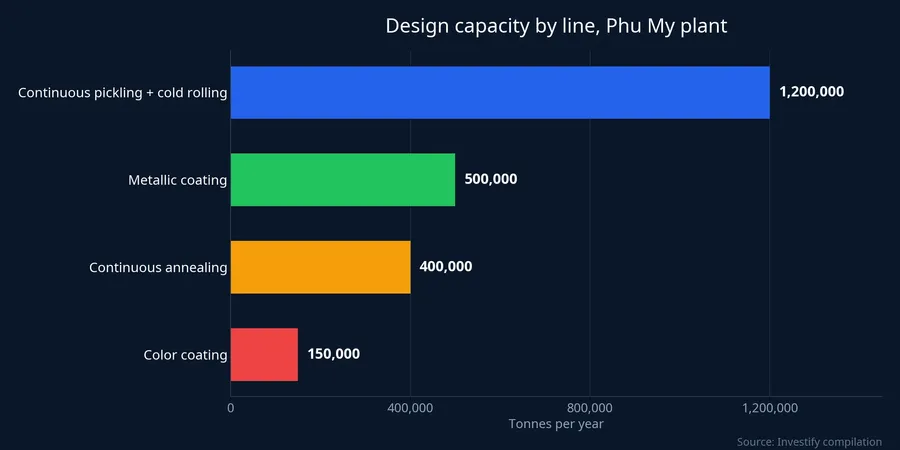
Side by side, the 1.2 million tonnes is the cold-rolling stage, far larger than the coating stage. Phu My therefore does more than add coated sheet: it moves Nam Kim into higher-spec products. At the opening, the company presented three new products: annealed cold-rolled coil (CR Annealed), zero-spangle galvanized steel (GI Zero Spangle) and PPGL AZ200 25/12 color-coated steel.Tạp chí Tài chính The plant also targets electrical steel and products for machinery, electrical equipment, appliances and autos.CafeF
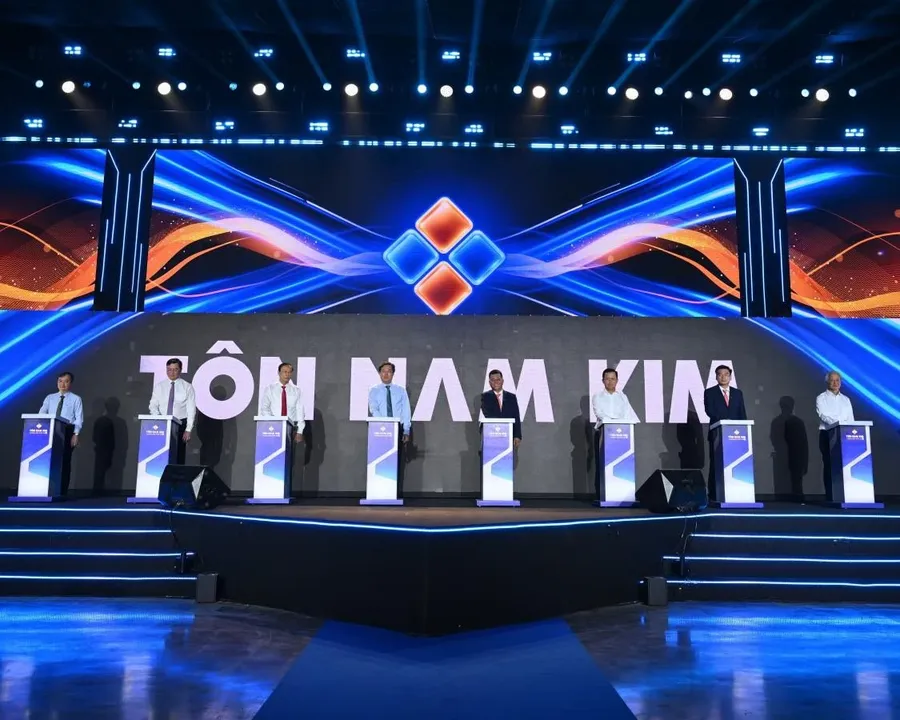
Mr. Ho Minh Quang, Chairman of the Board of Nam Kim Steel Joint Stock Company (NKG), called the investment a strategic step to develop high-spec products and compete better in international markets.CafeF Product from Phu My had reached customers before the ribbon-cutting: annealed cold-rolled steel has shipped to Brazil since August, and in early November Nam Kim exported nearly 20,000 tonnes of steel to the US.CafeF Mirae Asset's Q3 update on November 4 also noted that the plant had begun commercial deliveries.Mirae Asset
Nine-month results against the annual plan
For the first nine months, revenue was nearly VND 12,884 billion, up 10% year on year. Pre-tax profit was above VND 373 billion and net profit above VND 250 billion, up 22%.Vietstock These are consolidated figures for Nam Kim Steel Joint Stock Company. According to Mirae Asset, Q3 results were supported by higher export volumes and a sharp rise in average selling prices.Mirae Asset
The 2026 plan approved by the shareholders' meeting calls for revenue of VND 22,000 billion and pre-tax profit of VND 400 billion.CafeF The two targets are moving at different speeds.
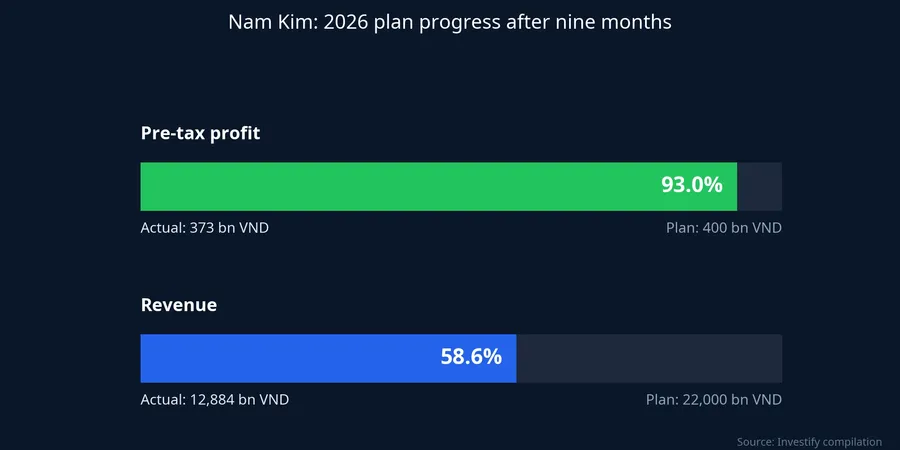
Pre-tax profit of VND 373 billion is already about 93% of the annual plan, so Q4 needs only about VND 27 billion more. Revenue of VND 12,884 billion is only about 58.6% of plan. To reach VND 22,000 billion, Q4 needs about VND 9,116 billion, nearly 1.7 times the VND 5,472 billion booked in Q3.
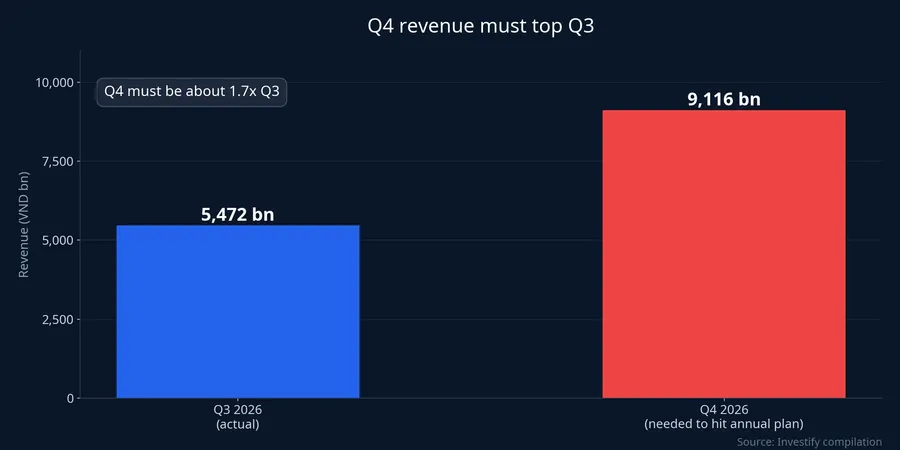
Q4 is also the first quarter with Phu My running after the opening, so the gap in revenue is the first place to see how much extra product the new plant puts on the market. Note that this is arithmetic against the plan the shareholders approved, not a forecast from the company or from any brokerage.
Demand: more than 70 markets and rising trade barriers
Nam Kim's products are sold in more than 70 countries and territories.Tạp chí Tài chính For a company selling into that many markets, trade-defense measures in large markets bear directly on how it fills new capacity.
The week before the opening, the European Commission issued Implementing Regulation (EU) 2026/2547, imposing a definitive 16% anti-dumping duty on Vietnamese cold-rolled steel, effective November 17, 2026.CafeF The measure covers certain flat cold-rolled products originating in Vietnam, and some products are excluded, so the impact on Nam Kim depends on whether its shipments to Europe fall within that scope. It is worth noting that cold-rolled steel is exactly the product group Phu My adds to Nam Kim.
More broadly, Vietstock says the coated-steel sector faces growing barriers from protectionism, especially in the US and Europe. When exports get harder, companies must compete at home or find new markets with thinner margins than the US offers.Vietstock
Input costs are edging up too. Hot-rolled coil, the main raw material for cold-rolled and coated steel, stood at USD 1,429 a tonne on November 19, about 4.5% above USD 1,368 on October 20. Higher raw-material prices can lift selling prices, but they also raise the working capital needed for every tonne as the plant ramps up.
Where the ramp-up costs will show
Once a plant enters service, depreciation starts flowing into cost of goods sold, and project loan interest is no longer capitalized but charged straight to financial expenses. Both run on the calendar, while revenue grows only with the tonnes actually sold. That is why the period when a plant runs below capacity is typically when margins are squeezed, before they improve as volume builds.
Brokerages read this stage in two ways. Vietcap, in a late-October report, said export recovery and Nam Kim Phu My could support long-term growth, but early-stage interest and depreciation costs, domestic competition and high raw-material prices will weigh on 2027 profit.Vietcap Mirae Asset stressed that the plant has begun commercial deliveries and said it expects to raise its 2026 earnings forecasts.Mirae Asset The two views are not mutually exclusive: Mirae Asset speaks to this year, Vietcap to next year, when the new plant's costs show up more fully.
On the market, NKG closed at VND 12,150 on November 20.
The markers that will answer the question
The thesis here is simple: the capital spent and the capacity built are done, and from now on the plant's value depends on tonnes sold. The Q4 2026 financial statements will be the first to reflect Phu My after the opening, with three lines worth reading together. First, Q4 revenue against Q3's VND 5,472 billion and the roughly VND 9,116 billion needed to hit the annual plan. Second, sales volume, if the company discloses it, to separate growth from price and growth from tonnes. Third, financial expenses and gross margin, where the new plant's depreciation and interest appear.
If Q4 revenue rises clearly from Q3 while gross margin holds, the new capacity has started to carry its own costs. If revenue stays flat while gross margin narrows, the plant is still waiting for orders, and the quarters of 2027 are where the story gets answered.