
On 13 November 2026, Sacombank's (STB) board approved a private bond issue to raise Tier 2 capital, up to VND 10,000 billion in total, to be issued within 2026. The bonds are non-convertible, carry no warrants and are unsecured: subordinated debt of the bank.Doanh Nhân Trẻ
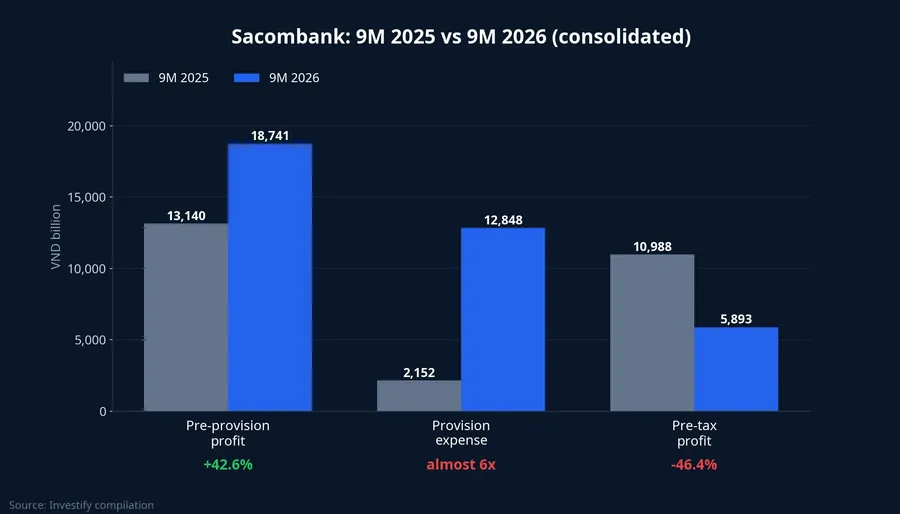
The nine-month numbers pull in two directions. Pre-provision profit rose 42.6% to VND 18,741 billion, customer deposits grew 25.4% from the start of the year, and consolidated pre-tax profit of VND 5,893 billion is about 73% of the VND 8,100 billion full-year plan. On the other side, pre-tax profit fell 46.4% year on year because provisioning expense jumped. The new VND 10,000 billion sits between those two halves, and it is the third bond plan the board has approved since late June. To read it properly, start with the chain of issues that came before.
June to August: longer tenors, coupons up to 10%
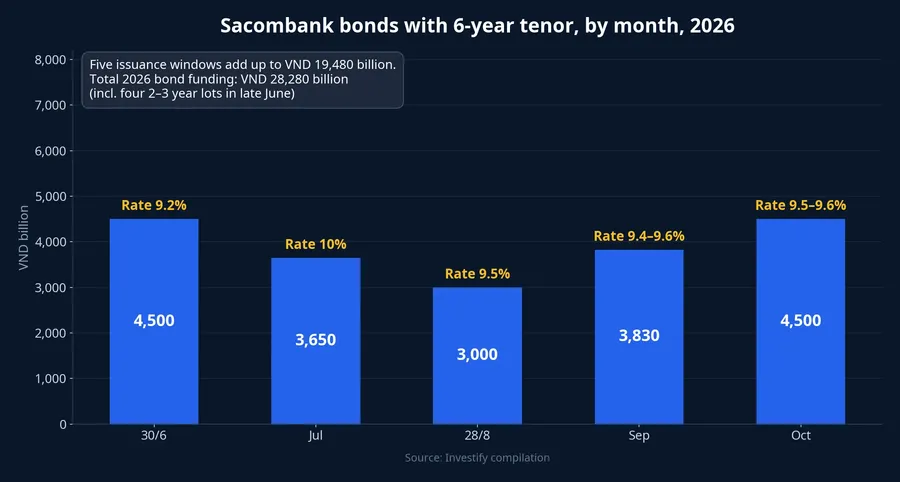
In the last week of June Sacombank issued four lots with 2–3 year tenors, VND 8,800 billion in total.StockBiz On 26 June the board approved a private Tier 2 bond plan of up to VND 20,000 billion. Four days later the bank sold lot STB12605: VND 4,500 billion, 6-year tenor, fixed 9.2% a year. From that lot on, every issue has had a tenor of 6 years or more.
In late July, three lots totalling VND 3,650 billion were sold at a fixed 10% a year, the highest coupon of any lot this year.Thương hiệu & Công luận On 28 August came two more lots, VND 2,000 billion and VND 1,000 billion, at 9.5%.Thời báo Tài chính The outstanding balance of promissory notes and bonds reached VND 18,300 billion at end-June, up from about VND 5,000 billion at end-Q1.
September: credit changes pace, and a public offering is added
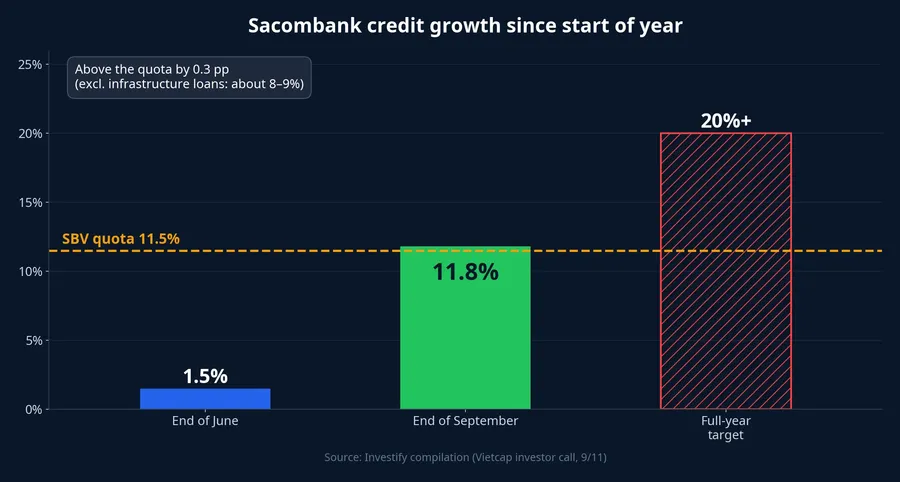
Q3 is when Sacombank's lending pace changed most visibly. At end-June credit had grown just 1.5% from the start of the year. By end-September it was 11.8%, above the 11.5% quota set by the State Bank of Vietnam. According to Vietcap, some loans disbursed in the quarter went to infrastructure projects that do not count toward the quota; excluding them, credit growth was about 8–9%. The bank expects full-year growth of 20% or more.Người Quan Sát
On the funding side, customer deposits reached VND 775,422 billion, up 25.4% since the start of the year and more than twice the pace of lending.Tin nhanh chứng khoán
In September the bank sold four bond lots worth VND 3,830 billion at 9.4–9.6% a year. In the same month it settled two older 2-year lots carrying 6%, so maturing debt is being replaced with longer paper costing roughly 3.5 percentage points more.Nhịp sống kinh doanh
On 29 September the board also approved a public offering of up to VND 15,000 billion in bonds with 7- and 10-year tenors, in three tranches from Q4 2026 to Q4 2027, which can be offered only after the State Securities Commission issues a registration certificate. The coupon is floating: the average 12-month deposit rate of four state-owned banks plus a margin. The bonds would be distributed through Sacombank branches and transaction offices, so ordinary savers at the counter could be invited to buy.Thời báo Tài chính
October and 13 November: from VND 28,280 billion to up to VND 10,000 billion more
In the second half of October three lots (16, 26 and 28 October) of VND 1,000 billion, VND 2,000 billion and VND 1,500 billion were sold, all with 6-year tenors and coupons of about 9.5–9.6%. Total bonds raised in 2026 reached VND 28,280 billion, including the four 2–3 year lots from late June.Nhịp sống kinh doanh The 6-year-plus lots alone, summed lot by lot, come to roughly VND 19,480 billion, close to the VND 20,000 billion ceiling of the June plan (a lot-by-lot sum, not allocated by plan).
The 13 November plan returns to the private format and leaves only about seven weeks to complete it. For scale, in all of October the bank sold VND 4,500 billion of long-dated bonds.
Why 25.4% deposit growth still calls for Tier 2 capital
Deposits fund lending, but they are not capital. The capital adequacy ratio is measured on own capital, which combines Tier 1 (charter capital, retained earnings) and Tier 2, including eligible subordinated bonds. As loans grow, risk-weighted assets grow with them, and the bank needs matching capital. Sacombank states the purpose of the issue as topping up own capital and supporting its financial capacity and capital-safety ratios.
Now the profit side. Pre-provision profit for nine months rose 42.6%, helped by service income of VND 8,206 billion (more than 3.5 times a year earlier) and operating costs down 19.3%. What pulled pre-tax profit down is provisioning expense: VND 12,848 billion, almost six times the VND 2,152 billion of the same period.Doanh Nhân Trẻ Pre-tax profit therefore fell 46.4% to VND 5,893 billion.CafeF
Net interest income fell 17.8% to VND 17,517 billion. Sacombank attributes this to a deliberate squeeze on its margin to cut lending rates for customers in line with Government and State Bank policy. Its nine-month NIM was 2.52%, down 1.09 percentage points year on year.
On bad debt, the end-Q3 ratio was 5.99% under Circular 31. On consolidated statements, NPLs over customer loans were 7.33%, versus about 6.41% at the start of the year. The bank believes overdue and new bad debt may have peaked in Q3 and has revised its year-end NPL target from about 4% to no more than 5%.Người Quan Sát
What STB shareholders and bondholders get
For STB shareholders, Tier 2 bonds differ from a share issue in that the number of shares outstanding does not change, so ownership percentages stay put. In return the bank pays interest every year. If the full VND 10,000 billion sold at the 9.5–9.6% of the October lots, annual interest would be roughly VND 950–960 billion (Investify estimate, before tax). That is about one-sixth of nine-month pre-tax profit but only around 5% of pre-provision profit over the same period, and it is deducted as an expense before profit is reported.
For buyers, a 9.5–10% coupon beats savings rates, but the terms are different. This is unsecured subordinated debt: if the bank runs into trouble, bondholders are repaid after depositors. A 6-year tenor is also far longer than a savings book. The 13 November issue is private, which by regulation is open only to professional securities investors. Ordinary depositors would meet this kind of bond only if the VND 15,000 billion public offering gets approved.
Total assets stand above VND 1.057 quadrillion, up 15.3% since the start of the year, so funding for lending is not short.Tin nhanh chứng khoán The bonds do a different job: they add own capital so lending can keep growing while capital ratios stay within limits.
Two yardsticks to watch
Between now and 31 December, each lot issued under the 13 November plan carries a results report filed with HNX showing the amount sold, coupon and tenor. That is the first yardstick. If the full VND 10,000 billion sells at around 9.5%, demand for Sacombank paper is holding. If it falls short, or the coupon has to go above the 10% of July, the cost of this Tier 2 chain is rising.
The second is the capital adequacy ratio in the Q4 2026 financial statements, expected in early 2027, read against the 20%-plus full-year credit growth the bank is aiming for. The same report will show whether the NPL ratio gets below 5%, the revised target.