
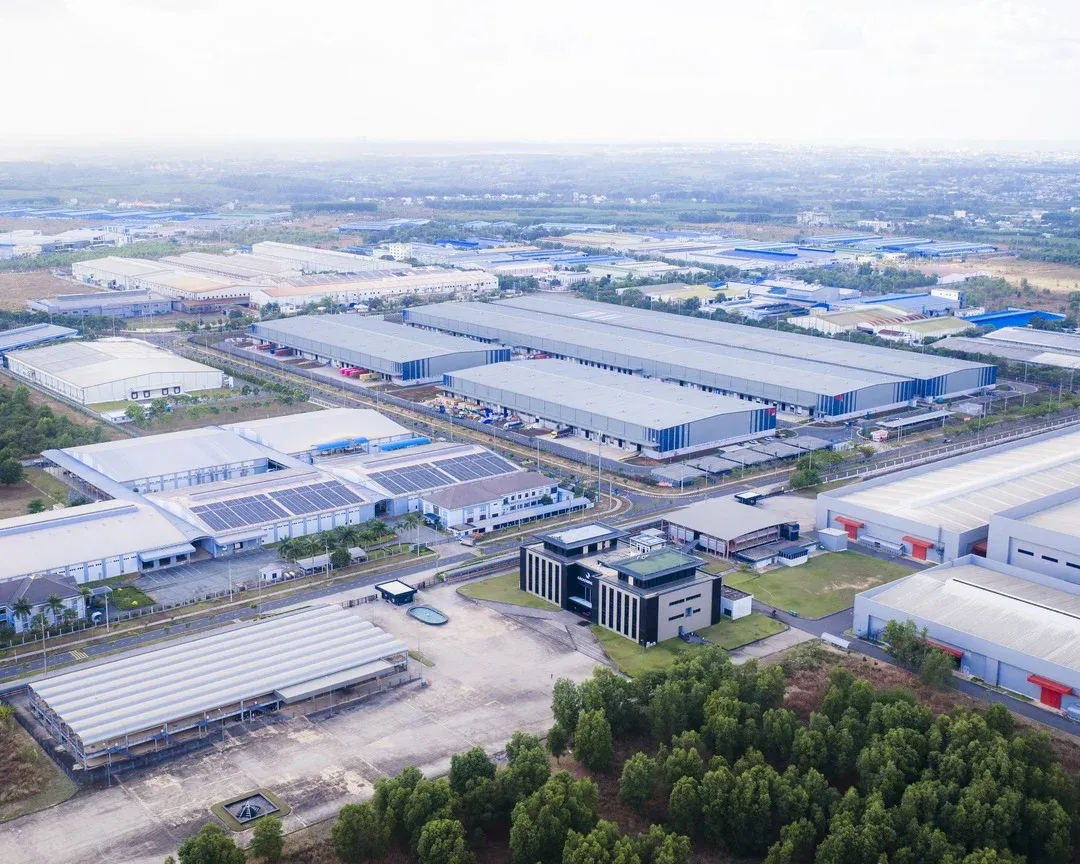
Leasable land at the Giang Dien industrial park, the main revenue source of Sonadezi Giang Dien JSC (UPCoM: SZG), is down to about 42 ha. To secure land for the years ahead, SZG's board has put a proposal to an extraordinary shareholder meeting on December 3: take over 100% of Phuoc Binh Investment Co., Ltd., developer of the Phuoc Binh industrial park in Phuoc Thai commune, Dong Nai, for a lump sum of up to VND 2,800 billion, excluding VAT.Nguoi Dua Tin
This is a proposal to shareholders, not a decision. And if approved, the deal does not happen in a day: it runs from a sub-lease signed in early 2025 to the point where the new site starts leasing in 2028. Reading it milestone by milestone shows holders of SZG shares exactly where the company's reports will change.
Starting point: a 35 ha sub-lease
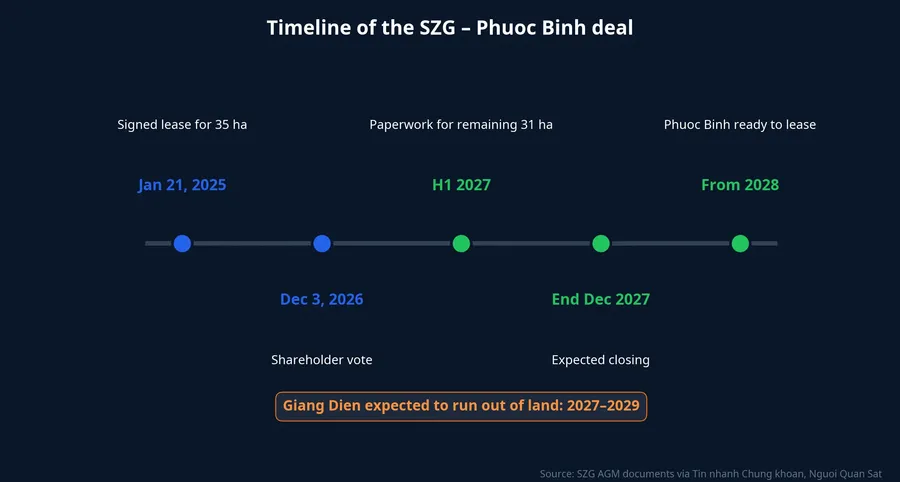
Before the offer to buy the whole company, SZG was already tied to Phuoc Binh through a business cooperation contract signed on January 21, 2025. Under it, SZG sub-leases 35 ha in the park at about USD 140 per square metre.Tin nhanh Chung khoan By the time the meeting documents were published, SZG had disbursed VND 618.26 billion under the contract. According to Nguoi Dua Tin, 35 ha covers SZG's business needs for only about two years, which is the reason the company gives for going further and buying the developer outright.Nguoi Dua Tin
December 3, 2026: the shareholder vote
The proposal contains these main points.
- Target: 100% of the charter capital of Phuoc Binh Investment Co., Ltd., acquired from its existing members. Phuoc Binh has charter capital of VND 600 billion. If the deal closes, it becomes a single-member LLC wholly owned by SZG.
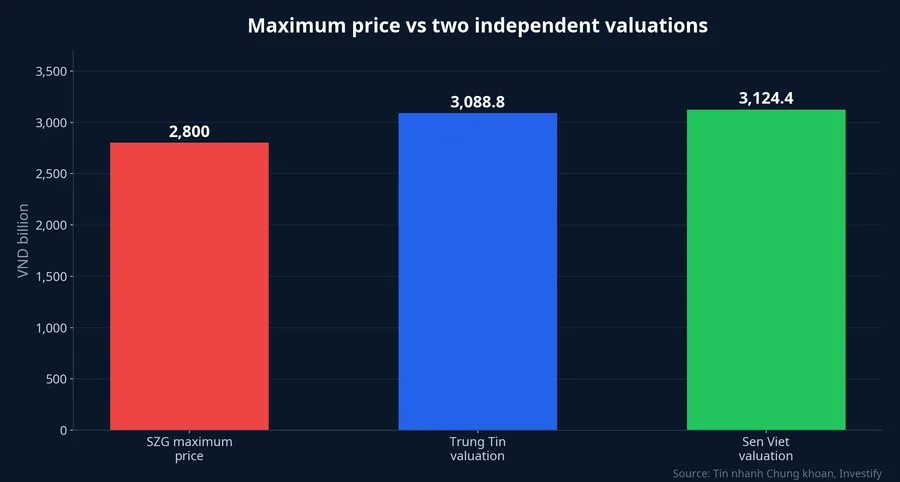
- Price: up to VND 2,800 billion, excluding VAT. The figure includes compensation costs for the remaining land and the cost of completing all infrastructure, which the seller carries out, but excludes raw land rent and management fees.Tin nhanh Chung khoan
- Valuation basis: SZG hired two independent appraisers. Sen Viet Appraisal JSC arrived at VND 3,124.4 billion using the asset method, and Trung Tin Appraisal JSC at VND 3,088.8 billion using the residual method. The maximum price is roughly 10.4% and 9.4% below those two results.
Spread over about 139.67 ha of leasable industrial and warehouse land, the maximum price works out to roughly VND 20 billion per hectare, or about VND 2 million per square metre (VND 2,800 billion divided by 139.67 ha), before raw land rent.Nguoi Dua Tin
On scale, SZG's total assets at June 30, 2026 were VND 5,103.29 billion, so the maximum outlay equals about 54.9% of total assets. A transaction of this size falls under the general meeting's authority under the company charter, which is why an extraordinary session is needed.
First half of 2027: the rest of the Phuoc Binh land
The Phuoc Binh park covers 189.99 ha, with total project investment of VND 1,501.08 billion and a 50-year operating term from July 24, 2026. Per Nguoi Quan Sat, compensation and site clearance has covered nearly 159 ha, and the remaining 31 ha or so is expected to finish paperwork in the first half of 2027.Nguoi Quan Sat
At this point SZG does not yet own Phuoc Binh. Nothing on SZG's balance sheet changes apart from the VND 618.26 billion under the cooperation contract, which stays where it is.
2027–2029: Giang Dien runs out of land
The Giang Dien park is SZG's main product, generating its revenue and profit. According to the meeting documents as relayed by Tin nhanh Chung khoan, remaining commercial land is about 42 ha and is expected to be sold out between 2027 and 2029. SZG itself says that as this land runs down, income from its core business risks being interrupted.Tin nhanh Chung khoan
The company also offers market context: industrial parks in Dong Nai have an occupancy rate of 73.1%, the region's highest asking rent at USD 189.6 per square metre per lease cycle, and competing supply is expected to rise in 2027–2029. These are Dong Nai-wide figures, not Giang Dien's own.
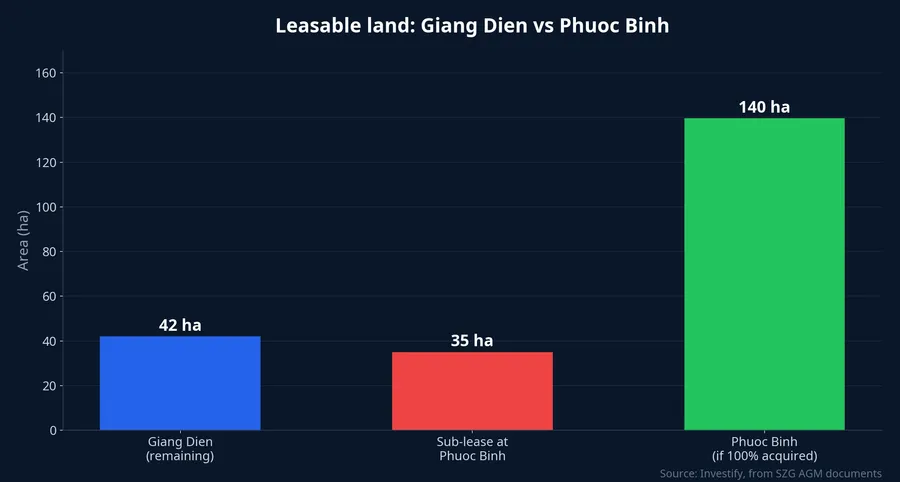
This is the most important stretch on the timeline. If the 42 ha is leased out early, in 2027, there will be a period when SZG has no new land to sign at Giang Dien while Phuoc Binh cannot yet lease. If leasing is slower and Giang Dien lasts until 2029, the two land banks will overlap.
End of December 2027: closing, if conditions are met
The deal is expected to close at the end of December 2027. The conditions: Phuoc Binh completes 100% of its infrastructure and legal procedures, terminates the business cooperation contract, carries no bank debt, and has settled or resolved its payables before handover.Nguoi Dua Tin
This design places most construction and legal risk on the seller: SZG receives a park with finished infrastructure and no debt. In return SZG has to wait, because the land only passes to the company once every condition is met. This is also where SZG's balance sheet changes most visibly: under the proposal to shareholders, the VND 618.26 billion already disbursed would be refunded with 8% annual interest, and the cooperation contract wound up.Tin nhanh Chung khoan
The money trail: where VND 2,800 billion comes from
At June 30, 2026, SZG had no bank debt and held about VND 1,247.6 billion in cash and short-term financial investments, not counting the VND 618.26 billion already disbursed under the cooperation contract.Nguoi Dua Tin Together that is about VND 1,865.9 billion available for the deal. The remaining gap of about VND 934.1 billion (2,800 minus 1,865.9) is expected to be covered by accumulated operating cash flow and bank loans.
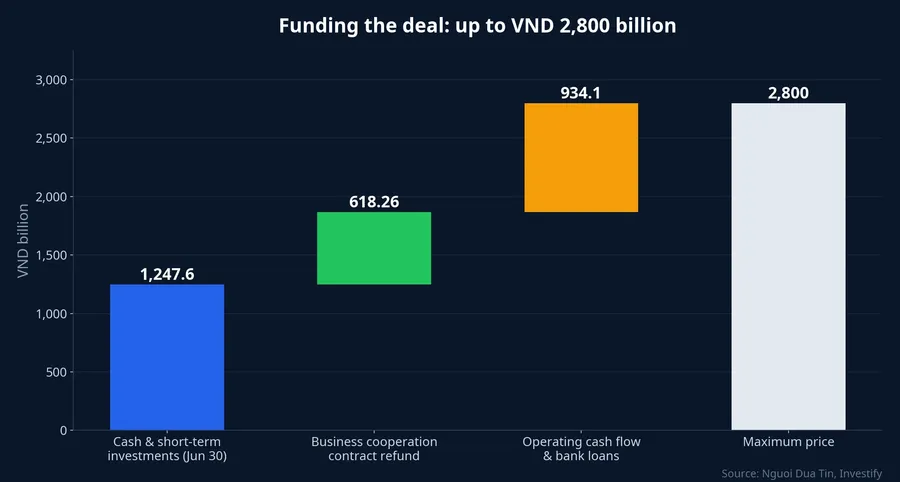
Some press reports put total funding after the refund of the cooperation contract at about VND 2,181.7 billion. Adding up the items disclosed does not produce that number: VND 2,181.7 billion is exactly VND 2,800 billion minus VND 618.3 billion, the cash still to be spent after offsetting what was already disbursed. This article uses the direct calculation, a gap of about VND 934.1 billion.
Since the deal closes at the end of 2027, SZG has more than a year to build operating cash flow before it must pay out most of the money. How much comes from operations and how much from banks will decide how far SZG moves from no debt to some.
Trading results while waiting
In Q3 2026, SZG reported net revenue of VND 104.1 billion, down 7.9% year on year, and profit after tax of VND 63.2 billion, down 11.1%. For nine months, profit after tax was VND 174.8 billion, down 6%.Tin nhanh Chung khoan
SZG attributes the decline mainly to provisions for trading securities, which pushed Q3 financial expenses to VND 13.1 billion from about VND 33.7 million a year earlier. Selling expenses rose to VND 15.9 billion from VND 579 million because the 2026 plan includes an extra 20 ha of leased land, double the prior-year period, which triggered brokerage commissions. Financial revenue rose 114.5% to VND 34.3 billion on interest from term deposits.
That last detail bears directly on the deal. Financial revenue currently comes from the large deposit balance; once cash is spent on the acquisition, deposit interest will shrink, and if bank loans are taken, interest expense will appear.
2028 onward: Phuoc Binh starts leasing
Phuoc Binh is expected to qualify for land leasing from 2028. By SZG's estimate, about 139.67 ha of commercial land meets leasing demand for 8–9 years.Nguoi Quan Sat As the company frames it, compared with continuing the 35 ha cooperation contract, buying 100% of the equity gives SZG control of the entire land bank and more freedom over investment and business decisions.
How an SZG shareholder can read this deal
If approved and completed on schedule, SZG swaps about VND 1,865.9 billion in cash and the cooperation contract, plus some borrowing capacity, for about 139.67 ha of leasable land with infrastructure finished, at a price roughly 9–10% below two independent valuations. The balance sheet moves from cash-rich and debt-free to less cash, possibly some debt, and a new land bank. The VND 618.26 billion disbursed under the cooperation contract also gets a concrete exit.
The main risk lies in timing, not price. The seller must finish infrastructure and legal work before the deal closes, and the new land can only be leased from 2028. If Giang Dien runs out of land in 2027, or Phuoc Binh runs behind plan, SZG's land-leasing revenue will have a gap.
Three indicators will show whether the two land banks join up. The remaining area at Giang Dien in SZG's quarterly reports shows the pace at which the old land bank is running down. Progress on the remaining 31 ha of paperwork at Phuoc Binh in the first half of 2027 shows whether the new park is on schedule. And bank loans appearing on the balance sheet from 2027 show whether the VND 934.1 billion gap is filled with operating cash or debt. The December 3 vote is the first answer to whether the deal goes ahead at all.