
If Construction Joint Stock Company No. 9 (VC9, listed on HNX) sells every share in the private placement its board has just cleared for rollout, all of today's shareholders combined would hold only about 8.49% of the company.CafeF The rest, more than nine-tenths, would belong to at most 20 investors whose names nobody yet knows.
At this scale, a capital raise is really a question of who controls the company. This post starts from that arithmetic and works down to the mechanics: where the money is meant to go, and what the law says about a buyer who ends up with 25% or more.
What the October 5 resolution says
According to CafeF, on October 5, 2026 the VC9 board issued a resolution to proceed with a private placement of 180 million shares at VND 10,000 each.Tin nhanh chứng khoán Buyers are up to 20 professional domestic securities investors. The sale is planned between Q4 2026 and Q1 2027, once the State Securities Commission notifies that it has received a complete filing. The new shares are barred from transfer for one year after the offering closes.
If everything sells, VC9 raises VND 1,800 billion and charter capital rises from VND 170 billion to about VND 1,970 billion.VietnamBiz
The articles recounting the resolution do not say which shareholder meeting approved the plan, or when. Holders should look for that in the company's own disclosures, because it bears directly on the tender-offer rule discussed below.
The dilution math
VC9 has 17 million issued shares, of which 304,800 are treasury shares and almost 16.7 million are outstanding. The new offering is about 10.78 times the shares outstanding.CafeF
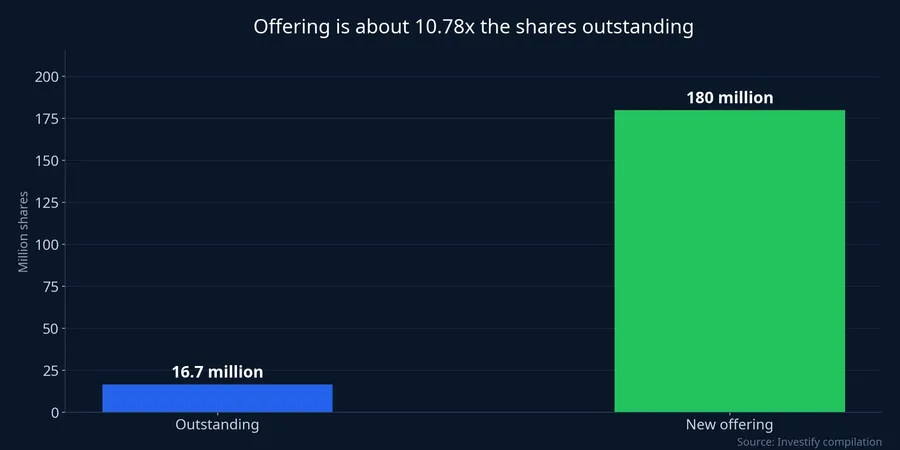
The addition is simple. Almost 16.7 million old shares plus 180 million new ones gives about 196.7 million shares outstanding, assuming treasury shares stay unchanged. Existing shareholders would then hold about 8.49% in total, and the new buyers about 91.51%.
The largest shareholder shows the shrinkage most clearly. TNG Investment and Construction Co., Ltd. holds more than 6.2 million shares, or 36.53% of charter capital.Tin nhanh chứng khoán If it buys nothing more in this round, its stake in the enlarged capital falls to about 3.15%.CafeF
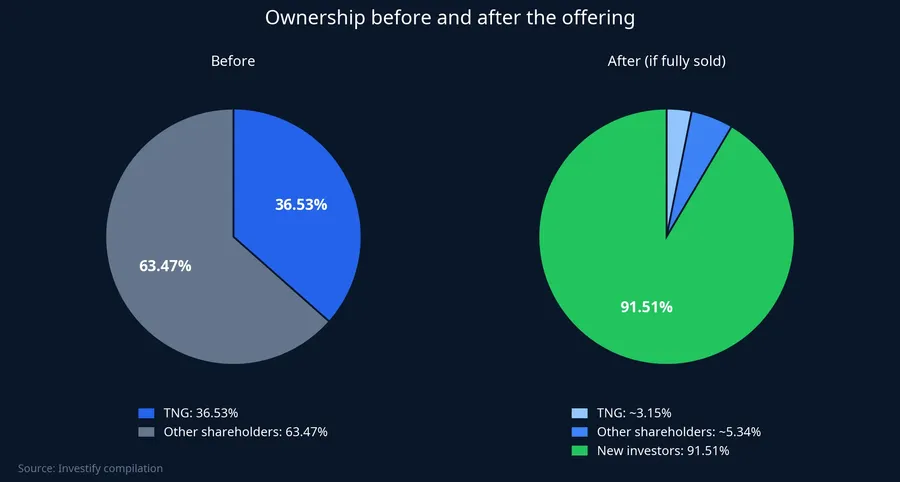
A small investor holding 1,000 shares follows the same ratio. The share count in the account stays the same, but each share now represents roughly one-twelfth of the ownership it did before.
Unlike a standard rights issue, existing shareholders get no pro-rata right to subscribe. The new shares are offered only to a selected group of professional investors, so a VC9 holder who wants to keep their percentage has no route to do so in this offering.
Why this is about control, not just capital
In private placements of a few dozen percent, existing holders are diluted but keep a majority. At VC9 the balance flips completely. After the sale, every vote at the shareholder meeting, from electing the board to approving the business plan, would be decided by the new investor group. The old shareholders combined, TNG included, would not have enough votes to block any resolution.
The buyers' identities are not yet known. Who holds VC9 after this round can only be answered once the company discloses the investor list and the results. If the 180 million shares go to one or a few institutions, VC9 effectively changes hands. If they are spread across nearly 20 investors, control depends on whether those investors are related to one another.
Offer price, the money and the size of the business
The VND 10,000 price is far above the market. VC9 closed at VND 4,300 on October 7, so the offer price is about 132.6% higher.Tin nhanh chứng khoán At the October 9 close of VND 4,500, the offer price is about 2.22 times the market price.
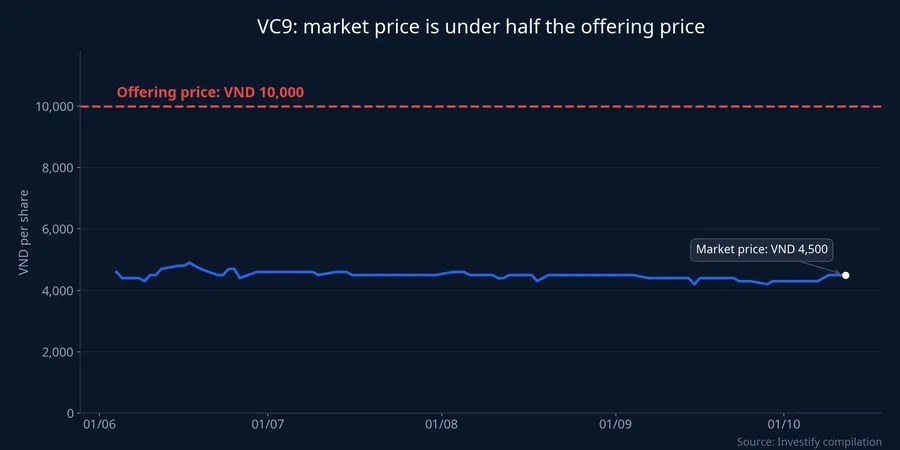
At that price the whole listed company is valued at about VND 75 billion.CafeF The VND 1,800 billion it wants to raise is about 24 times that market capitalization.
Set beside operating results, the gap widens. In the first half of 2026, VC9 booked net revenue of VND 101 billion, up 35% year on year, and net profit of about VND 498 million.VietnamBiz That profit did not come from construction. Gross profit for the half was only about VND 0.97 billion, core operations lost about VND 7.3 billion, and other income of about VND 7.8 billion pushed the result into positive territory. According to the company's explanation as relayed by VietnamBiz, other income rose on proceeds from fixed-asset disposals.
At June 30, 2026, VC9 still carried accumulated losses of VND 101.9 billion, equal to 59.94% of charter capital.Tin nhanh chứng khoán Equity is about VND 64.7 billion against total assets of about VND 727.5 billion. The stock has also been on the warning list because of accumulated losses as of December 31, 2025.Vietstock
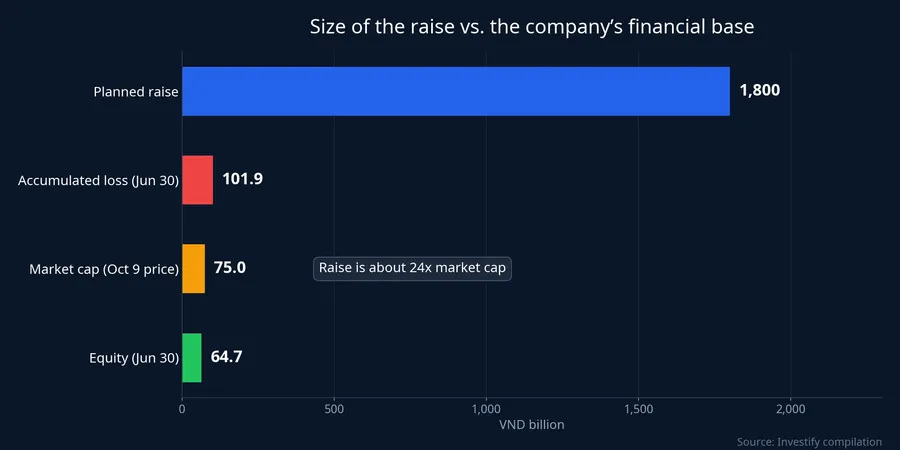
The numbers show one thing: the planned raise is many times the company's entire current scale. This post does not speculate on why an investor would pay VND 10,000 for a share trading near VND 4,500. Whoever puts money into this round is buying what is almost a new company, tied to one specific project.
Where the money goes: the Chi Dong urban area
Under the plan, all VND 1,800 billion is earmarked for the Chi Dong urban area in Quang Minh commune, Hanoi, to be disbursed over 2026 to 2027.CafeF As of June 30, 2026, VC9 had booked VND 82.7 billion of long-term work-in-progress costs on the project.Tin nhanh chứng khoán
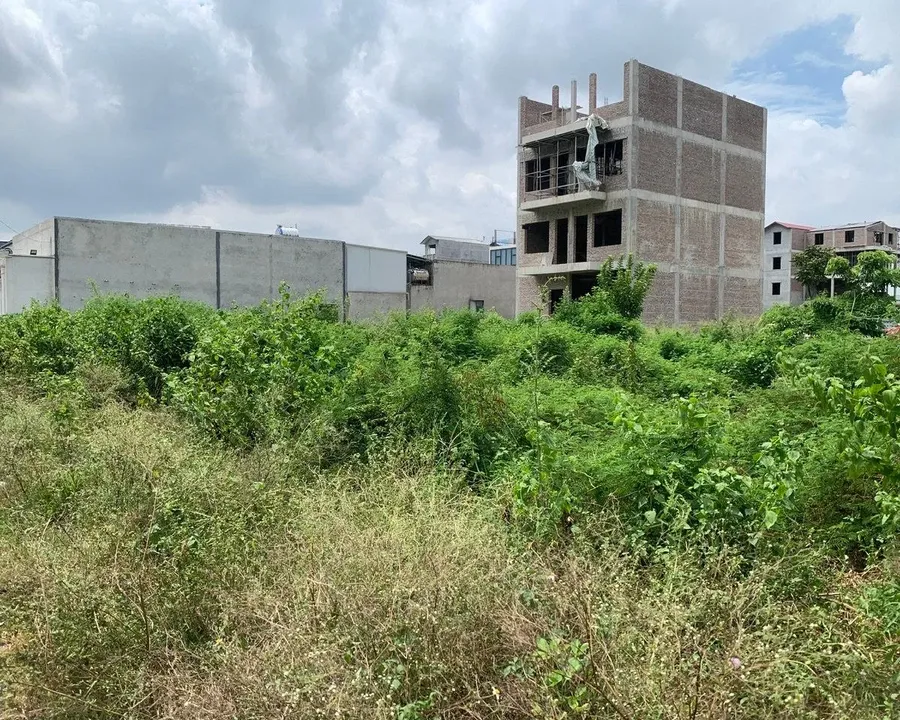
The two outlets report the project's size differently. Tin nhanh chứng khoán gives 68.87 hectares with total investment of VND 558.6 billion, while CafeF gives 46.8 hectares in total, with phase two expected to start construction in 2027 to 2028. The VND 1,800 billion is more than three times the VND 558.6 billion total investment figure, and the articles do not say whether the project's total investment has since been revised.
On the legal side, the biggest recent step came on January 20, 2026, when the Quang Minh commune People's Committee issued Decision 201/QĐ-UBND approving a partial adjustment to the 1/500 detailed plan. A long list remains: adjusting the investment approval (including extending the schedule), continuing compensation and site clearance, applying for land allocation, meeting land-related financial obligations, and only then design and construction. The company has also raised the option of finding a financially capable partner to co-invest or to take over part of the project.
So the proceeds would flow into a project with many legal steps still unfinished. How fast VND 1,800 billion can be disbursed over two years depends on how fast those procedures are completed.
What the law says when one buyer reaches 25%
Under Article 35 of the 2019 Securities Law, an organization or individual, together with related persons, who plans to buy outstanding shares that would take them to 25% or more of the voting shares of a public company must make a tender offer.Hệ thống pháp luật A tender offer means the buyer makes a public offer to purchase, and every shareholder has the chance to sell to them.
The same article contains an exemption: a buyer of newly issued shares who crosses those thresholds under an issuance plan approved by the shareholder meeting does not have to make a tender offer.
For a VC9 holder, this means that if the plan has been through the shareholder meeting and one investor receives 25% or more in the placement itself, that investor could become the controlling shareholder without small shareholders ever receiving an offer to buy their shares. This post does not speculate on how VC9 will allocate the shares. Only the investor list and each investor's allocation will answer that.
What to watch
The conclusion here is plain: at nearly 11 times the shares outstanding, this offering transfers control of VC9 to a new investor group rather than topping up capital in the ordinary sense. Existing shareholders, including the largest one, would no longer have a deciding voice once the sale is complete.
Three milestones will show how it plays out. The first is the State Securities Commission's notice that it has received a complete filing, the condition for the sale to begin. The second is the published investor list, which will show whether the 180 million shares go to one group or are split among many. The third is the offering result in Q4 2026 to Q1 2027, which will show how many shares are actually sold.
If only part is sold, dilution will be below 91.5%. Even so, with an offering nearly 11 times the current share count, selling just over 16.7 million shares is enough for the new buyers to hold more than half the company.