
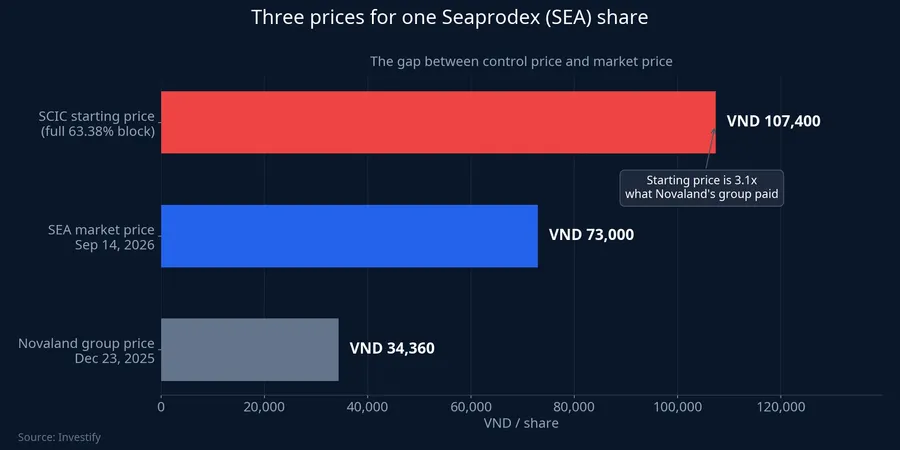
On September 29, the Hanoi Stock Exchange will auction the entire 79,228,000-share block of Seaprodex that SCIC holds, equal to 63.38% of charter capital, with a starting price of VND 8,509 billion for the whole block.Tin nhanh Chứng khoán That works out to roughly VND 107,400 per share, nearly 47% above the VND 73,000 at which SEA is currently trading on UPCoM.Fili Plenty of retail investors are reading that gap as a bargain: buy now, below the price the state itself set. What that reading skips is that the two numbers measure two entirely different things, and subtracting one from the other to get a "47% discount" is wrong from the start.
Why SEA has been climbing for a month
SEA sat flat around VND 51,000 through early August, then two consecutive ceiling-up sessions on August 11 and 12 pushed it to VND 65,600. A 13.10% jump on September 3 was followed by a close of VND 78,200 on September 4, the peak of the run and 53% above the level three weeks earlier. Six sessions of gradual pullback followed, closing at VND 73,000 on September 14.
The rally doesn't trace to a single cause. Seaprodex also set a cash dividend record date of VND 500 per share for September 22, and a balance sheet with almost no debt makes the stock an easy fit for the "hidden asset" bucket. But both of those had been true for a while; the price only broke out the week the divestment auction story firmed up, on volume several times the average. The data leans heavily toward the auction as the main driver, though not the only one.
Four reasons the 107,400 vs. 73,000 comparison breaks down
VND 107,400 is the price of control, sold as one indivisible block. Buyers have to take all 79,228,000 shares at once, and anyone wanting to bid has to post a deposit equal to 10% of the block's value at the starting price — VND 850.9 billion — by 3:30 pm on September 22.Báo Đấu thầu The premium in that price buys the right to pick a development partner for the land, to decide what happens to the asset portfolio, and to set dividend policy. A single share bought on the exchange comes with none of that.
The party that understands this company best paid far less. Per a disclosure dated December 27, 2025, Địa Ốc Ngân Hiệp bought more than 30 million shares to reach a 24.03% stake, and Đầu Tư Redwood bought more than 10.5 million shares to reach 8.44%, together worth nearly VND 1,395 billion, averaging roughly VND 34,360 per share.DoanhNhan.vn Ngân Hiệp is a subsidiary 99.98% owned by Novaland, and Redwood traces back to an entity Novaland set up in 2012. That VND 34,360 average was roughly 24% below the VND 40,500 market price at the same time. The group that understands the Đồng Khởi land best bought in below the market price then, not above it.
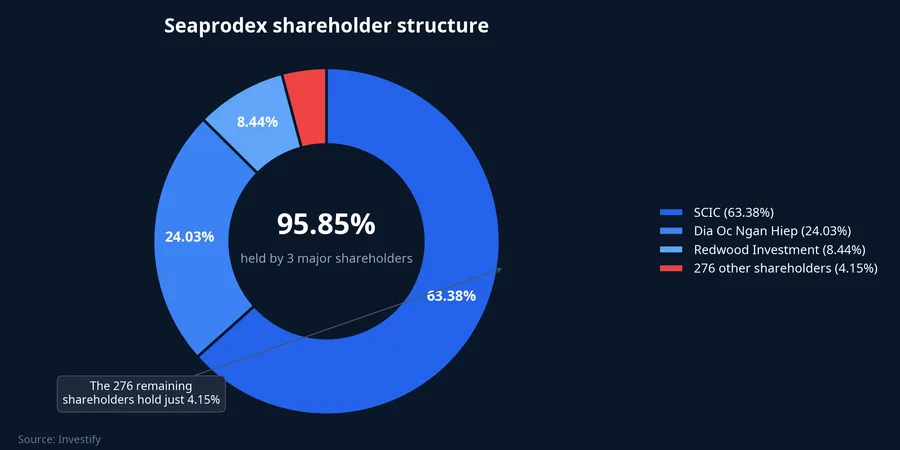
The exchange price is forming in a very shallow pool. Per a disclosure dated May 17, 2026, Seaprodex no longer meets the conditions for a public company: as of March 18, 2026 it had just 279 shareholders, with three large holders controlling 95.85% of voting shares and the remaining 276 shareholders holding just 4.15%, roughly 5.2 million shares.CafeF Average matched volume for SEA over the past month has been only around 22,300 units per session. At that scale, a few hundred million dong in buy orders is enough to push a stock with a market cap of over VND 9,100 billion to its daily ceiling: the two ceiling-up sessions on August 11 and 12 matched just 74,500 and 83,100 units respectively, worth less than VND 10 billion combined.
No mechanism forces the auction winner to buy out minority shareholders. Normally, when a buyer crosses 25% of voting shares in a public company, a mandatory tender offer kicks in, giving small shareholders a chance to sell at the same price. But share purchases through a state-capital divestment auction are exempt from that obligation.LawNet Whoever wins on September 29 pays VND 107,400 to SCIC and owes exchange shareholders nothing at that price.
The foundation is real; only the comparison is wrong
The argument circulating on forums has a real foundation, and it isn't unreasonable. The 2-4-6 Đồng Khởi plot is real: 1,522.2 m² across three street frontages in the heart of District 1, zoned for a mixed-use complex of hotel, commercial, office, and residential towers up to 20 stories.MarketTimes Seaprodex's balance sheet is clean too, with total assets of VND 2,905.1 billion and only VND 248.8 billion in liabilities at the end of Q2 2026, plus a 22.08% stake in Proconco worth roughly VND 1,143 billion.
But a real plot and a clean balance sheet don't make the comparison correct. VND 107,400 and VND 73,000 aren't measuring the same thing, so subtracting one from the other to get a "47% discount" is wrong from the start. The pair worth comparing is today's market price against what the party that understands the company best actually paid: VND 73,000 today versus VND 34,360 last December, not the starting price of a controlling block.
The knot neither side has untied
What's notable is that SCIC's own price is also valuing an asset with unresolved legal status. On the books, the 2-4-6 Đồng Khởi plot sits under construction-in-progress costs at roughly VND 692 billion, far below the value the VND 8,509 billion implies. Seaprodex paid its land-use fees back in January 2017, but as of June 30, 2026 it still hasn't received the land-use rights certificate, so the project can't move forward.Người Quan Sát Nine and a half years of paid fees, and the title still hasn't come through. The gap between the VND 692 billion book value and the value the starting price implies is essentially a bet that this legal knot gets untied, and untied within an acceptable timeframe. That's a risk sitting on both sides: the auction winner and the minority shareholders holding SEA on the exchange alike.
Who is actually carrying the risk
VND 73,000 on the exchange isn't "Đồng Khởi land being discounted 47%." It's the price a very small group of investors are paying each other, in a stock where only 4.15% of shares actually change hands freely, for a minority position with no say over what happens to that land.
That standard should apply to every "state-owned company sitting on prime land" stock: when free float sits below 5% and average liquidity is just a few tens of thousands of units per session, the listed price is a thin reference point, not a reliable market valuation. Retail investors buying at current levels are paying more than double — 112% above — what the group that understands this company best paid less than a year ago, in a stock where a few hundred million dong in buy orders is enough to send the price to its daily ceiling.
Three dates that will answer the rest
The evidence so far isn't enough to say whether the September 29 auction will succeed or fail. Worth remembering: SCIC first proposed divesting its 63% stake in Seaprodex back in 2020, and it has never gone through.Người Quan Sát Three upcoming dates should tell us more.
On September 22, the number of registered bidders and deposits filed with HNX will show whether any party is genuinely prepared to put up at least VND 8,509 billion. On September 29, the auction result will show how far above the starting price the winning bid lands, if the auction succeeds at all. After that comes the timeline for issuing the land-use rights certificate for 2-4-6 Đồng Khởi: the one variable that can turn paper value into real cash flow.
Until those three dates play out, retail investors should avoid using VND 107,400 as an anchor to convince themselves that VND 73,000 is cheap. The two numbers have never measured the same thing.